

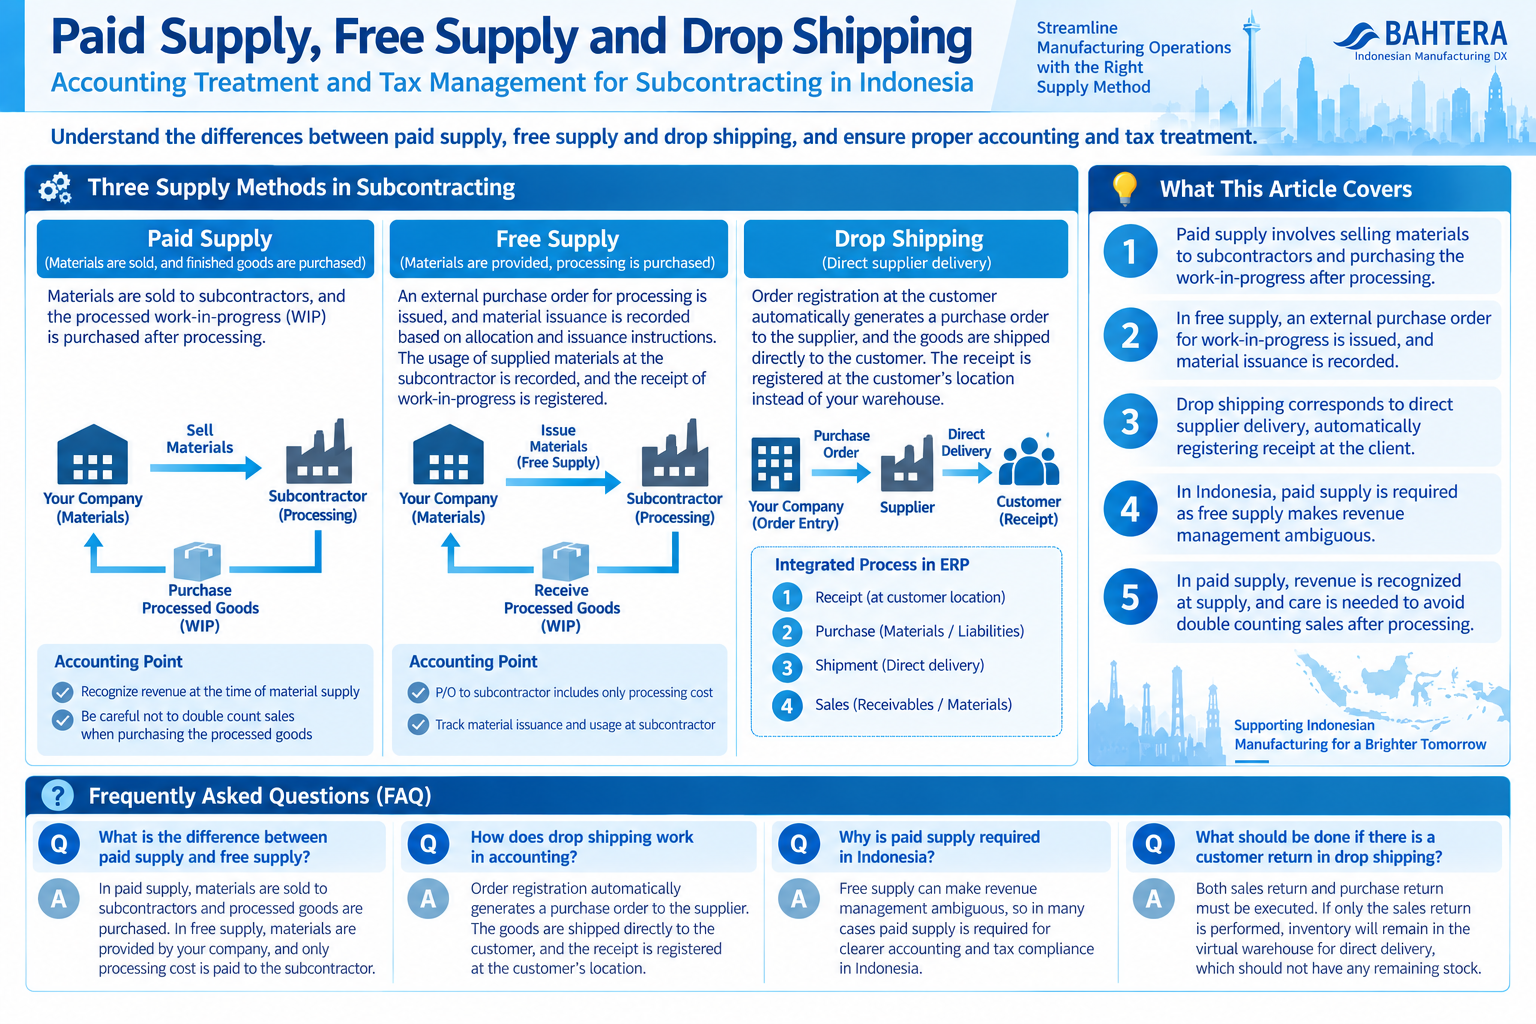
Paid supply is a method where materials are sold to subcontractors and the work-in-progress is purchased after processing. In the case of free supply, an external purchase order for the work-in-progress is issued, and the actual material issuance is recorded based on the allocation and issuance instructions. Then, the usage of supplied materials at the subcontractor is recorded, and the receipt of work-in-progress is registered.
-
-
Accounting Systems in Indonesia
The adoption rate of SaaS-based accounting systems in Indonesia is less than 8%, despite the advancement of SaaS technology. The continuous launch of new…
続きを見る
What this article covers
- Paid supply involves selling materials to subcontractors and purchasing the work-in-progress after processing.
- In free supply, an external purchase order for work-in-progress is issued, and material issuance is recorded.
- Drop shipping corresponds to direct supplier delivery, automatically registering receipt at the client.
- In Indonesia, paid supply is required as free supply makes revenue management ambiguous.
- In paid supply, revenue is recognized at supply, and care is needed to avoid double counting sales after processing.
Drop Shipping and Direct Supplier Delivery
From 2001 to 2007, while I was engaged in the furniture export business in Bali, I received numerous inquiries from people in Japan who wanted to start a new online business.
At the time, I felt averse to the idea of opening an online shop without holding inventory and with zero risk, but today, drop shipping has grown into a business known as affiliate marketing.
This drop shipping corresponds to the direct supplier delivery function in business systems, where order registration from client A automatically generates order information to supplier B, and the receipt is registered not in the company's warehouse but at client A's location.
It is easy to understand by imagining a triangular trade where the Japanese headquarters receives an order from the American branch, places an order with the Indonesian factory, and the Indonesian factory ships directly to the American branch.
When the ERP system integrates order and accounting functions, after order registration, direct supplier delivery registration allows the following four processes to be executed together.
- Receipt
- Purchase (Materials/Liabilities)
- Shipment
- Sales (Receivables/Materials)
If a return from the client occurs, both sales return and purchase return need to be executed. If only the sales return is performed, inventory will remain in the virtual warehouse for direct delivery, which should not have any remaining stock.
Supplying from Own Warehouse
The process flow for paid and free supply is the same, but the P/O price issued to the subcontractor includes material cost plus processing cost for paid supply, and only processing cost for free supply.
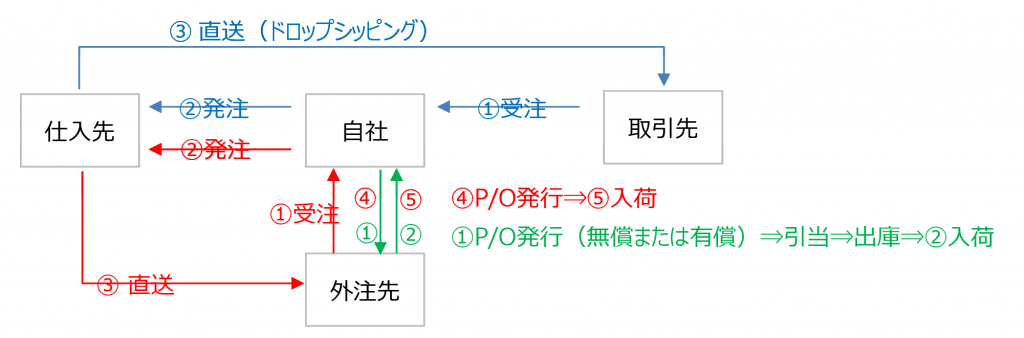
When recognizing revenue for paid supply, orders for materials from subcontractors are received, and material order registration to suppliers is performed. Materials may enter the company's warehouse or be shipped directly to the subcontractor.
- Order for materials from subcontractor (in case of paid supply)
- Order for materials to supplier
If materials are received in the company's warehouse, orders for subcontract processing, inventory allocation, and issuance to the subcontractor, and receipt processing after completion of processing at the subcontractor are performed. This flow is the same for both paid and free supply.
- Issue external purchase order (P/O) to subcontractor
- Allocate materials in the company's warehouse
- Issue material issuance instructions to subcontractor
- Record material issuance to subcontractor
- Record usage (input) of supplied materials at subcontractor
- Record receipt from subcontractor
From the perspective of transactions, the difference between in-house and outsourced production is as follows.
- In-house production: Input record ⇒ Production record
- Outsourced production: Supply record ⇒ (Input record ⇒) Purchase record
Paid Supply
In Indonesia, free supply makes revenue management ambiguous, so the tax office requires paid supply with profit. In the case of paid supply, revenue is recognized at the time of supply, and care must be taken to avoid double counting of sales when selling the processed product to the client.
Case: If materials are sold to a subcontractor for 120 and the processed product is sold to a customer for 200, there is a possibility of double counting sales.
- Sale of materials to subcontractor
(Dr) A/R 120 (Cr) Sales 120 - Sale of product to customer
(Dr) A/R 200 (Cr) Sales 200
Therefore, at the time of supply (material sale), it is recorded as accounts receivable (asset) and not as Sales (revenue plus), but materials are recorded as a negative, and when buying back after processing, accounts receivable is transferred to subcontract processing costs.
- Material purchase
(Dr) Materials 100 (Cr) A/P 100 - Sale of materials to subcontractor (company profit 20)
(Dr) Accounts Receivable 120 (Cr) Materials 100
(Cr) Material Supply Profit 20 - Completion of subcontract work (subcontractor profit 50)
(Dr) Subcontract Processing Cost 170 (Cr) A/P 50
(Cr) Accounts Receivable 120 - Sale of product to customer (company profit 30)
(Dr) A/R 200 (Cr) Sales 200
Free Supply
Outsourcing such as plating or pressing corresponds to the purchase of services (subcontract processing). Therefore, an external purchase order (P/O) for the service is issued to the subcontractor. Regarding the delivery of materials to the subcontractor, no journal entry occurs, but when the subcontract work is completed, a journal entry is made as subcontract processing costs. The specific journal entry example is as follows.
- Material purchase
(Dr) Materials 100 (Cr) A/P 100
- Delivery of materials to subcontractor
No journal entry
- Completion of subcontract work (subcontractor profit 50)
(Dr) Subcontract Processing Cost 50 (Cr) A/P 50
- Sale of product to customer (company profit 50)
(Dr) A/R 200 (Cr) Sales 200
Frequently Asked Questions | Differences Between Paid and Free Supply
In line with the content of this article, frequently asked questions are briefly organized.
What is the difference between paid and free supply?
Paid supply is a method where materials are sold to subcontractors and the work-in-progress is purchased after processing. Free supply is a method where materials are provided to subcontractors free of charge, and only processing costs are paid. Different journal entries are required for the accounting treatment of both.
What should be noted in the accounting treatment of paid supply?
In the case of paid supply, revenue is recognized at the time of supply, and care must be taken to avoid double counting of sales when selling the processed product. At the time of material sale, it is recorded as accounts receivable, and after processing, accounts receivable is transferred to subcontract processing costs.
How is the accounting treatment for free supply conducted?
In free supply, no journal entry occurs for the delivery of materials to the subcontractor. When the subcontract work is completed, a journal entry is made as subcontract processing costs. Specifically, subcontract processing costs are recorded on the debit side, and accounts payable on the credit side.