

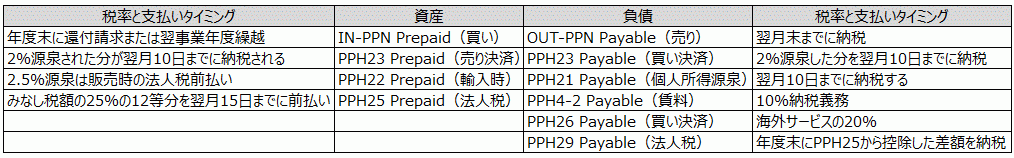
When implementing an accounting system, the minimum knowledge required about Indonesian taxation includes Value Added Tax (PPN) and Income Tax (PPh). However, Corporate Tax (PPh25) and Service Withholding Tax (PPh23) are comprehensive taxes (Non-Final), while Office Rental Income Tax (PPh4(2)) is a separate tax (Final).
-
-
Accounting Systems in Indonesia
The adoption rate of SaaS-based accounting systems in Indonesia is less than 8%, despite the advancement of SaaS technology. The continuous launch of new…
続きを見る
What this article covers
- Indonesia's Value Added Tax (PPN) is calculated using the invoice method.
- Before Japan's consumption tax increase, condominiums were selling rapidly.
- Indonesia's personal income tax (PPh21) is withheld from salaries.
- In transactions with system companies, invoices include 11% PPN.
- Foreign currency transaction tax journal entries use BI and Tax rates.
Value Added Tax PPN (Pajak Penambahan Nilai)
In Indonesia, PPN (VAT = Value Added Tax) is equivalent to Japan's consumption tax. Indonesia adopts the invoice method, calculating PPN payments and refunds based on Faktur Pajak (Tax Invoice). Output PPN charged at the time of sale and Input PPN charged at the time of purchase are offset. If Output PPN is higher, it must be paid by the end of the following month. If Input PPN is higher, a refund claim can be made at the end of the fiscal year or carried over to the next business year.
Non-residents may not have to pay PPN if they exceed a certain amount. In Jakarta, about 20 stores, such as souvenir shops in shopping malls, are designated as PPN refundable stores (for purchases over Rp.500,000 at the same store). However, it does not match Singapore's GST refund (over S$100 at the same store), and in Japan, consumption tax refunds of 8% are available not only at airports but also at drugstores.
Case: During an annual temporary return to Japan, shopping at Bic Camera and Matsumoto Kiyoshi results in a significant amount just from refunds.
Income Tax PPh (Pajak Penghasilan)
In Indonesian tax law, Income Tax (PPh) is very complex. While PPN is equivalent to Japan's consumption tax, PPN is a value-added tax and is also levied on production goods such as services and land. Income Tax PPh is divided into personal income tax and corporate income tax.
Produced goods and services are broadly classified into consumer goods and production goods according to their economic use. Goods and services demanded by households for consumption are called consumer goods, while those demanded by companies for production are called production goods. The same goods may be considered consumer goods or production goods depending on their use. (From "Kotobank")
Personal income tax is withheld from salaries under PPh21 (Article 21 of Law No.10/1994). Corporate income tax involves monthly payments of estimated tax amounts calculated from the previous year's income under PPh25 (Bulanan) and settling the difference at the end of the year under PPh29 (Tahunan). These are similar to the Japanese tax system, making them easy to understand.
Additionally, there are PPh23, which is withholding tax on service income obtained by Indonesian residents, PPh4(2) on office rental fees, and PPh26, which is withholding tax on service income obtained by non-residents of Indonesia. It is important for Japanese managers to be aware of these.
In Japan In Indonesia Features ERP
Corporate Income Tax PPh25, 29
Personal Income Tax PPh 21 Withholding tax on salaries Automatically calculated in Payroll system
Service Income Tax PPh 23 Withholding tax (residents) Automatically calculated at settlement
Service Income Tax PPh 26 Withholding tax (non-residents)
Transaction Examples (Sales and Purchases)
When a system company sells a computer for Rp.1,000,000 and installation fee for Rp.500,000, the total amount is Rp.1,500,000, but the invoice amount is Rp.1,665,000, including 11% PPN.
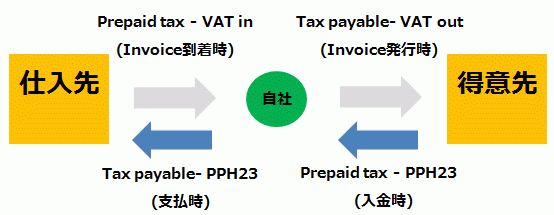
The customer deducts Rp.10,000, which is 2% of the installation fee Rp.500,000, as PPh23 and pays Rp.1,655,000, with the obligation to pay Rp.10,000 to the tax office (Kantor Pajak) by the 10th of the following month. The seller has effectively prepaid income tax in the form of withholding.
The customer issues a withholding tax slip (Bukti potong PPh pasal 23) to the system company, which can deduct that amount at the end of the year, having a "go-and-return" nature similar to PPN. Comprehensive taxation (PPh Non-Final Tax) refers to combining and offsetting with other income taxes like PPh23, which is a prepayment of undecided income tax.
On the other hand, separate taxation (PPh Final Tax) refers to taxes like PPh4(2), where the tax amount is determined by withholding at the payer's side.
System Company's Journal Entry
At invoice issuance: Tax payable - PPN out is a liability (obligation to record Output)
- (Debit) A/R 1,650,000 (Credit) Sales 1,500,000
- (Credit) Tax payable - PPN out 150,000
At settlement: Tax payable - PPh23 is an asset (prepaid income tax)
- (Debit) Bank 1,640,000 (Credit) A/R 1,650,000
- (Debit) Prepaid tax - PPh ART23 10,000
Customer's Journal Entry
Upon receiving invoice: Prepaid tax - PPN in is an asset (right to deduct from Output)
- (Debit) Purchase 1,500,000 (Credit) A/P 1,650,000
- (Debit) Prepaid tax - PPN input 150,000
At settlement: Tax payable - PPh23 is a liability (obligation to withhold and pay system company's income tax)
- (Debit) A/P 1,650,000 (Credit) Bank 1,640,000
- (Credit) Tax payable - PPh ART23 10,000
Other Income Taxes
Fiscal was known as "departure tax" or "prepayment of income tax," but it was actually considered an outdated tax system aimed at curbing residents' desire to travel abroad and preventing foreign currency outflow. Initially, it required "all residents departing overseas to pay 1 million rupiah," but it was changed to "exemption for NPWP holders, only 2.5 million rupiah for non-holders."
This was intended to increase tax awareness by uncovering those without NPWP and encouraging them to obtain NPWP, also positioned as "provisional payment of income tax," but was eventually abolished.
Regarding foreigner tax, to obtain IKTA (Ijin Kerja Tenaga Asing), US $1,200 must be transferred to the national designated bank as a skill development fund (DPKK = Dana Pengembangan Keahilan Keterampilan), and then the labor permit procedure is carried out with the payment proof.
(IKTA is the predecessor of the current IMTA (Izin Mempekerjakan Tenaga Asing).)
To obtain IKTA, one must first obtain KITAS (Kartu Ijin Tinggal Terbatas) residence permit. After obtaining this, one becomes an Indonesian resident and must receive a Kartu Imigrasi (immigration card) at the airline check-in counter when departing, submitting it to immigration upon departure.
At this time, the departure card is collected, but the half of the entry card must not be lost and must be returned at immigration upon return.
(The immigration card was abolished in March 2015.)
Previously, extending KITAS five times with the same company allowed upgrading to KITAP (Kartu Ijin Tinggal Tetap = permanent residence permit), but the current situation is unknown.
There are three ways for residents to depart from Indonesia, and if a KITAS holder departs with the intention of re-entering, a MERP (Multiple Exit/Re-entry Permit) or Single Re-entry Permit must be obtained in advance. If abandoning KITAS, an EPO (Exit Permit Only) must be obtained in advance.
(As of September 2015, only Multiple is available.)
After issuing EPO, one must leave Indonesia within two weeks. At this time, both entry and exit cards are taken, so care must be taken not to panic about "losing the card half" upon arriving in Singapore.
Upon re-entry, entry is made with VOA (Visa On Arrival), and it is recommended to prepare the necessary information on the entry/exit card and the ticket for the next departure (for Telex Visa for new KITAS) in advance. Otherwise, one may have to purchase and discard a departure ticket to Singapore just for immigration inspection.
Also, during the period from when Telex Visa approval is granted by immigration until the next departure, care must be taken not to lose the half of the departure card, as it will cause trouble upon departure. During this period, one should not forget their status as a traveler.
(Again, the immigration card was abolished in March 2015, so it is no longer necessary. It is included as a memory heritage of "such a system existed in the past.")
Foreign Currency Transactions and Tax Journal Entries
The Tax rate is officially determined by the tax office to prevent companies from manipulating the taxable amount of foreign currency transactions to be lower. The Tax rate is not used for Rupiah-denominated transactions. The principle is to record transaction journal entries in the transaction currency (Original currency).
For example, if the functional currency (Base Currency) is US$, and the repair fee A/P invoice is in Rupiah Rp.900,000, with a transaction rate of Rp9,500/$ and a Tax rate of Rp.10,000/$, it would be as follows.
- (Debit) Repair fee Rp. 900,000 (Credit) A/P Rp. 900,000(Base Rp.900,000÷9,500=$94.74)
- (Debit) Prepaid PPN input Rp. 90,000 (Credit) A/P Rp. 90,000(Base 90,000÷9,500=$ 9.47)
For Rupiah-denominated transactions, the amount payable to the tax office is determined in Rupiah. In accounting, the transaction rate used for conversion to the functional currency is the BI (Bank Indonesia) rate.
Next, if the repair fee A/P invoice is in dollars $90, the PPN journal entry is made in IDR. In this case, even if the transaction currency is dollars, the tax amount calculation records A/P in Rupiah.
- (Debit) Purchase $90 (Credit) A/P $90
- (Debit) Prepaid PPN input Rp.99,000 (Credit) A/P Rp.99,000($90x11%x10,000=99,000)
Due to accounting system constraints, if multiple rates (BI rate and Tax rate) cannot be referenced from the exchange rate master in the transaction screen, the conversion method to the functional currency is one of the following.
- Obtain the transaction part from the exchange rate master and correct the PPN part with manual calculation results
- Separate the transaction part and tax part into different screens for input
Both have high operational burdens, so when foreign currency transactions occur mid-month, it is possible to have both the transaction part and the tax part automatically calculated with the BI rate from the exchange rate master, aggregate the 11% PPN portion in a Temporary account, and offset (Re-class) with Rupiah-denominated PPN Payable calculated separately with the Tax rate at the end of the month.
- (Debit) Purchase $90 (Credit) A/P $99.9
- (Debit) PPN clearing $9.9
Aggregate the amount of Faktur Pajak on a monthly basis and offset it in bulk.
- (Debit) Prepaid PPN input Rp.90,000 (Credit) PPN clearing $9
Frequently Asked Questions | Indonesia's Tax System and Accounting Procedures
Based on the content of this article, frequently asked questions are briefly organized.
What is Indonesia's Value Added Tax PPN?
Indonesia's Value Added Tax PPN is equivalent to Japan's consumption tax. It adopts the invoice method, calculating PPN payments and refunds based on Faktur Pajak. Output PPN charged at the time of sale and Input PPN charged at the time of purchase are offset. If Output PPN is higher, it must be paid by the end of the following month. If Input PPN is higher, a refund claim can be made at the end of the fiscal year or carried over to the next business year.
What types of Income Tax PPh exist in Indonesia?
Indonesia's Income Tax PPh is divided into personal income tax and corporate income tax. Personal income tax is withheld from salaries under PPh21, and corporate income tax involves monthly payments of estimated tax amounts calculated from the previous year's income under PPh25 and settling the difference at the end of the year under PPh29. There are also withholding taxes on service income like PPh23 and PPh26.
How are tax journal entries for foreign currency transactions conducted in Indonesia?
The taxable amount for foreign currency transactions uses the Tax rate officially determined by the tax office. The Tax rate is not used for Rupiah-denominated transactions, and the principle is to record in the transaction currency. For accounting, the BI rate is used for conversion to the functional currency, and it is possible to automatically calculate with the BI rate mid-month and offset with Rupiah-denominated PPN Payable calculated separately with the Tax rate at the end of the month.