


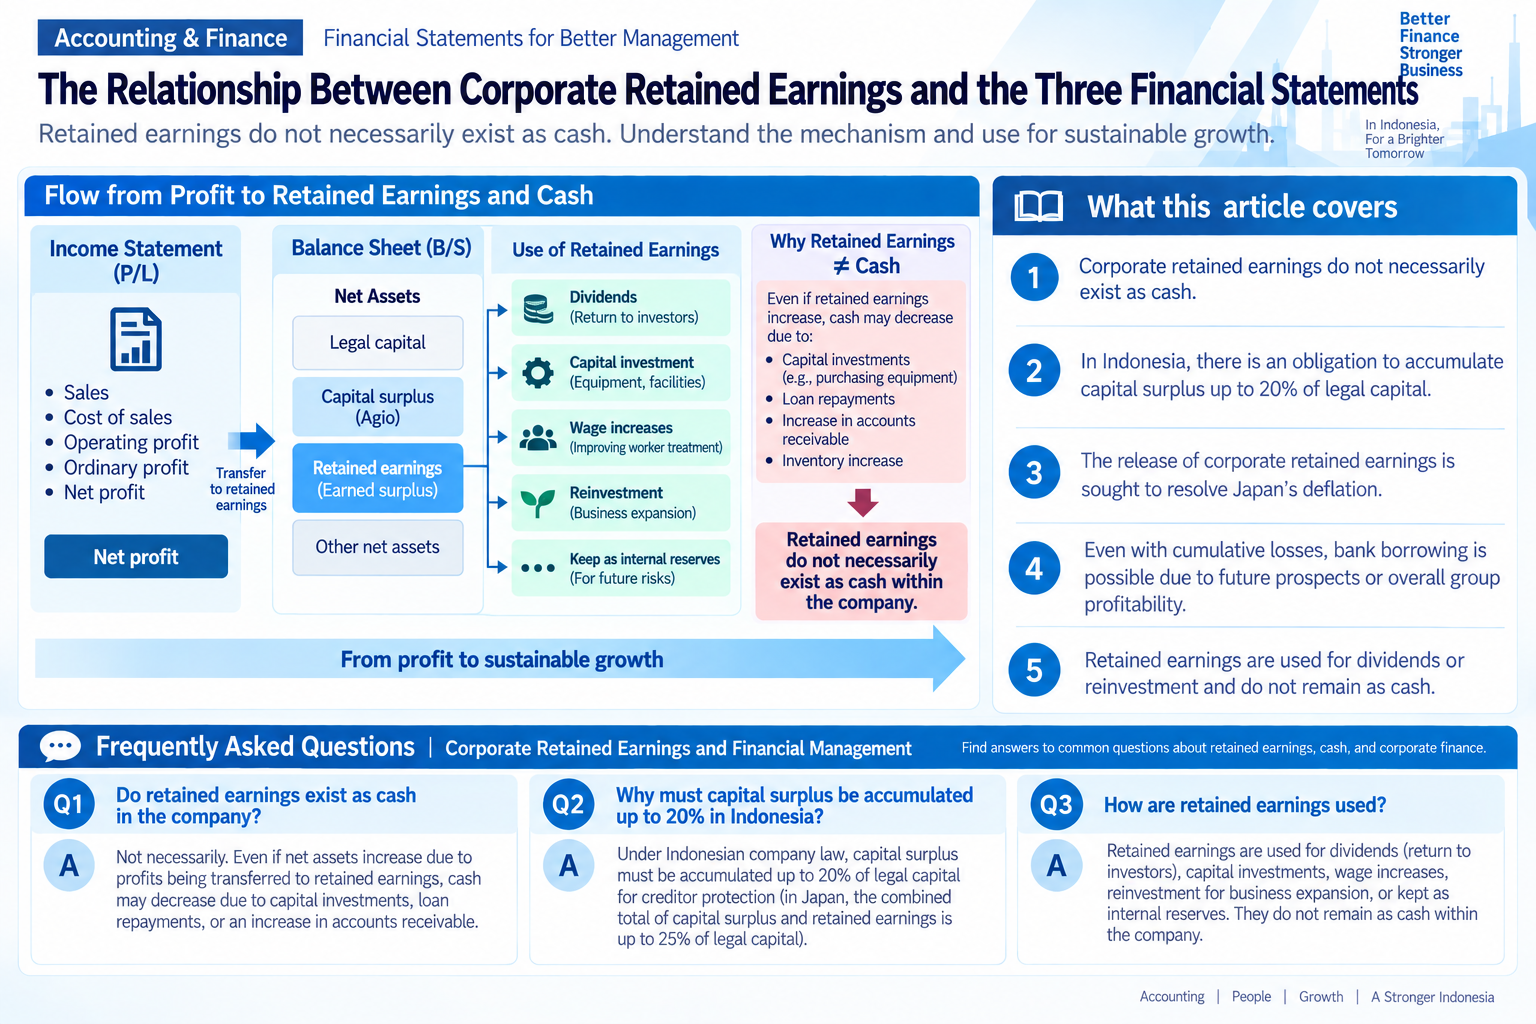
Corporate retained earnings do not necessarily exist as cash within the company. This is because even if net assets increase by transferring profits to retained earnings, the balance may decrease due to capital investments or loan repayments during the process of converting accounts receivable into cash.
-
-
Accounting Systems in Indonesia
The adoption rate of SaaS-based accounting systems in Indonesia is less than 8%, despite the advancement of SaaS technology. The continuous launch of new…
続きを見る
What this article covers
- Corporate retained earnings do not necessarily exist as cash.
- In Indonesia, there is an obligation to accumulate capital surplus up to 20% of legal capital.
- The release of corporate retained earnings is sought to resolve Japan's deflation.
- Even with cumulative losses, bank borrowing is possible due to future prospects or overall group profitability.
- Retained earnings are used for dividends or reinvestment and do not remain as cash.
Net Assets Section of the Balance Sheet (B/S)
Net assets are recorded in the net assets section of the balance sheet (B/S) in the form of legal capital, legal capital surplus, or retained earnings (earned surplus). Capital surplus and retained earnings are considered internal reserves.
Companies with growth potential aim to increase cash balances by carrying forward profits as retained earnings rather than returning them to shareholders through dividends, and by reinvesting in fixed assets such as equipment.
In Indonesia, company law requires that capital surplus be accumulated up to 20% of legal capital for creditor protection (in Japan, the combined total of capital surplus and retained earnings is up to 25% of legal capital). Japan is said to be in a deflationary recession, which is a state where companies hold excess internal reserves without money flowing into the market, resulting in stagnant wages and prices.
The Abe administration's Liberal Democratic Party government aims to overcome the deflationary mindset by setting an inflation target of 2% through the Bank of Japan, releasing internal reserves, raising prices, and increasing consumer purchasing power.
If liquid assets have accumulated within the company due to investment restraint and stagnant wages during the lost decade, it is possible to "release internal reserves" by raising wages. However, since the economy is poor, companies have endured by keeping wages stagnant. To improve the economy by raising wages, it cannot be done arbitrarily by management as a source for wage increases, and requires approval from investors at the shareholders' meeting.
There are three types of stakeholders related to corporations.
- Return to investors (dividends)
- Investment
- Improve worker treatment (wage increases)
- Do nothing (accumulate as internal reserves)
Since internal reserves do not necessarily exist as cash, whether "internal reserves can be released" depends on the company's financial situation. For example, a printing company that added a printing machine worth 5 million yen based on a deposit of 1 million yen may have internal reserves on the financial statements but zero cash.
- (Debit) Deposit 1,000,000 (Credit) Legal capital 2,000,000
- (Debit) Printing machine 10,000,000 (Credit) Capital surplus 7,000,000
- (Credit) Retained earnings 2,000,000
Additional purchase of a printing machine for 5 million yen
- (Debit) Printing machine 5,000,000 (Credit) Loan 4,000,000
- (Credit) Deposit 1,000,000
In accounting processing, when disposing of profits monthly, transfer journal entries occur, but when processing with an accounting system, there is no need to be particularly aware of this. At the time of annual closing, the system automatically transfers to the target net asset account (carried forward retained earnings) and creates journal entries for processing the accumulated internal reserves into dividends.
- (Debit) Net Profit 800,000 (Credit) Retained earning 800,000
In Indonesia, it is rare to dispose of current net income monthly, and if it occurs, it is usually done at the time of quarterly settlement. Until reaching the final retained earnings (carried forward retained earnings) on the B/S, temporary profit and loss accounts are used on a monthly and term basis.
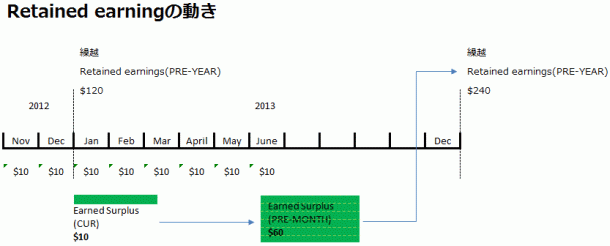
- RETAINED EARNING (CUR) Retained earnings (current month's net income) Temporary profit and loss account for transferring current month's net income (NET INCOME) to RETAINED EARNING (PRE-MONTH).
- RETAINED EARNING (PRE-MONTH) Retained earnings (cumulative net income from the beginning of the term to the previous month) Temporary profit and loss account for transferring the ending balance of this account to RETAINED EARNING (PRE-YEAR) at the beginning of the next year.
- RETAINED EARNING (PRE-YEAR) Carried forward retained earnings (cumulative net income from the founding year to the previous year) Generally referred to as retained earnings, it is the cumulative total from the founding year to the previous period, and the cumulative after-tax profit of past P/L.
Resolution of Cumulative Losses
If production results are not correctly input from the system or if month-end inventory is not accurately conducted, monthly inventory differences will fluctuate significantly. If the inventory difference is negative, manufacturing costs (sales cost in the case of product inventory differences) increase and result in a loss, while if the inventory difference is positive, manufacturing costs decrease and result in a profit. The system operates in a world of logic, and inventory differences are reflected in sales costs as inventory shrinkage costs (SGA), directly affecting the P/L.
By not recording monthly inventory difference losses as expenses but instead recording them as other assets, "hiding input errors" can temporarily improve the appearance of the B/S and P/L.
The following options are available for processing inventory differences.
- Reflect in sales cost by expensing monthly.
- Revalue fixed assets and transfer to revaluation gains.
- Record retained earnings as negative.
- Transfer to a temporary account (asset).
Ideally, when an inventory difference occurs, trace the receipt and payment results and correct the data, implementing option 1 to minimize the expense recording of inventory differences. In the case of a loss, it is appropriate to record retained earnings as negative in option 2, but if it is difficult in terms of labor, it is also possible to temporarily store the loss in option 3 and process it later in the system. Ultimately, some account transfer processing is necessary, and in that case, the B/S will be reconstructed through capital reduction.
Cumulative losses accumulate as negative retained earnings. Assets minus liabilities equals negative net assets, indicating insolvency, but reasons such as the following may allow for bank borrowing or stock price increases:
- The company's future prospects are very high.
- The entire group is profitable.
- The owner's personal assets are enormous.
- The latent gains on assets are significant.
Due to these factors, cumulative losses do not necessarily indicate danger.
The Meaning of Transferring Beginning and Ending Inventory During Closing Processing
In settlement adjustment journal entries, all expense and revenue accounts for the current month are transferred to profit and loss accounts. The expenses subject to this are period expenses incurred and expensed in the current month, and sales cost, which is the difference between beginning inventory and purchases for the current month minus ending inventory.
- Period expenses incurred and expensed in the current month
- Transfer the entire beginning inventory to an expense account called Opening stock, record the entire purchase as an expense account when purchased, and from a state of excessive expenses, transfer the remaining portion in ending inventory to assets to deduct from expenses, resulting in incurred expenses (sales cost).
- Replace inventory on the balance sheet (B/S), deduct ending inventory from purchases (Debit) Opening stock 800 (Credit) Inventories 800 (Debit) Inventories 1000 (Credit) Closing stock 1000
By setting the balances of the Opening stock account, Closing stock account, and purchase account to zero and eliminating them from the profit and loss statement (P/L), the difference is set as the balance of the sales cost account (cost of goods sold).
- Transfer beginning inventory, current month purchases, and ending inventory to COGS (Debit) COGS 800 (Credit) Opening stock 800 (Debit) Closing stock 1000 (Credit) COGS 1000 (Debit) COGS 400 (Credit) Purchases 400
Preparation for transferring expense accounts to profit and loss accounts is now complete.
Current Net Income Transferred to Retained Earnings Does Not Remain as Cash
The profit and loss on the P/L after month-end closing is also recorded as a profit and loss account (Net Profit) on the B/S and processed as dividends or retained earnings at the end of the fiscal year. In system accounting, journal entry data on the general ledger (G/L) is aggregated, pasted into prepared formats, and P/L and B/S are created. From a bookkeeping perspective, all expense and revenue accounts for the current month are transferred to profit and loss accounts.
- Transfer all expense items to profit and loss (Debit) Profit and loss (Net income) 80 (Credit) Total expenses 80
- Transfer all revenue items to profit and loss (Debit) Total revenue 100 (Credit) Profit and loss (Net income) 100
Companies with growth potential aim to reinvest in fixed assets such as equipment without returning dividends to shareholders, and conduct internal reserves more extensively.
- Transfer surplus balance (credit side) of profit and loss account to retained earnings (Debit) Profit and loss (Net income) 20 (Credit) Retained earnings 20
By carrying forward profits as retained earnings, net assets increase, but accounts receivable, which are the substance of revenue, are converted into cash, and the balance decreases due to capital investments or loan repayments. This is done independently of the movement of net assets.
- Capital investment (Debit) Machinery 5 (Credit) Cash 5
A few years ago, in response to the opinion that "corporate internal reserves should be released" to solve Japan's deflation, there was a counterargument that "internal reserves do not exist as cash within the company."
Methods of Profit Disposal
Net assets are listed on the B/S in the form of legal capital, capital surplus, and retained earnings (earned surplus). Among these, capital surplus and retained earnings correspond to internal reserves.
In Indonesia, company law requires that capital surplus be accumulated up to 20% of legal capital for creditor protection. Dividends to shareholders as profit disposal are recorded as liabilities in the form of unpaid dividends, sourced from retained earnings.
- Dividends from profit reserves (Debit) Retained earnings 10 (Credit) Unpaid dividends 10 (Debit) Unpaid dividends 10 (Credit) Cash 10
Frequently Asked Questions | Corporate Retained Earnings and the Three Financial Statements
Based on the content of this article, frequently asked questions are briefly organized.
Do internal reserves exist as cash?
Internal reserves do not necessarily exist as cash. Even if net assets increase as retained earnings, cash balances may decrease due to the conversion of accounts receivable into cash, capital investments, or loan repayments.
How do the regulations for capital surplus differ between Japan and Indonesia?
In Indonesia, capital surplus must be accumulated up to 20% of legal capital. In contrast, in Japan, the combined total of capital surplus and retained earnings is up to 25% of legal capital.
Why can companies with cumulative losses still obtain bank loans?
Even with cumulative losses, bank loans may be possible if the company's future prospects are high, the entire group is profitable, the owner's personal assets are enormous, or the latent gains on assets are significant.