
In mass production factories such as two-wheeler and four-wheeler parts manufacturers in Indonesia, comprehensive cost accounting is adopted to accumulate costs for each process. Material costs are allocated to work-in-progress and products according to input performance, while labor costs and manufacturing overheads are aggregated at the end of the month and allocated to items based on specific rules.
On the other hand, in factories with make-to-order production, individual cost accounting is adopted to aggregate costs by order number or project number, and labor costs and manufacturing overheads are recorded by multiplying actual work hours by predetermined wage rates and allocation rates.
In the Indonesian manufacturing industry, when the operating rate of production equipment declines, fixed costs drive up manufacturing costs, necessitating allocation rules based on actual data collected using IoT that reflect the actual situation.
However, no matter how precisely costs are understood, profits do not increase. For revenue improvement, it is necessary to analyze the variance between actual costs and standard costs and to establish a mechanism to review the purchasing prices of materials, equipment, and worker efficiency.
This blog is written for those who feel the need for systematization of cost management operations in the Indonesian manufacturing industry, providing articles on cost management systems to help envision a manufacturing system suited to Indonesia.
What this article covers
- Mass production factories in Indonesia adopt comprehensive cost accounting.
- Custom order production factories adopt individual cost accounting.
- Allocation rules are set using actual data from IoT.
- Variance analysis between actual cost and standard cost is important.
- Considering specific improvement measures is necessary for revenue enhancement.
Differences in Cost Calculation Methods Adopted by Production Management Systems
ERP package systems such as Microsoft Dynamics and Sage Accpac, which are commonly implemented in Indonesia, adopt actual cost calculation using the perpetual inventory method. In this method, cost calculation and accounting entries are performed each time inventory is received or issued, generating a series of real-time entries for material procurement, material input, manufacturing, shipping, and cost of sales. Therefore, there is no need for transfer entries of beginning and ending inventory balances to cost of sales in settlement adjustment entries after closing processes.
On the other hand, systems that adopt the periodic inventory method calculate manufacturing costs by subtracting the ending inventory amount from the sum of the beginning inventory amount and expenses incurred during the month. This method performs actual cost calculation based on the weighted average method through batch processing during accounting closing processes to calculate the manufacturing cost of products. Additionally, the standard cost for the next period is adjusted to reflect actual conditions, and standard cost calculation is executed based on the production plan and fixed cost budget to determine the manufacturing cost budget for the next period.
-

-
Cost Calculation Methods in ERP Systems in Indonesia
This article discusses cost calculation methods in ERP systems in Indonesia, focusing on the perpetual inventory and three-part methods. It highlights the…
続きを見る
Cumulative Method for Calculating Manufacturing Cost by Adding Subsequent Process Costs
The Cumulative Method (Rolling Costing) calculates the direct material cost input in the initial process using the weighted average method. It considers the manufacturing cost of work-in-progress, which includes processing costs, as the incurred cost of items input into the next process. The manufacturing cost of work-in-progress for the next process is similarly calculated using the weighted average method, and this is repeated for subsequent processes. This method is also known as rolling costing.
In this method, the incurred costs of each process are accumulated as input costs for the next process according to the account linkage diagram. In contrast, there is a Non-Cumulative Method that calculates the product manufacturing cost all at once by considering all processes as a single process. However, in actual cost accounting, the Cumulative Method is used.
To respond to market changes, production quantities are adjusted, but monthly fixed costs remain constant. Therefore, calculating manufacturing costs based on actual production quantities leads to shortsighted cost management. To avoid this, a leveled standard cost for the year is determined before creating the budget for the next term, and sales and procurement plans are established.
Cost variance indicates how much the manufacturing cost for each month deviates from this standard cost. Cost variance analysis breaks down the variance by factors such as purchase price, purchase quantity, and operating time.
Cost variance shows how much the manufacturing cost for the current month deviates from the standard cost, which is the benchmark. The inventory accumulated at the beginning of the month is not responsible for this cost variance, but at the time of shipment, both the inventory and the current month's production are evaluated at the weighted average, ultimately bearing joint responsibility as the cost of goods sold per unit.
The weighted average unit cost present when calculating manufacturing cost is the weighted average unit cost of work-in-progress. The weighted average unit cost of products is calculated based on "beginning inventory of products + current month's product manufacturing cost," and the cost of goods sold per unit, calculated after the manufacturing cost, corresponds to this.
-
-
Detailed Manufacturing Cost Calculation Using the Average and Cumulative Methods
This article details manufacturing cost calculation using the average and cumulative methods. It explains how costs are calculated and the implications of…
続きを見る
Costs Based on Production Results and Input Results in Cost Management Systems
In a cost management system, costs are calculated for each work-in-progress stage using the formula "total average unit cost of inputs x input quantity + processing cost of the current stage." The cost based on the production results of the previous stage becomes the cost based on the input quantity of the current stage, and the material cost becomes the cost based on the input quantity to the work-in-progress. The cost based on the production quantity of the work-in-progress becomes the cost based on the input quantity to the product.
- Cost based on input is direct material cost
⇒ Total average unit cost of materials x input quantity - Cost based on production is manufacturing cost
⇒ Total average unit cost of products x production quantity = Total average unit cost of inputs x input quantity that became products + processing cost that became products - Cost based on shipment is cost of goods sold
⇒ Total average unit cost of products x shipment quantity
The total material cost incurred for common materials can be calculated by subtracting the end-of-month material inventory amount from the sum of the beginning-of-month material inventory amount and the material purchase amount for the month using the three-part method. However, the incurred material cost for each item cannot be calculated using the three-part method unless it is known how many kilograms were used for each product. Therefore, it is calculated from the parent-child relationship of input results.
-
-
The Relationship Between WIP and Incurred Costs in Cost Accounting
The relationship between WIP and incurred costs in cost accounting involves understanding how materials and processing costs contribute to manufacturing…
続きを見る
Handling of Fixed Costs in Indonesia When Production Results Span Months and in Months Without Production
Materials are expensed not at the time of purchase but when they are put into production, and they remain as WIP inventory until production results are recorded. Once production results are recorded, they are converted into manufacturing costs, and at the time of shipment, they are converted into COGS.
If the actual input and production results span months, the costs incurred will remain in the WIP at the end of the current month, and if production results are not recorded by the end of the following month, the WIP will remain without incurring costs.
Manufacturing costs are based on the costs incurred in the current month according to production results, and if production is zero, manufacturing costs are also zero. Similarly, COGS are based on the costs incurred in the current month according to shipment results, and if sales are zero, COGS are also zero.
Even if there is no production, depreciation costs for machinery still occur. Ideally, the portion that became products in the current month should become manufacturing costs, but a contradiction arises when there are manufacturing costs in a month without production. For tax purposes, it is necessary to record depreciation costs monthly, so they are transferred to SGA or WIP.
-
-
Cost Management and Classification of Incurred Costs and Their Importance
Cost management involves classifying incurred costs into direct material costs, manufacturing costs, and cost of goods sold. Understanding these…
続きを見る
Variance Analysis of Actual Costing and Standard Costing
Actual cost and standard cost treat fixed costs similarly to variable costs using wage rates (allocation rates) and labor hours (efficiency) for variance analysis.
- Direct Material Cost (Material) = Unit Price x Quantity (KG per product)
- Direct Labor Cost (Labor) = Wage Rate (Amount per minute) x Efficiency (Labor hours per product)
- Manufacturing Overhead (Machine) = Allocation Rate (Amount per minute) x Operating Rate (Minutes per product) ← Allocation by working hours
- Manufacturing Overhead (Common Machine) = Allocation Rate (Amount per product) ← Allocation by production quantity
In variance analysis of actual cost and standard cost of products, the price variance of direct material cost is calculated as (Actual Material Unit Price - Standard Material Unit Price) x Actual Usage. The quantity variance is (Actual Usage - Standard Usage) x Standard Material Unit Price.
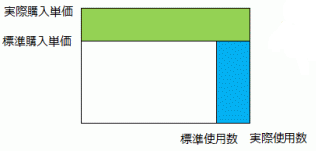
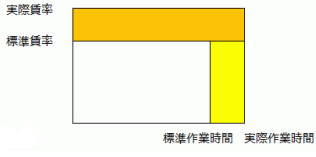
The wage rate variance of direct labor cost is calculated as (Actual Wage Rate - Standard Wage Rate) x Actual Labor Hours, and the actual wage rate is obtained by Actual Direct Labor Cost ÷ Actual Working Hours. The working hours variance is (Actual Labor Hours - Standard Labor Hours) x Standard Wage Rate.
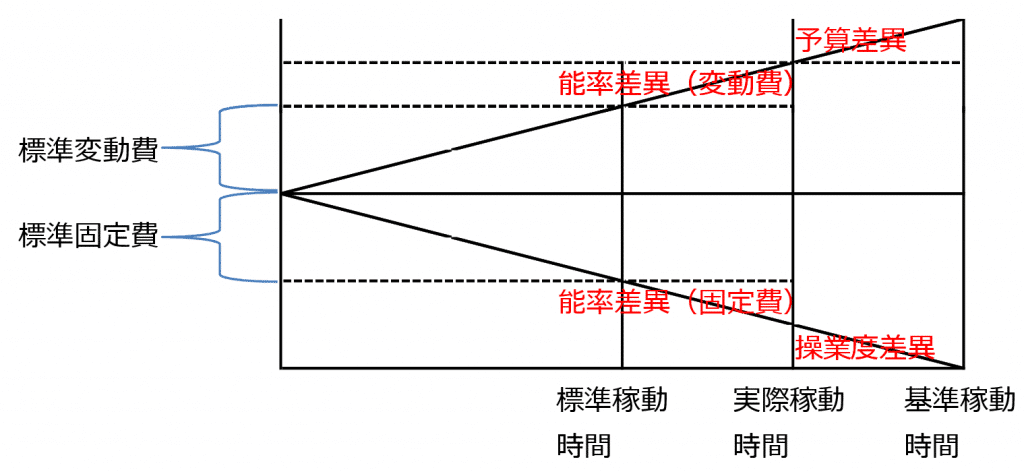
The variance of manufacturing overhead is considered on the Schlatter diagram based on standard operating hours, actual operating hours, and base operating hours as Allocation Rate x Operating Hours.
Allocation Rate x Standard Operating Hours = Standard Variable Cost and Standard Fixed Cost
Allocation Rate x Actual Operating Hours = Actual Variable Cost and Actual Fixed Cost
Allocation Rate x Base Operating Hours = Base Variable Cost and Base Fixed Cost
- Efficiency Variance (Variance on XY Graph)
Efficiency Variance (Variable Cost Part) = Actual Variable Cost - Standard Variable Cost
Efficiency Variance (Fixed Cost Part) = Actual Fixed Cost - Standard Fixed Cost - Budget Variance
Actual Variable Cost - Actual Variable Cost (Theoretical value based on actual operating hours), and the portion where actual manufacturing overhead exceeds actual manufacturing overhead (Allocation Rate x Actual Operating Hours) due to increases in material costs or wage rates (Variable Cost Allocation Rate).
- Operating Rate Variance (Variance on XY Graph)
Base Fixed Cost - Actual Fixed Cost, which is the loss due to the difference between base operating hours (full operation) and actual operating hours
How to Understand Standard Costing and Actual Costing as the Same System
The basic concept of allocation rate is to aggregate costs into units that do not bias the value of work time or production quantity, and then recalculate by dividing by the total work time to calculate the wage rate (how much per minute) or by the total production quantity to calculate the allocation rate (how much per item). In actual costing, the actual allocation rate is calculated as 'actual manufacturing overhead incurred ÷ actual production quantity', while in standard costing, the planned allocation rate (standard allocation rate) is calculated as 'manufacturing overhead budget ÷ planned production quantity'.
If the calculation basis for actual or planned allocation rates is work time allocation, then 'unit cost per item = allocation rate x labor hours', and if it is production quantity allocation, then 'unit cost per item = allocation rate'.
- Actual Cost Unit Price
- Direct Material Cost (Time Allocation): Average Unit Price
- Direct Labor Cost (Time Allocation): Actual wage rate calculated from actual incurred amount x direct labor hours
- Depreciation Cost (Time Allocation): Depreciation cost rate calculated from actual incurred amount x direct operating hours
- Manufacturing Overhead (Quantity Allocation): Allocation rate calculated from actual incurred amount
- Standard Cost Unit Price
- Direct Material Cost (Time Allocation): Standard Unit Price (from purchase price master)
- Direct Labor Cost (Time Allocation): Standard wage rate x standard labor hours (efficiency)
- Depreciation Cost (Time Allocation): Standard depreciation cost rate x standard operating hours (efficiency)
- Manufacturing Overhead (Quantity Allocation): Standard allocation rate
In standard costing, quantity expansion calculations are performed based on the planned production quantity of products, and the planned production quantity of work-in-progress and the planned purchase quantity of materials are calculated. This allows for the calculation of direct material cost per product and the calculation of planned direct labor hours through time expansion calculations. Additionally, a primary allocation ratio is calculated to allocate depreciation costs of shared equipment, etc., to cost centers.
-
-
Implementation of Cost Management System and Allocation Rate Calculation Method
The implementation of a cost management system allows for the calculation of direct material costs and manufacturing costs using a production management…
続きを見る
The Concept of Cost Management by Calculating Costs from Wage Rates (Allocation Rates) and Work Hours
In cost management, labor costs, which are fixed costs, are calculated using wage rates x efficiency (work hours), similar to material costs (unit price x quantity). Originally, this was intended for estimating subcontracting fees through work hour calculations (unit price x man-days).
Wage Rate Calculation for Cost Centers (Direct Departments)
- Aggregate the total direct work hours for each cost center by subtracting the indirect work hours (time not directly involved in manufacturing) from the work reports from the attendance data (clock-out time - clock-in time) of cost center workers.
- Calculate the direct work hours per product using the formula: [Direct work hours per product = Total direct work hours per cost center x {(standard work hours x production quantity) / SUM(standard work hours x production quantity)}]. It is crude to use only the production quantity of products with different work hours as the ratio to allocate the total direct work hours to products, so use standard work hours x production quantity.
Raising the Direct Work Hour Ratio is Fundamental to Factory Management
- Direct work is what produces results, and sales, general affairs, accounting, and managers are all support teams to enhance the productivity of direct work.
- Since "wage rate = total cost / operating hours," even with the same wage rate, if the direct work hour ratio is high, the results are significant, whereas if the indirect work hour ratio is high, the results are minimal.
- The wage rate is a time cost, and it is challenging to keep the wage rate down or increase processing output unless at least 70% of the sewing direct personnel is secured.
-
-
Management of Labor Hours and Wage Rates in Cost Accounting
This article discusses the management of labor hours and wage rates in cost accounting, focusing on their use in standard cost accounting for budget…
続きを見る
Difference Between Manufacturing Cost, Cost of Goods Sold, and Selling, General and Administrative Expenses
Manufacturing cost refers to the cost of products that have been stored in the product warehouse during the current month. Variable costs pertain to the portion of materials that were turned into products from the beginning inventory of materials and materials purchased during the month. Fixed costs pertain to the portion of direct labor costs and manufacturing overhead incurred during the month that were applied to the products.
Cost of goods sold is the cost of products shipped during the month from the beginning inventory of products and products stored in the product warehouse during the current month. Operating profit is calculated by subtracting the selling, general and administrative expenses (period costs) incurred up to the point of shipment from the gross profit, which is the sales minus the cost of goods sold.
- Beginning inventory of materials + Materials purchased during the month - Ending inventory of materials = Material cost for the month
- Beginning work-in-progress inventory + Material cost for the month + Processing cost for the month - Ending work-in-progress cost = Manufacturing cost
- Beginning inventory of products + Manufacturing cost - Ending inventory of products = Cost of goods sold
- Sales - Cost of goods sold = Gross profit
- Gross profit - Selling, general and administrative expenses = Operating profit
It is a very important point that the selling, general and administrative expenses, which are the costs incurred in selling the products, are outside of the cost of goods sold.
-

-
Key Points of Cost Calculation in Indonesian Accounting Operations
This article discusses key points in cost calculation for Indonesian accounting operations, focusing on manufacturing costs, COGS, and the timing of…
続きを見る
Explaining the Difference Between Cost and Expense with Egg Indomie
At the point of purchasing materials, it is merely a purchase expense. When cooking begins, it becomes an incurred expense, and the state during cooking is the WIP cost. Once cooking is completed, it becomes the manufacturing cost, and finally, when the customer pays, it becomes the COGS.
By understanding this flow, you can specifically grasp the difference between cost and expense.
For example, when making egg Indomie, it starts with the material expense, incurs WIP cost during the cooking process, and the finished product becomes the manufacturing cost.
When the customer purchases it, it changes to COGS.
Through this process, you can clearly understand the relationship between cost and expense.
-
-
Learning the Difference Between Expense and Cost with Egg Indomie
Learn the difference between expense and cost using egg Indomie. Understand incurred expenses, WIP, and how utility costs are determined.
続きを見る
How to Correct Errors in Performance Input in Production Management Systems
In the Indonesian manufacturing industry, it is common to perform cost calculations using Excel. The manufacturing cost for the month is calculated by subtracting the month-end inventory amount from the sum of the beginning inventory amount and the expenses incurred during the month. With this method, even if there are input errors in production performance or input performance, it is possible to handle them by making accounting adjustment entries.
However, when introducing a cost management system and calculating the manufacturing cost for the month from the total average unit price and actual quantities, it is necessary to correct the actual performance and recalculate the cost. This enables accurate cost management.
For specific correction methods, please refer to the following article.
-
-
Differences and Correction Methods between Total Average Method and Three-Part Method in Cost Calculation
This article explains the differences and correction methods between the total average method and the three-part method in cost calculation. It highlights…
続きを見る
Differences Between Job Order Costing for Make-to-Order and Process Costing for Make-to-Stock
In factories engaged in mass continuous production, such as those manufacturing two-wheeler and four-wheeler parts, make-to-stock production is carried out to maintain a certain level of inventory. Due to the high volume of orders, it is both personnel-wise and time-wise challenging to accumulate material costs, labor costs, and manufacturing overheads on a per order number basis as in make-to-order production. In continuous production, the same costs basically occur, so there is no point in calculating them individually for each order number.
In Indonesia, many factories engaged in make-to-order production struggle with cost management, and when requested to systematize production management tasks, they are often asked to aggregate costs incurred per order number rather than focusing on the flow of goods through inventory receipts and issues. This shows that in many cases, "production management = cost management."
-
-
Differences and Application Conditions of Job Order Costing and Process Costing
Job order costing aggregates costs per order, while process costing aggregates costs over a period. IFRS recognizes four inventory valuation methods.
続きを見る
Budget Cost in Cost Management System and Budget Management in Accounting System
A budget involves calculating the estimated sales and expenses for the next term in advance to predict profits. Key tasks in accounting include financial closing and budgeting, with financial closing conducted after a year's business activities and budgeting done before starting business activities.
The budget cost calculation function in the cost management system calculates the manufacturing cost budget against the sales budget on an item basis using standard material unit prices, wage rates, and efficiency through quantity and time expansion calculations.
On the other hand, budget management in the accounting system is conducted on a departmental and account basis. When budgets are set for P/L and B/S accounts, they are automatically aggregated to create the company's overall budget. This provides a budget versus actual management function to compare with the P/L and B/S figures after financial closing.
In Japan, the largest corporate expense is often labor costs, but in Indonesia, where labor costs are low, depreciation of machinery and material costs may constitute the majority of costs.
Project-based budgets use the project cost management function (Job Costing) to register estimated costs and manage budget versus actual costs through issuing purchase orders (P/O) for materials procurement and subcontractor services during the project term. Material costs, outsourcing costs, and other expenses incurred during the project are transferred to work-in-progress accounts or construction-in-progress accounts and managed as "non-revenue-generating assets."
-
-
Comparison and Practical Knowledge of Cost Management and Budget Management Systems
This article compares cost management and budget management systems, highlighting differences in standard and actual costs, and the impact of low labor…
続きを見る
Real Experience! Learning Marginal Profit and Break-even Point from Boutique Management in Bali
Manufacturing costs are classified into variable costs and fixed costs. Variable costs fluctuate in proportion to quantity and include direct material costs and subcontracting processing costs. These can be obtained from the transaction records of the production management system. On the other hand, fixed costs remain constant in amount and are obtained from the accounting system. These include costs allocated based on working hours according to allocation rules.
Manufacturing costs are also classified into direct costs and indirect costs. Direct material costs, direct labor costs, and manufacturing overheads fall into this category. Similar costs to manufacturing overheads also occur in selling and administrative expenses.
- Cost is the sum of variable costs and fixed costs, and unit price is expressed as the sum of variable unit price and fixed unit price. The variable unit price remains constant regardless of sales, but the fixed unit price decreases inversely with sales.
- To recover fixed costs with gross profit, it is necessary to consider the profit margin. For example, if a product purchased for 6 is sold for 10, the profit margin is 0.4. In this case, to recover fixed costs of 30, such as rent and labor costs, the break-even sales of 75 is calculated using the marginal profit rate of 0.4.
As such, understanding marginal profit and break-even point is a crucial element in management.
For detailed calculation methods and case studies, please refer to the following article.
-
-
Practical Understanding of Break-even Point and Marginal Profit Ratio
Understand the practical application of break-even points and marginal profit ratios in cost management. Learn how to calculate necessary sales to cover…
続きを見る
FAQ | Cost Management and Cost Calculation
We address common points of confusion in the Cost Hub, following the framework of the main text.
What is the difference between standard cost and actual cost?
The standard cost is evaluated using predetermined unit prices and quantities, while the actual cost is aggregated based on occurrences. The difference between the two is subject to variance analysis, and the key point in practice is to design them so they can be compared on the same system.
How are manufacturing cost, cost of goods sold, and selling, general and administrative expenses related?
Manufacturing cost refers to the cost incurred in the process of making products, cost of goods sold corresponds to the cost related to the sold portion, and selling, general and administrative expenses are the period costs for sales and management. The starting point in the framework of corporate accounting is not to confuse the positions of these three.
When do you differentiate between job order costing and process costing?
In make-to-order (MTO) production, job order costing on a project basis is fundamental, while in make-to-stock (MTS) production, process costing on a period or process basis is basic. It is chosen in conjunction with designs that accumulate process costs using methods like the cumulative method.