

Costs based on actual input are recorded as direct material costs, and costs based on production quantity are recognized as manufacturing costs. Costs based on shipments are recorded as cost of goods sold. If actual input and production results span months, the input for the current month remains as work-in-progress at the end of the month, and if production results are not achieved by the end of the following month, work-in-progress remains without incurred costs.
-
-
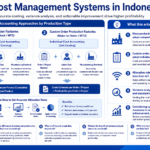
Cost Management Systems in Indonesia
Mass production factories in Indonesia adopt comprehensive cost accounting. Custom order production factories adopt individual cost accounting.
続きを見る
What this article covers
- Costs based on actual input are recorded as direct material costs.
- Costs based on production quantity are recognized as manufacturing costs.
- Costs based on shipments are recorded as cost of goods sold.
- If production results are carried over to the next month, costs remain as work-in-progress for the current month.
- In standard costing, there is no work-in-progress inventory at the end of the month, but in actual cost calculation, inventory is recorded.
The Importance of Cost Management
In corporate accounting, revenue (sales) and expenses (purchases) are recognized when transactions occur. Therefore, the profit obtained by subtracting expenses from revenue for a month does not match the cash balance. Even if the transaction terms with suppliers for materials and customers for products are end-of-month payments, the pressure of cash flow for material purchases at the end of the month varies depending on the company due to the following conditions:
- Cash balance sourced from sales or capital
- Depreciation costs that were factors in reducing profits
- Payments for manufacturing fixed costs other than material costs that occur throughout the month
- Payments for selling, general, and administrative expenses
- Salaries paid before receiving payments from customers
In sales management, even if sales increase due to discounts, if gross profit decreases, there will be a deficit in selling, general, and administrative expenses. However, sales prices need to consider market prices and cannot be easily increased. Therefore, cost reduction in the production management stage, where there is room for internal effort, becomes important. Overly detailed management of manufacturing costs only increases management burden, so the level of cost management is determined by "whether the results can be utilized in production management."
- Financial accounting aspect (from cost management to accounting) Convert actual production quantity on the shop floor to monetary terms (manufacturing cost report) and link to accounting (P/L).
- Management accounting aspect (from cost management to production management) Analyze productivity by comparing actual results with standard costs or budgeted costs.
Incurred Costs, Manufacturing Costs, and Cost of Goods Sold
Materials are not expensed at the time of purchase but when they are used. Until production results are achieved, they remain as work-in-progress inventory, and when production results are achieved, they become manufacturing costs, and upon shipment, they become cost of goods sold.
- Costs based on shipments Three-part method: Cost of goods sold = Beginning finished goods + Manufacturing costs - Ending finished goods balance Average method: Cost of goods sold = Average unit cost of products x Shipment quantity
- Costs based on production results Three-part method: Manufacturing costs = Beginning work-in-progress + Current month incurred costs - Ending work-in-progress balance Average method: Total average unit cost of inputs x Input quantity + Processing costs
- Costs based on actual input Three-part method: Material incurred costs = Beginning material balance + Current month purchase costs - Ending material balance Average method: Material incurred costs = Average unit cost of materials x Input quantity
When recording actual input and production results together, all incurred costs are aggregated to SKU item numbers. If beginning inventory is 0 and current month incurred costs are 100, the following holds:
- Beginning work-in-progress 0 + Current month incurred costs 100 - Ending work-in-progress 0 = Current month manufacturing costs 100
Difference Between Only Actual Input and Up to Production Results
If both actual input and production results are achieved by the end of the month, production results are recorded as a production quantity of 100. However, if production results span into the next month, the production quantity is 0, and work-in-progress is recorded as 100. This is the difference between whether the input of 100 remains as work-in-progress at the end of the month or is recorded as manufacturing costs.
If actual input and production results span months, incurred costs will always remain as work-in-progress at the end of the month. If production results are not achieved by the end of the following month, work-in-progress remains without incurred costs.
- Beginning work-in-progress 0 + Current month incurred 100 - Ending work-in-progress 100 = Current month manufacturing costs 0
When creating a manufacturing cost report by item, if there is an item number in work-in-progress inventory, costs can be aggregated by item. However, items without item numbers also need to be displayed as incurred costs on the cost report, and these are recorded as work-in-progress at the end of the month.
In standard costing, there is no work-in-progress inventory at the end of the month, but in actual cost calculation, the following two are recorded in the month-end balance of work-in-progress (also in the beginning balance):
- Month-end inventory: Items with item numbers in work-in-progress
- Month-end work-in-progress inventory: Items with only actual input recorded
Two Classification Methods of Manufacturing Costs
In Indonesian, "to move" is called mutasi, a loanword from the English mutation. This mutasi includes four types: Goods Receive, Goods Issue, Movement, and Transfer.
Manufacturing costs are classified into standard costs and actual costs, and manufacturing overhead is subdivided into indirect material costs, indirect labor costs, and expenses. Variable costs are direct material costs obtained from production input and output results, while fixed costs are expenses obtained from accounting, with two types: indirect costs and direct costs.
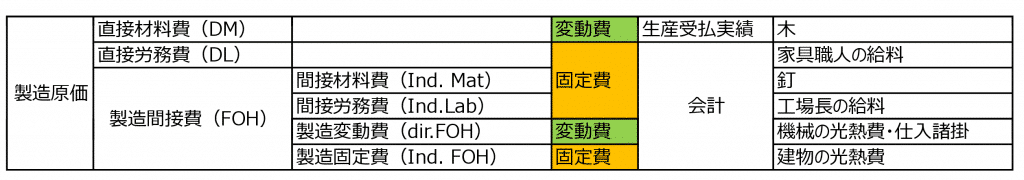
There are variable costs other than direct material costs, such as overtime and purchase charges, but most variable costs consist of direct material costs and outsourced processing costs.
Actual Allocation of Fixed Costs in Perpetual Method
The Perpetual Method, one of the inventory valuation methods, is a technique to always track inventory value movements in accounting asset accounts (materials, work-in-progress, products) when input and output occur. In systems where accounting and production management are integrated, direct material costs are maintained at FIFO (First-In-First-Out) unit prices or updated with moving average method, and direct labor costs and manufacturing expenses are allocated with standard allocation rates set in the Bill of Materials (BOM).
-
-
Knowledge of Variable Costs and Variance Analysis in Standard Costing
Standard costing treats direct material, labor, and overhead costs as variable costs. Variance analysis divides these costs into specific categories for…
続きを見る
However, even if direct materials are evaluated in real-time with FIFO or moving average method, when direct labor costs and manufacturing expenses are allocated to items based on actual incurred amounts, journal entries are generated in a batch process at the end of the month.
Journal entry for liabilities incurred at the time of material purchase.
- (Debit) Materials (Credit) Liabilities (AP)
Materials are input into work-in-progress, but manufacturing overhead is not allocated to work-in-progress.
- (Debit) Work-in-progress (Credit) Materials
The electricity bill for the current month arrives from the power company PLN (recorded as operating expenses at this stage).
- (Debit) Utilities (Credit) Liabilities (AP)
Transfer utilities to manufacturing overhead.
- (Debit) Manufacturing Overhead (Credit) Utilities
Allocate manufacturing overhead to products.
- (Debit) Products (Credit) Work-in-progress
- (Credit) Manufacturing Overhead
Additionally, the movement (mutasi) of materials in FIFO is recorded monthly under the assumption that there is no change in material purchase prices within the same month. To calculate the valuation of disbursement (material input) in the Perpetual Method, material costs are managed with two keys: material code and purchase month, such as "Cost of materials purchased in month X is Y yen."
Handling of Fixed Costs in Months Without Production
Even in months without production, depreciation costs of machinery occur in the factory. These costs are usually recorded as part of the current month's manufacturing costs.
- Beginning work-in-progress (Rp.0) + Current month manufacturing costs (Rp.100) - Ending work-in-progress (Rp.0) = Current month manufacturing costs (Rp.100)
In fixed asset management systems, there is a function to suspend the recording of depreciation costs in months without production, but for tax purposes, depreciation costs must be recorded monthly based on the straight-line or declining balance method. Therefore, it is common to transfer them to selling, general, and administrative expenses. This transfer needs to be done indirectly by specifying the incurred amount through an account transfer account.
It is also possible to transfer to work-in-progress (assets), but if the work-in-progress account is inflated despite no work-in-progress inventory in the warehouse, it may be pointed out by auditors.
- Why is work-in-progress recorded when there is no work-in-progress inventory?
In project accounting or construction accounting, it is common to record in work-in-progress accounts or construction in progress accounts and transfer to products at the end.
Frequently Asked Questions | Basics of Cost Management and Incurred Costs
Based on the content of this article, frequently asked questions are briefly organized.
What happens if actual input and production results span months?
If actual input and production results span months, the input for the current month remains as work-in-progress at the end of the month. If production results are not achieved by the end of the following month, work-in-progress remains without incurred costs.
What is the difference between manufacturing costs and cost of goods sold?
Manufacturing costs are costs based on production quantity and are recorded when products are produced. Cost of goods sold is costs based on shipments and are recorded when products are shipped.
What is the importance of cost management?
Cost management is important to ensure corporate profitability. Since revenue and expenses are recognized at the time of transaction, they do not match the cash balance. Cost reduction in the production management stage contributes to securing profits.