

By utilizing a production management system, it becomes possible to manage payment and receipt records based on an account linkage diagram. This allows the cost management system to calculate the total average unit price of direct materials. Furthermore, by using the cumulative method to accumulate processing costs for each process, it is possible to calculate the material costs incurred during the month, manufacturing costs, and cost of goods sold necessary for creating the P/L.
-
-
Cost Management Systems in Indonesia
Mass production factories in Indonesia adopt comprehensive cost accounting. Custom order production factories adopt individual cost accounting.
続きを見る
What this article covers
- Utilizing a production management system enables management of payment and receipt records based on an account linkage diagram.
- A cost management system can calculate the total average unit price of direct materials.
- Using the cumulative method, processing costs for each process are accumulated to calculate the manufacturing cost necessary for P/L creation.
- Manufacturing costs consist of variable costs and fixed costs, with variable costs calculated by the production management system.
- Allocation rates are calculated based on working hours or production quantity to determine the manufacturing cost unit price per item.
Purpose of Implementing a Cost Management System
In the financial accounting income statement (P/L), profits are calculated in the order of gross profit by subtracting the cost of goods sold from sales, operating profit by subtracting selling, general and administrative expenses (SGA), ordinary profit by subtracting non-operating expenses, and net profit for the period by subtracting extraordinary losses. The costs related to cost calculation are from the cost of goods sold inward.
To display gross profit, it is necessary to calculate the cost of goods sold, which requires calculating the manufacturing cost. To calculate the manufacturing cost, it is necessary to calculate the material costs incurred during the month.
- Gross Profit = Sales - Cost of Goods Sold
- Cost of Goods Sold = Beginning Finished Goods Inventory + Manufacturing Cost - Ending Finished Goods Inventory
- Manufacturing Cost = Beginning Work-in-Progress Inventory + Material Costs Incurred During the Month - Ending Work-in-Progress Inventory
- Material Costs Incurred During the Month = Beginning Material Inventory + Material Purchase Costs During the Month - Ending Material Inventory
To perform these calculations, it is necessary to calculate the valuation unit price for the quantities of materials, work-in-progress, and finished goods inventory at the end of the month. If calculations in Excel are difficult, it is recommended to consider implementing a cost management system.
Variable Costs and Fixed Costs
The cost of goods sold refers to the cost of products shipped from the product warehouse during the month. On the other hand, the manufacturing cost is the cost of products based on the production results of the month, which can also be said to be the cost of products received into the product warehouse. Material occurrence costs refer to the cost of materials shipped from the material warehouse during the month, which is synonymous with the cost of materials input into the production process.
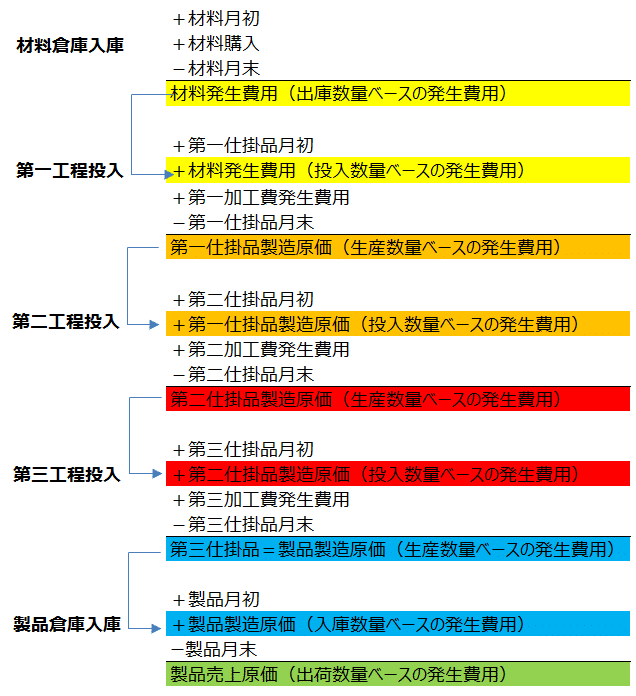
Materials with accumulated processing costs are collectively referred to as work-in-progress (first work-in-progress + second work-in-progress + third work-in-progress) as "larger than materials but less than products." The manufacturing cost of self-process work-in-progress is the cost of work-in-progress produced in the self-process during the month, which becomes the work-in-progress cost when input into the next process, and further processing costs are accumulated.
Manufacturing costs consist of variable costs and fixed costs (processing costs). The production management system can only calculate variable costs such as direct material costs and outsourced processing costs. Beginning inventory, purchase results, input results, and production results are necessary for calculating variable costs using the total average unit price, and processing costs (direct labor costs and manufacturing overhead costs) are obtained from the accounting system.
The Unit of Aggregation Changes from Account Titles to Items at the Boundary of Primary Allocation
An easy-to-understand example of primary allocation is the depreciation cost of shared machinery such as boilers and coolers. This is apportioned using the total operating hours of each line, which is a cost center, as the primary allocation ratio, and the allocation rate (cost per unit) is calculated by dividing by the production quantity for each line. In the case of manufacturing overhead costs, the total working hours of each product group, which is a cost center, are apportioned using the primary allocation ratio, and the wage rate (cost per minute) is calculated by dividing by the working hours for each product group and multiplying by the man-hours (efficiency).
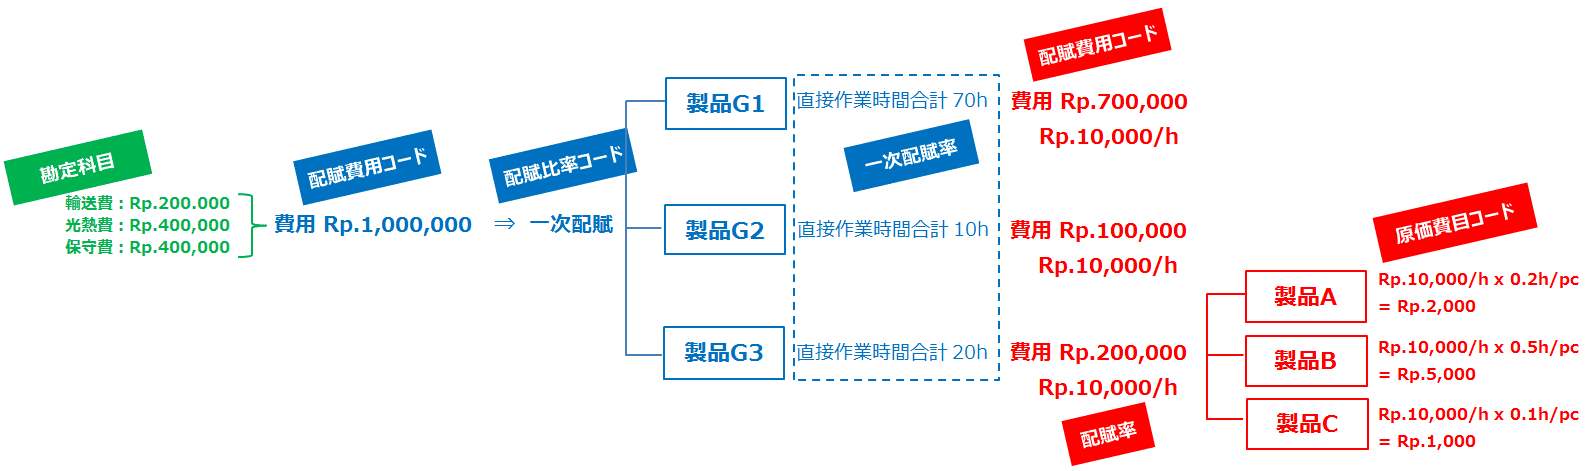
- Calculate the primary allocation ratio from quantity and time.
- The planned production number or actual production number obtained as a result of the requirement expansion based on the production plan is aggregated by product group or line and incorporated under the allocation ratio code, making it the quantity-based primary allocation ratio.
- The planned direct working hours obtained by multiplying the planned production number by the standard man-hours (efficiency), or the actual direct working hours, are aggregated by product group or line and incorporated under the allocation ratio code, making it the time-based primary allocation ratio.
- By apportioning the actual fixed costs or budgeted fixed costs using the primary allocation ratio, fixed costs are aggregated by product group or line.
- By dividing the fixed costs by the actual time or planned time for each product group or line, the allocation rate (cost per minute) for each cost item (direct labor costs, depreciation costs, expenses, etc.) is calculated. In the case of production quantity allocation, the allocation rate becomes the cost per unit for each cost item, so there is no need to multiply by man-hours.
- By multiplying the actual working hours or standard man-hours (efficiency) per item by the allocation rate, the actual unit price (standard unit price) per item for each cost item is calculated, and by cumulative calculation, the actual unit price (standard unit price) per item is calculated.
Differences in the Concept of Allocation Rate and Man-Hours between Standard Cost and Actual Cost
The basic concept of the allocation rate is to aggregate costs to a unit (process, line, product group) that groups items with no bias in the value of working hours or production quantity, and to recalculate the wage rate (cost per minute) by dividing by the total working hours or to recalculate the allocation rate (cost per unit) by dividing by the total production quantity. In the case of the wage rate, the manufacturing cost per item is calculated by multiplying by the man-hours (efficiency) per item. Based on the allocation rate, the processing cost per item can be calculated as follows.
- Direct Labor Costs (Time Allocation): Wage Rate (cost per minute) x Efficiency (minutes per unit)
- Depreciation Costs (Time Allocation): Allocation Rate (cost per minute) x Efficiency (minutes per unit)
- Manufacturing Overhead Costs (Quantity Allocation): Allocation Rate (cost per unit)
- SGA (Quantity Allocation): Allocation Rate (cost per unit)
In standard cost, the allocation rate is calculated in advance, and the standard unit price for each cost item is calculated by multiplying by the prepared standard man-hours. In contrast, in actual cost, the actual unit price for each cost item is calculated by dividing the amount aggregated to the primary allocation destination by the direct working hours. The allocation rate (cost per minute) and man-hours (minutes per unit) are determined retrospectively based on actual results.
Actual Allocation Rate and Planned Allocation Rate (Standard Allocation Rate) of Manufacturing Overhead Costs
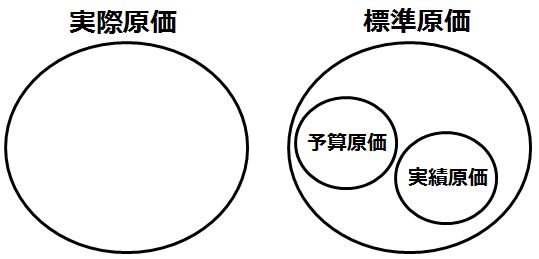
There are various types of cost calculations, but they can be broadly divided into actual cost and standard cost. Actual cost and budget cost can also be considered a type of standard cost.
Fixed costs are broadly divided into direct labor costs and manufacturing overhead costs. The calculation of direct labor cost begins with calculating the wage rate, and the calculation of manufacturing overhead cost begins with calculating the allocation rate. Direct labor costs are appropriately apportioned in proportion to time, such as "cost per hour." Since the standard man-hours differ for each item, it is not appropriate to apportion by production quantity.
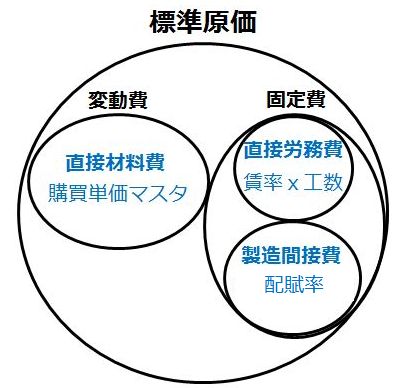
On the other hand, the depreciation cost of buildings, which is a manufacturing overhead cost, can only be apportioned by production quantity, such as "cost per unit." Thus, even for the same fixed cost, the basis for item allocation differs between direct labor costs and manufacturing overhead costs.
In the case of actual cost, the actual allocation rate is calculated based on the actual amount of manufacturing overhead costs incurred during the month and the actual production quantity. In the case of standard cost, the planned allocation rate (standard allocation rate) is calculated based on the manufacturing overhead cost budget and planned quantity. If the basis for calculating the actual allocation rate or planned allocation rate is time allocation, then "allocation rate x man-hours = cost per item," and if it is production quantity allocation, then "allocation rate = cost per item."
- Actual Cost Unit Price
- Direct Material Costs (Time Allocation): Total Average Unit Price
- Direct Labor Costs (Time Allocation): Actual Wage Rate Calculated from Actual Amount Incurred x Direct Man-Hours
- Depreciation Costs (Time Allocation): Depreciation Cost Wage Rate Calculated from Actual Amount Incurred x Direct Operating Time
- Manufacturing Overhead Costs (Quantity Allocation): Allocation Rate Calculated from Actual Amount Incurred
- Standard Cost Unit Price
- Direct Material Costs (Time Allocation): Standard Unit Price (from Purchase Unit Price Master)
- Direct Labor Costs (Time Allocation): Standard Wage Rate x Standard Man-Hours (Efficiency)
- Depreciation Costs (Time Allocation): Standard Depreciation Cost Wage Rate x Standard Operating Time (Efficiency)
- Manufacturing Overhead Costs (Quantity Allocation): Standard Allocation Rate
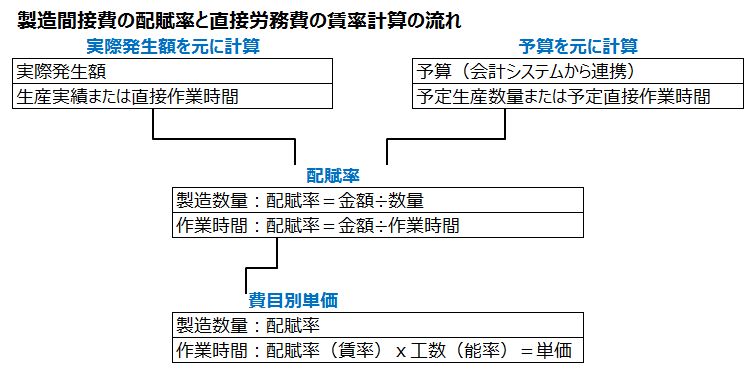
In the actual cost of the cost management system, fixed costs are calculated by apportioning the costs incurred after aggregating them in the cost center through primary allocation using working hours or production quantity. In the cost management system, the labor cost unit price allocated by working hours is "wage rate x man-hours," and the manufacturing overhead cost unit price allocated by production quantity is "allocation rate" itself. Standard cost can be calculated without waiting for the completion of actual input for the relevant month and is used to calculate the budget for the quarter or half-year.
Procedure for Standard Cost Calculation
In standard cost, the standard purchase unit price of direct materials is the purchase unit price managed in the production management master, and the planned allocation rate calculated from the actual allocation rate and production plan number of products calculated in the actual cost calculation of the previous month is set as the standard allocation rate for fixed costs.
- Expand calculation based on BOM from the planned production number of products
- Planned production number of work-in-progress
- Time expansion calculation based on planned production number and standard efficiency
- Planned direct working hours of products and work-in-progress
- Planned purchase number of purchased items
- Planned production number of work-in-progress
- Automatically calculate the primary allocation ratio based on the planned production number or planned direct working hours
- Perform primary allocation calculation based on the primary allocation ratio and aggregate fixed costs by cost center (product group or line)
- Set the calculation result of the allocation rate as the standard cost allocation rate
- Calculate standard cost based on the standard unit price of direct material costs and the standard cost allocation rate
Method for Calculating Allocation Rate
The wage rate (allocation rate) is a method of aggregating costs to a unit (process, line, product group) that groups items with no bias in the value of working hours or production quantity, and recalculating the wage rate (cost per minute) by dividing by the total working hours or recalculating the allocation rate (cost per unit) by dividing by the total production quantity.
- Allocation Rate Calculation
- Labor Cost Amount (Actual Amount Incurred or Budget) ÷ Working Hours = Wage Rate ⇒ Wage Rate x Efficiency (Man-Hours) = Labor Cost
- Manufacturing Overhead Cost Amount (Actual Amount Incurred or Budget) ÷ Quantity = Allocation Rate ⇒ Allocation Rate itself = Manufacturing Overhead Cost
In other words, if the cost per cost item per item is based on the budget, it is standard cost, and if it is based on the actual amount incurred, it is actual cost. Direct material costs are calculated based on the total average unit price in actual cost and the standard unit price in standard cost, but fixed costs (direct labor costs and manufacturing overhead costs) are aggregated to the cost center through primary allocation (inter-departmental allocation or inter-product group allocation) regardless of whether it is the actual amount incurred or the planned amount incurred, and allocated to item units based on working hours or production quantity.
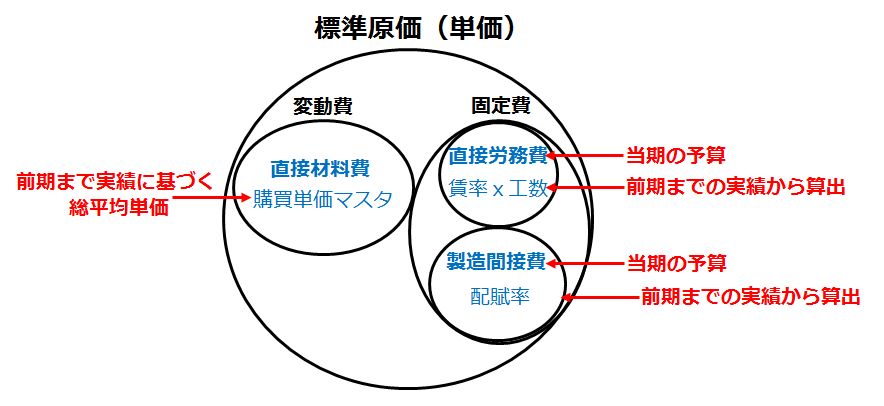
In standard cost calculation, the standard unit price of direct material costs is the unit price from the purchase unit price master, direct labor costs are calculated as wage rate x efficiency (man-hours), and the allocation rate of manufacturing overhead costs (quantity allocation) is the standard cost allocation rate. In this way, in standard cost calculation, the standard unit price of products is calculated by cumulative calculation of the standard fixed costs apportioned to items based on the budget for the current period, based on the wage rate and allocation rate calculated in advance based on the results up to the previous period.
Frequently Asked Questions | Standard and Actual with the Same System
This is a question about designing to see two calculations as one.
What are the advantages of using the same system?
By sharing the input route while only separating the evaluation axis, the explanation of differences can be standardized between the shop floor and accounting.
What are the common stumbling points?
Delays in updating the master (unit price, yield) and inconsistencies in the granularity of actual results.
What data should be aligned first?
The unit price and standard quantity of items, processes, and resources, as well as the timing of actual data collection.