


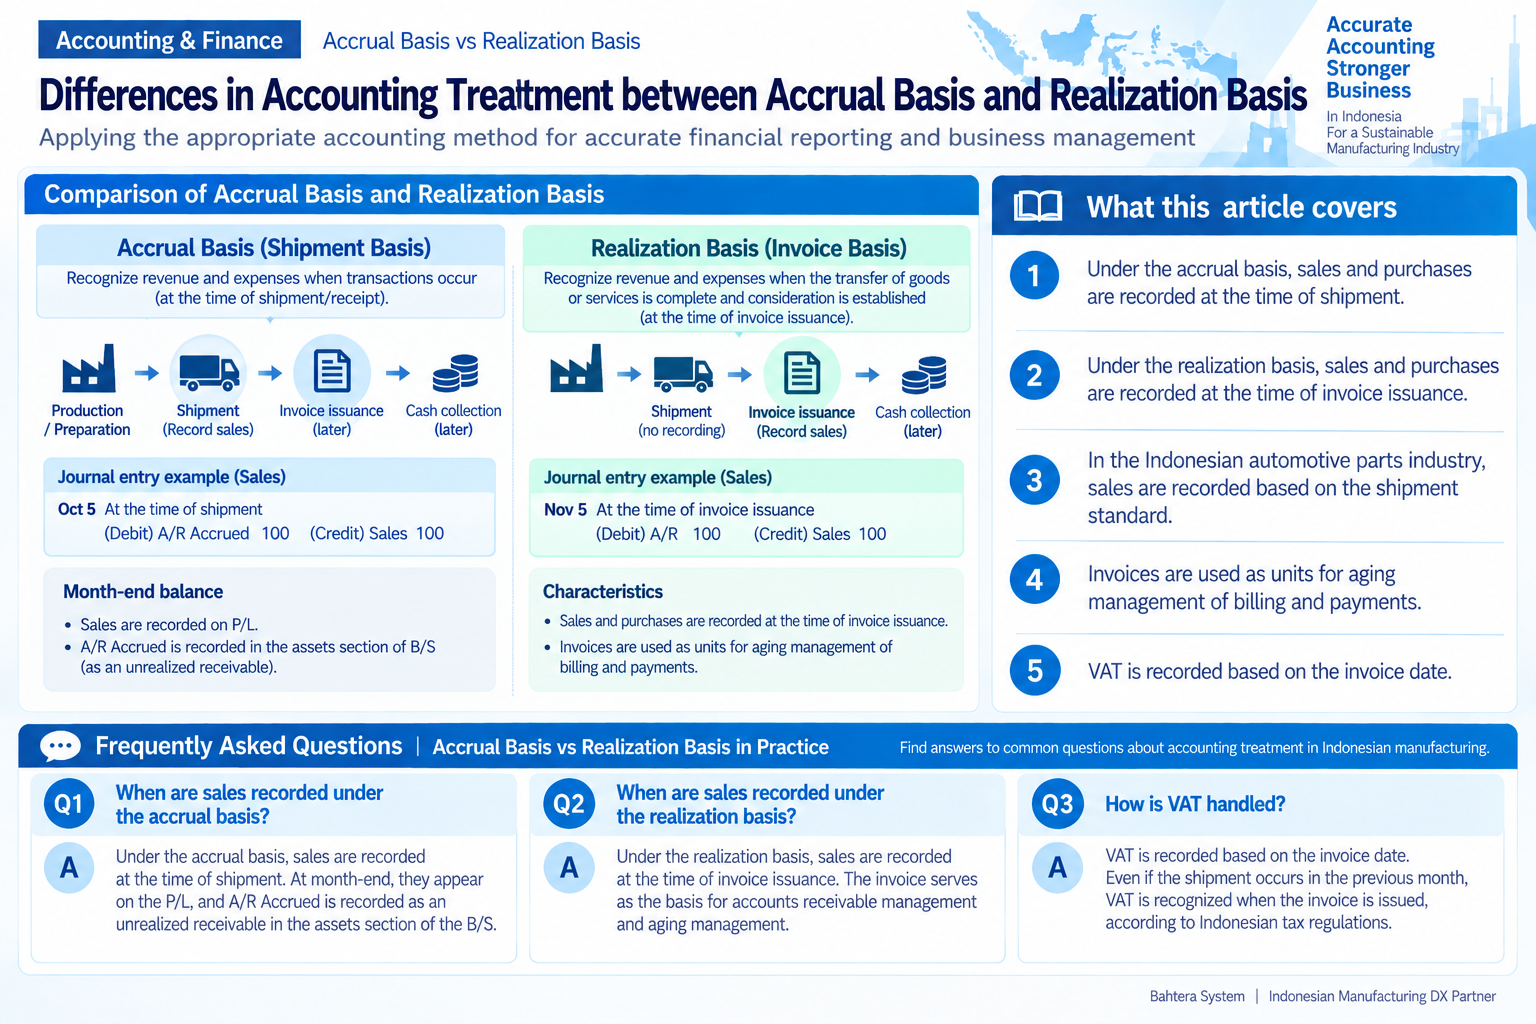
The accrual basis is a method of accounting where revenue and expenses are recorded when transactions occur. In contrast, the realization basis records them when the transfer of goods or services is complete and consideration is established. Specifically, under the accrual basis, sales and purchases are recognized at the time of shipment or receipt, while under the realization basis, they are recognized at the time of invoice issuance or arrival.
-
-
Accounting Systems in Indonesia
The adoption rate of SaaS-based accounting systems in Indonesia is less than 8%, despite the advancement of SaaS technology. The continuous launch of new…
続きを見る
What this article covers
- Under the accrual basis, sales and purchases are recorded at the time of shipment.
- Under the realization basis, sales and purchases are recorded at the time of invoice issuance.
- In the Indonesian automotive parts industry, sales are recorded based on the shipment standard.
- Invoices are used as units for aging management of billing and payments.
- VAT is recorded based on the invoice date.
Accounts Receivable and Sales Management on a Shipment Basis
In the Indonesian automotive parts industry, accounting treatment involves recording provisional receivables (A/R Accrued) and sales, purchases, and provisional payables (A/P Accrued) in the month the transaction occurs, and preparing the profit and loss statement (P/L) and balance sheet (B/S) for that month. Invoices are used as units for aging management of billing and payments, merely representing units of cash flow.
- October 5 shipment date records unrealized receivables and sales (Debit) A/R Accrued 100 (Credit) Sales 100
- October 10 shipment date records unrealized receivables and sales (Debit) A/R Accrued 100 (Credit) Sales 100
- October 20 shipment date records unrealized receivables and sales (Debit) A/R Accrued 100 (Credit) Sales 100
At the end of the month, sales are recorded on the P/L based on the accrual basis, and A/R Accrued, which is an unrealized receivable, is recorded in the assets section of the B/S. However, it is only recorded in the general ledger (G/L) of the accounting system and not yet recognized as a receivable (A/R). When the invoice is issued the following month, it is transferred to the A/R account in the accounting system's receivables management, clearing the G/L balance of A/R Accrued.
- November 5 transfer to receivables upon invoice issuance (Debit) A/R 300 (Credit) A/R Accrued 300
Accounts Payable and Purchase Management on a Receipt Basis
To ensure fairness, if receivables are recorded on a shipment basis, payables must also be recorded on a receipt basis. Accounts payable management on a receipt basis involves recording purchases and unrealized payables based on the accrual basis. Specifically, for goods received on October 5, 10, and 20, unrealized payables and purchases are recorded.
- October 5 receipt date records unrealized payables and purchases (Debit) Purchase 100 (Credit) A/P Accrued 100
- October 10 receipt date records unrealized payables and purchases (Debit) Purchase 100 (Credit) A/P Accrued 100
- October 20 receipt date records unrealized payables and purchases (Debit) Purchase 100 (Credit) A/P Accrued 100
At the end of the month, purchases are recorded on the P/L based on the accrual basis, and A/P Accrued, which is an unrealized payable, is recorded in the liabilities section of the B/S. However, it is only recorded in the G/L of the accounting system and not yet recognized as a payable (A/P). When the invoice arrives the following month, it is transferred to the A/P account in the accounting system's payables management, clearing the G/L balance of A/P Accrued.
- November 5 transfer to payables upon invoice arrival (Debit) A/P Accrued 300 (Credit) A/P 300
Integration Method from ERP System to Accounting System
Shipment and receipt processing are entered from the sales and purchasing management of the ERP system, but it is necessary to generate accounting journal entries based on the transaction date and interface data to the G/L or A/R A/P management. This ensures smooth integration with the accounting system.
Journal Entry Units at the Time of Receipt and Shipment
At the time of receipt or shipment, invoices have not yet arrived or been issued, and only the delivery order (D/O) is available. Therefore, to link to A/P or A/R upon invoice arrival or issuance, the D/O number is entered as a key item to search for receipt or shipment information.
Journal entries for recording unrealized receivables and payables (A/R Accrued, A/P Accrued) are generated at the time of receipt or shipment, but the unit of the journal entry changes depending on whether the accounting system includes item codes.
- For monthly summary invoices: "Supplier Code + Account Code" unit
- For invoices per shipment: "Supplier Code + D/O Number + Account Code" unit
- When the accounting system issues invoices: "Detail" unit
Journal Entry Units at the Time of Invoice Arrival (Issuance)
Typically, one invoice corresponds to multiple receipts or shipments. Only records with a status that has already been interfaced to the G/L as unrealized payables or receivables are displayed in a list, and checks are performed while matching them with the details of the arrived or issued invoice. The invoice number is then entered for the correct records.
Here, data is interfaced to receivables and payables (A/R A/P) management, and journal entries to clear the balance of unrealized payables or receivables on the G/L are generated. If the balance can be zeroed, the unit of interfaced data does not need to match the receipt or shipment.
The Chasm between Management, Sales and Purchasing Personnel, and Accounting Personnel
In the sales workflow of the Indonesian manufacturing industry, sales personnel register orders, logistics personnel issue shipment instructions, and delivery orders (D/O) are issued. Products and D/O are shipped together, and after shipment is complete, accounting personnel issue invoices and tax invoices (Faktur Pajak) and bill them together with the signed original D/O returned from the customer, resulting in A/R and sales registration.
In Indonesia, after the logistics department ships, there may be a delay of about a week before the accounting department issues invoices, especially when waiting for inspection completion reports from customers or when multiple D/Os are consolidated into one invoice. This makes it difficult to confirm whether accurate billing has been done for shipments.
This means that goods (shipments) and money (invoices) are not linked. Sales personnel may be aware of the shipment status of order data but may neglect to check whether invoices have been correctly issued and A/R recorded in the accounting department. Conversely, accounting personnel may find it difficult to see how the logistics department ships based on order information registered by the sales department and may not clearly understand which orders the original D/O collected by the accounting department is linked to.
When management requests project-based profit and loss calculation materials from accounting personnel, accounting personnel may ask sales personnel or logistics personnel to "specify the order number on the D/O." However, sales personnel often create estimates on a project lot basis, issue delivery instructions for multiple projects, or apply special discounts, making it difficult to clearly link D/O with orders when they span multiple projects.
Sales personnel often act on intuition, leading to rough document management. On the other hand, accounting personnel prioritize rationality and accuracy, leading to friction.
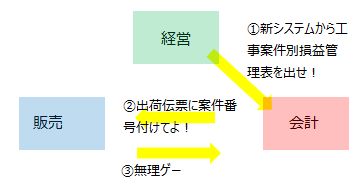
Management may question "why project-based profits cannot be calculated," while sales may resist, saying "sales work cannot be handled rigidly." The introduction of systems can lead to accumulated dissatisfaction among the three parties, worsening the internal atmosphere.
In small companies, the chasm can be resolved by sales personnel confirming that their recorded sales are correctly invoiced and settled by the accounting department. However, in large manufacturing companies with clearly defined roles in a vertical organization, system implementation vendors struggle to address these perception gaps.
Flow from Sales Registration on a Shipment Basis to Receivable Recognition
Sales are a profit and loss account, and A/R receivables are an asset account. In the ERP system, based on order registration, shipment instructions are issued, and sales registration is performed for completed shipments, generating the following journal entries on the accounting side.
- (Debit) A/R 10 (Credit) Sales 10
This assumes that sales are recorded on a shipment basis (accrual basis), and invoices are issued simultaneously with shipments, recording A/R. When shipments and invoice issuance occur simultaneously, the sales department can perform simultaneous sales registration, and the accounting side only needs to perform clearing at settlement, naturally resolving the chasm between sales and accounting.
Case: In the Indonesian automotive parts industry, invoices are often issued at the end of the month. However, the above journal entries are generated using the shipment date as the recording date at the time of shipment, and no accounting journal entries are generated at the time of invoice issuance, clearing using the shipment date (recording date) and item code as keys. Typically, invoice issuance is delayed by about a week from shipment, generating the following journal entries on the accounting side through shipment registration.
- (Debit) A/R accrued 10 (Credit) Sales 10
The recording date for A/R is the invoice issuance date or invoice arrival date, and at the time of shipment, the provisional receivable account A/R Accrued is used. A/R is recorded when the accounting department issues the invoice.
At the Time of Invoice Issuance
- (Debit) A/R 10 (Credit) A/R accrued 10
The bottleneck in system implementation in Indonesia is the A/R recording part, due to the timing mismatch between sales registration by the sales department based on shipments and A/R recording by the accounting department based on invoice issuance.
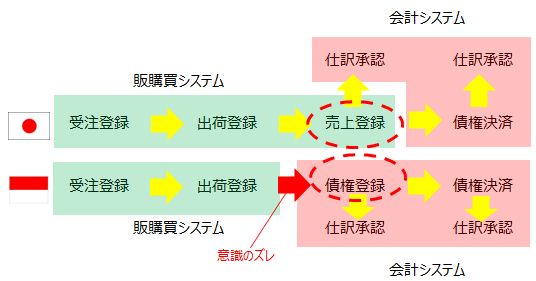
On the other hand, when only the accounting system is implemented, receivables are recorded based on invoices after managing orders and shipments outside the system using Excel, resulting in a smaller negative impact from system implementation but also a smaller positive impact.
The Meaning of Accrual Basis Accounting and Invoice Dates
Currently, VAT applications in Indonesia are conducted online through coretax, eliminating the need to develop Faktur Pajak form layouts in production management systems or accounting systems. However, it is necessary to consider how to link sales and purchase data to coretax. Before 2024, the import format for E-Faktur was CSV, but from 2025 onwards, it will change to XML in coretax.
In domestic transactions in Indonesia, the month of the Faktur Pajak date must be the same as the month of the invoice date. This is a rule to facilitate tax processing, meaning that the month for tax processing is based on the invoice date. When shipments or deliveries by domestic suppliers span months, even if the invoice date is the last day of the previous month, purchases may be recorded at the beginning of the current month based on the accrual principle.
Invoices are units of billing for money, and it is not necessary to record purchases or sales in accounting based on the invoice date. Invoices are merely documents that set deadlines for payment for consolidated billing units.
Discrepancies between Delivery Dates and Invoice Dates in Domestic Transactions
In domestic transactions, the period from shipment to delivery is short, so delivery dates and invoice dates may differ. The following two cases are common:
- Delivered on July 1, but due to the supplier's circumstances, the D/O (Delivery Order) date is set as June 31 to record it as sales for the previous month.
- The D/O was prepared on June 31, but delivery was delayed and arrived on July 1.
These are the same events for the company, differing only in the supplier's circumstances. Tax processing is based on the invoice date, and VAT journal entries are recorded in June.
- June 31 (Debit) VAT-in 33 (Credit) Payables 33
Purchases are recorded in July when they are shipped and delivered by the supplier based on the accrual principle.
- July 1 (Debit) Purchase 300 (Credit) Payables 300
Discrepancies between Invoice Dates and Deliveries in Imports
The greatest significance of recording goods in transit upon invoice arrival is recognizing and managing onboard inventory in accounting. If sales are recorded at the time of shipment based on the accrual principle, it may be fair to record purchases at the time of shipment by the supplier. However, in transactions like imports that take time to arrive, recording purchases in line with the supplier's shipment would be unfair, so purchases are recorded upon invoice arrival. VAT is also recorded upon invoice arrival.
- June 15 (Debit) Goods in Transit 300 (Credit) Payables 333 (Debit) Prepaid VAT-in 33
When goods arrive in Indonesia on July 15, goods in transit are transferred to the purchase account.
- July 15 (Debit) Purchase 300 (Credit) Goods in Transit 300
Timing of Sales and Receivable Recognition on an Accrual Basis
The accrual basis is one of the recognition criteria for profit and loss, where revenue or expenses are recorded at the time of economic events or changes, regardless of cash inflows or outflows. Typically, if payment is not made through cash or bank at the time of sales recording, it is recorded as accounts receivable (receivables).
- If payment is not made on the sales recording date, accounts receivable (receivables) are recorded.
- If payment is made on the sales recording date (Debit) Bank 100 (Credit) Sales 100
- If payment is not made on the sales recording date (Debit) A/R 100 (Credit) Sales 100
Sales based on the accrual principle are recognized upon "completion of delivery of goods" or "completion of service provision." If payment is not made on the sales recording date, accounts receivable (receivables) are recorded. An invoice is merely a unit of billing that confirms "the ability to bill and receive payment," so recording receivables upon invoice issuance is incorrect.
Positions of Sales and Accounting Departments on Sales and Receivable Recording Dates
From the sales department's perspective, if inventory movements and the timing of receivable and sales recording are synchronized, order backlog management, inventory management, and performance management can be unified on an accrual basis, making work easier. However, from the accounting department's perspective, synchronizing the movement of invoices with the timing of receivable and sales recording makes tax processing clearer.
Recording Sales and Receivables Simultaneously with Shipment
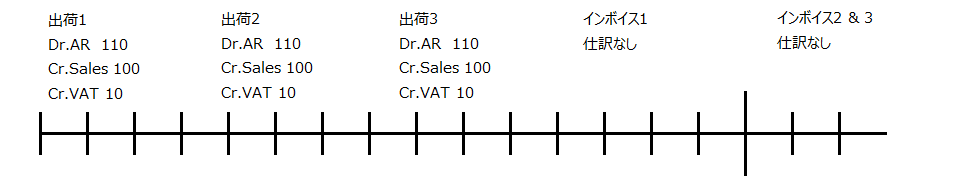
Based on simultaneous sales recording at the time of shipment, the sales recording date is considered the date when the right to receivables is confirmed, and receivable aging management is performed. Invoices are considered mere units of billing, and no accounting processing is performed at the time of monthly invoice issuance, following the principle of accrual-based shipment standards, a journal entry pattern more aligned with the sales department's perspective. Many Japanese automotive parts manufacturers in Indonesia adopt this accounting treatment.
- (Debit) A/R 111 (Credit) Sales 100
- (Credit) VAT payable 11
Invoice issuance
- No journal entry
Recording Sales Simultaneously with Shipment and Recording Receivables on a Document Basis
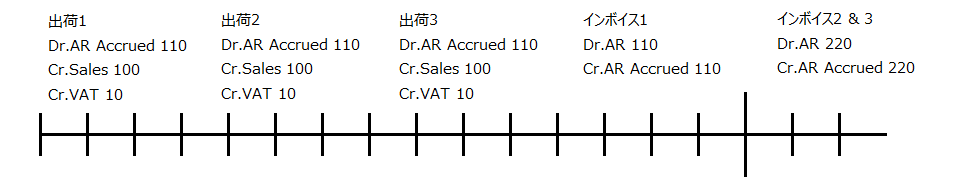
If the accounting department wants to record receivables at the timing of invoice issuance for administrative convenience, provisional receivables A/R Accrued are temporarily recorded at the time of shipment based on the accrual principle, and provisional receivables are offset with actual receivables A/R at the time of invoice issuance. This aligns the receivable recording date with the invoice issuance date for aging management.
- (Debit) A/R Accrued 111 (Credit) Sales 100
- (Credit) VAT payable 11
Invoice issuance
- (Debit) A/R 110 (Credit) A/R Accrued 110
From 2022, VAT (PPN) is 11%, and from January 2025, PPN will be 12%, but only some luxury goods will be subject to the full 12%. For regular transactions, multiplying 11/12 by the DPP (Dasar Pengenaan Pajak) calculates the taxable amount DPP nilai lain for applying the 12% PPN, resulting in an effective tax amount equivalent to 11%.
Recording Sales and Receivables in Line with VAT Based on Tax Invoice
According to international accounting standards, sales should be recorded on an accrual-based shipment basis, but in Indonesia, invoices are always accompanied by Faktur Pajak (Tax Invoice), which serves as the basis for VAT recording. When accounting for VAT based on Faktur Pajak, it is necessary to record sales in the same month as the invoice date, even if it deviates from the accrual principle.
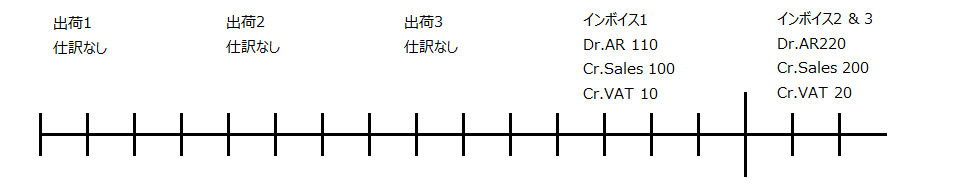
Recording sales and receivables based on invoices aligns the receivable recording date with the invoice issuance date, making receivables management easier for the accounting department. However, for the sales department, the actual results recognized as accounts receivable for shipments in the current month are carried over to the next month, complicating management and deviating from the accrual principle, making it inconsistent with international accounting standards for revenue recognition.
- No journal entry (inventory moves, but no accounting journal entry is generated)
Invoice issuance
- (Debit) A/R 111 (Credit) Sales 100
- (Credit) VAT 11
Recording Receivables at the Time of Shipment and Recording Sales in Line with VAT Based on Tax Invoice
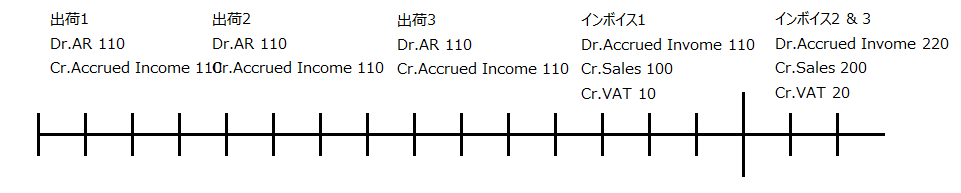
Receivables are recognized on the shipment date, and when recording sales in line with VAT based on Faktur Pajak, Accrued Income is used to clarify the target shipment results.
- (Debit) A/R 110 (Credit) Accrued Income 110
Invoice arrival
- (Debit) Accrued Income 111 (Credit) Sales 100
- (Credit) VAT 11
Reasons for Conducting Inventory Management on an Accrual Basis
If accurate current inventory cannot be grasped on an accrual basis, accurate ordering and shipping plans cannot be established. Inventory management must be conducted on an accrual basis to calculate the cost of goods sold in accounting.
Inventory management aligns with the actual flow of goods, accurately calculating the cost of goods sold on the P/L. Since the cost of goods sold (expenses) is recorded on an accrual basis, sales (revenue) must also be recorded on an accrual basis to prevent the gross profit from deviating from reality.
Case: The reason for setting the sales recording date to the B/L date (Bill of Lading) in FOB (Free On Board) export is that the B/L date becomes the delivery date of the goods under trade terms where costs and risks are borne until loading onto the ship, and thereafter, costs and risks are borne by the importer. In this case, inventory also decreases on the B/L date in inventory management.
Frequently Asked Questions | Differences between Accrual Basis and Realization Basis
Based on the content of this article, frequently asked questions are briefly organized.
What are the differences in accounting treatment between accrual basis and realization basis?
The accrual basis is a method of accounting where revenue and expenses are recorded when transactions occur. In contrast, the realization basis records them when the transfer of goods or services is complete and consideration is established. Specifically, under the accrual basis, sales and purchases are recognized at the time of shipment or receipt, while under the realization basis, they are recognized at the time of invoice issuance or arrival.
How is accrual basis accounting treatment conducted in the Indonesian automotive parts industry?
In the Indonesian automotive parts industry, provisional receivables (A/R Accrued) and sales, purchases, and provisional payables (A/P Accrued) are recorded in the month the transaction occurs. At the end of the month, sales are recorded on the profit and loss statement based on the accrual basis, and unrealized receivables are recorded in the assets section of the balance sheet. When invoices are issued the following month, they are transferred to the A/R account in receivables management.
How is accounting processing conducted upon invoice arrival?
Upon invoice arrival, goods in transit are transferred to the purchase account. For example, in import transactions, purchases are recorded upon invoice arrival, and VAT is also recorded upon invoice arrival. This allows onboard inventory to be recognized and managed in accounting.