

By dividing costs into variable and fixed costs, and using the marginal profit ratio, which is the ratio of purchase price (variable cost) to sales, the sales required to recover fixed costs is called break-even sales. In direct costing, only variable costs are considered as costs, and it calculates how many pieces of clothing need to be sold to achieve break-even sales.
-
-
Cost Management Systems in Indonesia
Mass production factories in Indonesia adopt comprehensive cost accounting. Custom order production factories adopt individual cost accounting.
続きを見る
What this article covers
- Break-even sales are calculated by dividing fixed costs by the marginal profit ratio.
- In managing a boutique in Bali, 35 juta in sales was needed to recover monthly fixed costs of 14 juta.
- The marginal profit ratio is set at 0.4, calculated as 60% of the selling price, to determine sales needed to cover fixed costs.
- Relocating to Sanur reduced fixed costs to 6 juta, lowering the break-even point to 15 juta.
- Transforming a cost center into a profit center can enhance departmental profitability.
Break-even Point: Neither Profit nor Loss
Eight years ago, I managed a boutique in Bali's Denpasar at Ramayana Mall and on Danau Tamblingan Street in Sanur. The strategy was based on the idea that "Jakarta's trends arrive in Bali with a three-month delay."
Every month, I purchased the latest trend models of Chinese imported clothing at a wholesale store in Jakarta's Mangga Dua, sent them to Bali via DAKOTA cargo, and displayed them in the store a week later. Freshness is crucial for women's clothing, especially trendy items for ABG (Anak Baru Gede).
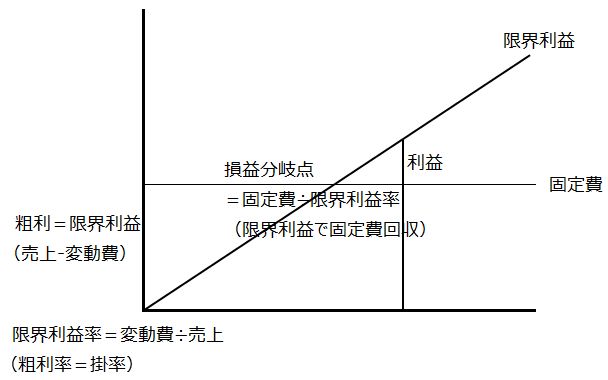
The break-even point indicates how many pieces (or how much) need to be sold to cover tenant fees and labor costs, resulting in a state of "neither loss nor profit."
- Sales - Variable Costs = Fixed Costs
- Marginal Profit = Fixed Costs
My wife handled purchasing and sales, while I was in charge of transportation and accounting, and the store operated with five SPGs (Sales Promotion Girls) in two shifts. The salary for an SPG was 800,000 Rupiah per person. As the accounting manager, I first considered
- Generating tenant rent of 7 juta and labor costs of 4 juta from OMSET (sales)
In reality, tenant rent was prepaid for a year, so there was no cash shortage at the end of the month, but it was considered as monthly fixed costs. With monthly sales of 11 juta, this was easily cleared.
Next, I considered
- Recovering tenant rent of 7 juta and labor costs of 4 juta with Profit from OMSET-MODAL (purchase cost in sales cost)
However, this became a bit challenging. The MODAL part is "MODAL against OMSET," so
- MODAL = Beginning Inventory + Purchases of the Month - Ending Inventory
This is precisely the variable cost (direct material cost in manufacturing). Clothes are sold at about 60% of the selling price, so the profit margin is 0.4. Therefore, ideally,
- 11 juta ÷ 0.4 = 27 juta
sales are needed to reach the "neither profit nor loss" break-even point, and the profit margin of 0.4 against the purchase price is called the marginal profit ratio.
With OMSET settling at around 22 juta, I felt somewhat relieved. Running a store in the warm Bali climate, it was easy to forget the initial investment (first-year tenant rent) and focus on clearing monthly payments and making a small profit. However, as the time for tenant rent renewal approached, reality became more apparent, and anxiety set in.
Sales Sufficient to Recover Fixed Costs
The concept of the break-even point refers to the "number of clothing pieces or sales amount sufficient to recover monthly tenant rent and labor costs," aiming to record at least non-loss sales. For retailers, it makes sense to recover fixed costs incurred at the end of the month with the profit (sales - variable costs = marginal profit) from sold products.
- Fixed Costs ÷ Marginal Profit Ratio = Break-even Sales
This is called CVP (Cost Volume Profit) analysis, which calculates sales at the "neither profit nor loss" point. If you lack confidence in the above calculations, please let us know.
It is important to visit the shop floor, overcoming inconveniences such as heat, traffic jams, back pain, and rear-end collisions, to understand the actual situation.
Increasing Productivity and Operating Profit by Raising the Direct Work Time Ratio
We continued to manage the boutique in Bali's shopping mall for about two years. With an annual tenant rent of around 100 juta and a team of six SPGs (Sales Promotion Girls) (80,000 Rupiah per person/month), the fixed costs amounted to 14 juta/month when divided monthly, but we managed to recover the initial investment to some extent.
- Total Cost = Total Variable Cost + Total Fixed Cost
- Unit Price = Variable Unit Price + Fixed Unit Price
While the variable unit price (purchase price of clothing) remains constant regardless of sales, the fixed unit price (tenant rent + SPG salary) decreases inversely with sales. When purchasing at 6 (variable cost) and selling at 10, the marginal profit ratio of 60% of the selling price (60% of the suggested retail price) is 0.4, and we consider how much sales are needed to recover fixed costs of 14 juta/month.
- 14 juta ÷ 0.4 = 35 juta/month in sales
After the impact of bombings centered in Jakarta, tourism to Bali declined, and the fixed costs (SGA) became a burden. After much consideration, we moved to Danau Tamblingan Street in Sanur, opposite Hardy's. As a result, we reduced the number of SPGs to two, lowered the tenant rent to about 50 juta/year, and reduced fixed costs to 6 juta/month.
- 6 juta ÷ 0.4 = 15 juta/month in sales
However, Sanur at that time was truly deserted, and despite the significant reduction in the break-even point after the move, we struggled to break even. The strategy we devised was to increase the profit margin by adding value to turquoise, amethyst, tiger's eye, and other natural stones, which were available at low cost, by connecting them with silver beads and selling them.
Case: By melting unsold silver inventory intended for Japan that was staying at home, reprocessing it into beads, and stringing them with fishing line to create necklaces and bracelets for display, Western women engaged in bulk buying, allowing us to achieve a decent profit. The crucial point here is that by having idle SPGs engage in accessory production as a side job, the salary, which was previously accounted for as SGA due to 100% of working hours being promotional work, was converted into direct labor costs as production work.
- Reduced purchase costs and increased marginal profit by in-house processing
- Converted SGA into direct labor costs for in-house processing, saving outsourcing processing costs, and increased both gross and operating profit
This means "converting indirect work time into direct work time, thereby transforming fixed costs into variable costs (purchase costs)."
- Marginal Profit (Gross Profit) = Sales - Variable Costs
By having SPGs, who have lower wage rates compared to outsourced processing costs included in the purchase price, perform production, variable costs decrease.
- Operating Profit = Marginal Profit - Fixed Costs
This means that even with the same working hours and the same cost (salary), by increasing the direct work time ratio, output increased, and operating profit was raised.
Managers Want to See Operating Profit by Department and Product
Having been self-employed in Bali for about seven years, the indicators I paid attention to daily were sales, sales cost, and SGA, with a focus on how much operating profit products or services generated. As a manager, there is always a desire to see operating profit by department or product group, taking into account SGA. Unless there is a calculation error in manufacturing costs leading to a cost overrun, gross profit is not a direct management indicator.
Returning to Jakarta and becoming a system implementation site manager, I tended to think of business systems in terms of functionality, viewing the flow of operations from procurement and production to inventory and accounting. However, Japanese company managers need to trace inventory and procurement from sales performance and require departments and product groups.
The classification of items in the business system's master data can be divided based on the convenience of inventory management from the perspective of department management personnel or based on the connection to sales from the perspective of sales personnel or managers. The department master is based on the company's organizational chart, but if you want to manage profit and loss at the section level, you need to define departments in more detail. A common department is also necessary, and a system department that serves as a cost center is defined flatly, with the upper-level general department defined as the output unit for reports.
From Cost Center to Profit Center
When accumulating costs by work center, the cost center usually functions as a department. In this case, only costs are aggregated, and revenue is not, so there is a tendency to avoid work or tasks with high profitability but high costs.
Therefore, by transforming the cost center into a profit center and making it responsible for both revenue and costs (profit and loss), we aim to optimize departments to maximize profit. However, partial optimization does not necessarily lead to overall optimization.
Frequently Asked Questions | Break-even Point and Marginal Profit Ratio
In line with the content of this article, we summarize frequently asked questions briefly.
What is the break-even point?
The break-even point refers to the point where sales reach an amount sufficient to recover fixed costs. At this point, there is neither profit nor loss. Once the break-even point is exceeded, profit is generated.
What is the marginal profit ratio?
The marginal profit ratio is an indicator that shows the ratio of variable costs to sales. Specifically, the amount obtained by subtracting variable costs from sales is the marginal profit, and dividing this by sales gives the marginal profit ratio.
How do you calculate the sales needed to recover fixed costs?
The sales needed to recover fixed costs can be calculated by dividing fixed costs by the marginal profit ratio. For example, if fixed costs are 14 juta and the marginal profit ratio is 0.4, the required sales would be 35 juta.