


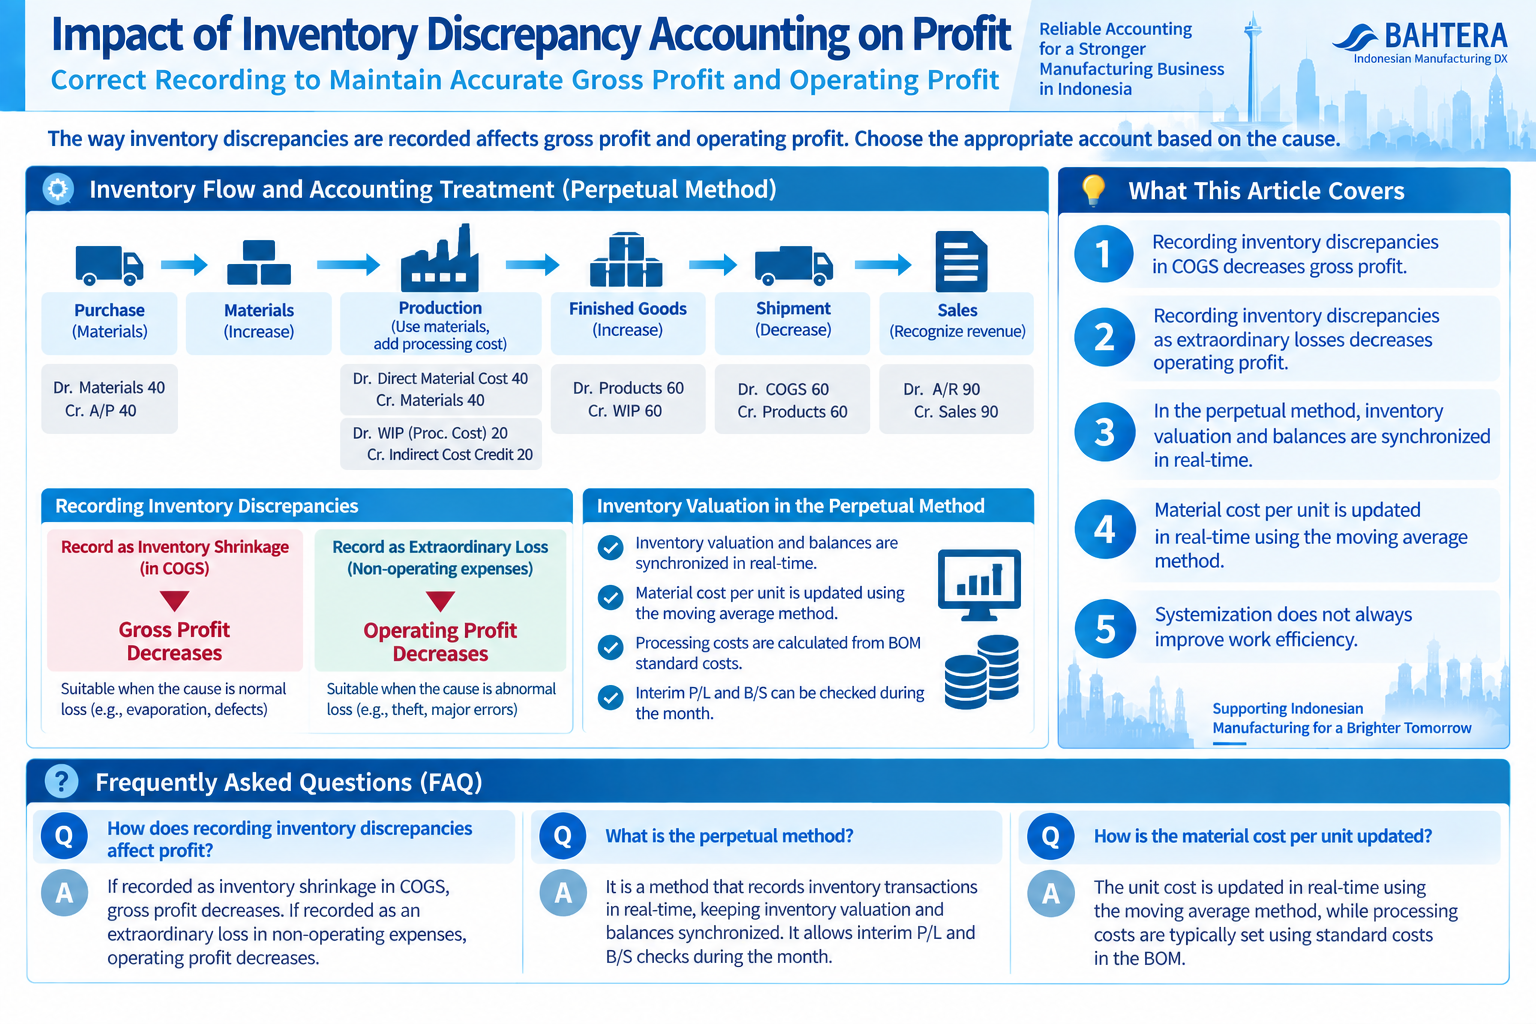
The way end-of-month inventory discrepancies are recorded affects gross profit and operating profit. If recorded as inventory shrinkage in COGS, gross profit decreases. If recorded as an extraordinary loss in non-operating expenses, operating profit decreases.
-
-
Accounting Systems in Indonesia
The adoption rate of SaaS-based accounting systems in Indonesia is less than 8%, despite the advancement of SaaS technology. The continuous launch of new…
続きを見る
What this article covers
- Recording inventory discrepancies in COGS decreases gross profit.
- Recording inventory discrepancies as extraordinary losses decreases operating profit.
- In the perpetual method, inventory valuation and balances are synchronized in real-time.
- Material cost per unit is updated in real-time using the moving average method.
- Systemization does not always improve work efficiency.
Difference Between Physical Inventory and Theoretical Value
In a perpetual method system that generates accounting journal entries for inventory transactions, inventory asset accounts are increased when materials or components are purchased and when WIP or finished goods are recorded, and decreased when materials or WIP are used or products are shipped.
- (Debit) Materials 40 (Credit) A/P 40
In this system, inventory valuation and accounting inventory balances are synchronized in real-time, allowing interim P/L and B/S checks during the month. Material cost per unit is updated in real-time using the moving average method, while standard costs for other processing costs are typically set in the BOM.
When materials are issued, material costs are recorded as a negative expense in a contra account (R/M Cost Credit account), allowing the breakdown of manufacturing costs to be shown on the P/L without offsetting the direct material cost account balance.
- (Debit) Direct Material Cost 40 (Credit) Materials 40
- (Debit) WIP (Direct Material Cost Portion) 40 (Credit) R/M Cost Credit 40
When recording product output, processing costs are calculated from the BOM's standard cost and recorded as a negative expense in a contra account (Indirect Cost Credit account), allowing the breakdown of processing costs to be shown on the P/L.
- (Debit) WIP (Processing Cost Portion) 20 (Credit) Indirect Cost Credit 20
- (Debit) Products 60 (Credit) WIP (Direct Material Cost Portion + Processing Cost Portion) 60
Ultimately, products are shipped and become COGS.
- (Debit) COGS 60 (Credit) Products 60
- (Debit) A/R 90 (Credit) Sales 90
Since processing costs are included in COGS, discrepancies are adjusted when actual processing costs are confirmed.
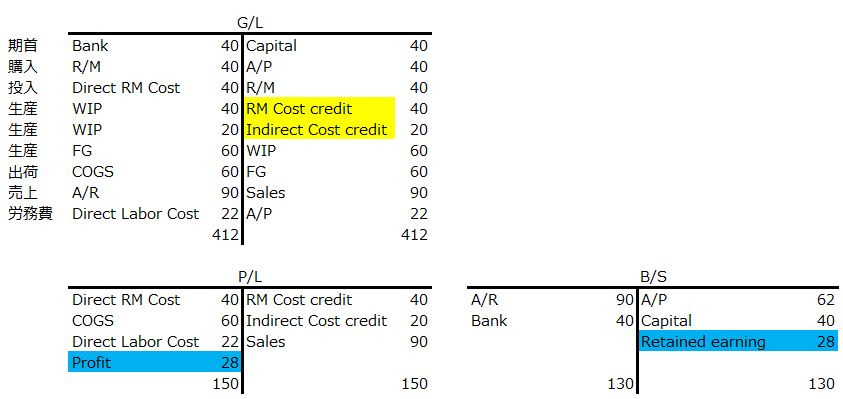
The method of recording the difference between WIP output and material input as processing costs is called planned allocation of actual cost accounting for fast accounting. However, incorrect actual input can distort not only inventory quantities but also accounting figures.
Case: Errors are often discovered during physical inventory counts. Corrective actions involve retroactively adjusting production records after month-end inventory counts. However, incorrectly recorded production lots may have already been consumed in subsequent processes, and for products with short lead times, they may have already been shipped and invoiced. Canceling downstream invoices and shipment records is often necessary, but typically, canceling shipments or invoices results in new invoice or shipment numbers, affecting customer and supplier document management.
Accounting Impact of Adjusting Inventory Discrepancies
Adjusting inventory discrepancies in inventory management triggers automatic journal entries in the accounting system. If physical inventory is less than theoretical values, a decision must be made whether to expense or capitalize the discrepancy. If due to input omission, it should be included in manufacturing costs as scrap costs, reducing gross profit.
- COGS = Beginning Inventory + (Current Month Manufacturing Costs + Discrepancy) - Ending Inventory
- Gross Profit = Sales - COGS
When included in COGS as inventory shrinkage in month-end adjustment entries
- COGS = Beginning Inventory + Current Month Manufacturing Costs - (Ending Inventory - Discrepancy)
- Gross Profit = Sales - COGS
When recorded as an extraordinary loss in non-operating expenses
- COGS = Beginning Inventory + Current Month Manufacturing Costs - Ending Inventory
- Gross Profit = Sales - COGS
- Operating Profit = Gross Profit - Discrepancy
Regardless of where it is recorded, costs are recorded, compressing profit. The key is the fact that "despite underreported actual input, deliveries are made without issue." It is essential to investigate the causes of discrepancies, such as unrecorded production or defective products, and improve actual input from the following month.
Systemization Is Not Always Correct
When implementing business systems in Indonesian factories, it is considered most practical to manage only quantities in production management, perform inventory adjustments in the system, and calculate inventory valuation at month-end using batch processing, determining manufacturing and COGS using the three-way method. In this case, data interfaces are needed between production management, cost management, and accounting.
- Interface A/R and A/P from the production management system to accounting
- Interface fixed costs from the accounting system to the cost management system
- Interface cost management system calculations as journal entries to the accounting system
However, it is not always necessary to build interfaces in the system; manual or double input is also possible. Even if interfaces are systemized, the human task of "checking and correcting data sequentially from upstream to downstream" remains unchanged. Systemization may result in "downstream checks cannot start because upstream is not ready," creating inconveniences.
While systemizing accounting undoubtedly improves efficiency, systemizing production management does not necessarily increase efficiency. This is especially felt in Indonesia, where "manual systemization" might boost morale and efficiency if operators are exhausted by systems meant to ease their work.
Previously implemented systems directly linking inventory transactions and accounting can be manualized as follows, but this is a countermeasure when systemization complicates processing and humans cannot trace the basis of output figures.
- Manage purchased materials at system's moving average cost as before
- (Debit) R/M (Credit) A/P
2. Manage material issuance quantities in Excel
No journal entry
3. Manage WIP production quantities in Excel
No journal entry
4. Conduct product manufacturing records in the system and manage product inventory valuation at system's standard cost
- (Debit) F/G (Credit) COGS
5. Deduct material quantities and amounts from the system based on physical inventory using the system's moving average cost
- (Debit) COGS (Credit) R/M
6. Confirm WIP inventory valuation based on physical inventory using Excel's standard cost and generate accounting journal entries.
- (Debit) WIP (Credit) COGS
Case: U.S. President Nixon promoted "honorable withdrawal" as a slogan to end the Vietnam War, which was supported by both the war-weary frontline troops and public opinion.
Takeaway: If systems meant to ease work are exhausting operators, "manual systemization" might boost morale and efficiency.
Frequently Asked Questions | Accounting for Inventory Discrepancies
Based on this article, frequently asked questions are summarized briefly.
What happens if inventory discrepancies are recorded in COGS?
Recording inventory discrepancies in COGS decreases gross profit as they are accounted for as inventory shrinkage, directly impacting profit.
What happens if inventory discrepancies are recorded as extraordinary losses?
Recording inventory discrepancies as extraordinary losses decreases operating profit as they are accounted for as non-operating expenses, impacting operating profit.
What causes inventory discrepancies?
Causes of inventory discrepancies include underreported actual input and unrecorded defective products. It is important to investigate these factors and improve actual input.