

In standard costing, not only variable costs such as direct material costs, but also direct labor costs and manufacturing overheads are treated as variable costs. Material costs are analyzed into price variance and quantity variance, labor costs into rate variance and activity variance, and overheads into efficiency variance, capacity variance, and budget variance.
-
-
Cost Management Systems in Indonesia
Mass production factories in Indonesia adopt comprehensive cost accounting. Custom order production factories adopt individual cost accounting.
続きを見る
What this article covers
- In standard costing, direct material costs, direct labor costs, and manufacturing overheads are treated as variable costs.
- The variance in direct material costs is divided into price variance and quantity variance.
- The variance in direct labor costs is classified into rate variance and activity variance.
- Manufacturing overhead variances include efficiency variance, capacity variance, and budget variance.
- In actual costing, costs are calculated using standard material unit prices and actual input quantities.
Variance Analysis in Actual Costing and Standard Costing
In Standard Costing, Direct Labor and Manufacturing Overheads are Calculated as Variable Costs
Manufacturing costs are broadly categorized into direct material costs (materials), direct labor costs (labor), and manufacturing overheads (machinery). Most variable costs consist of direct material costs and subcontracting costs, but some manufacturing overheads, such as utility costs for machinery and shipping costs for specific items, are included as manufacturing variable costs (direct expenses).
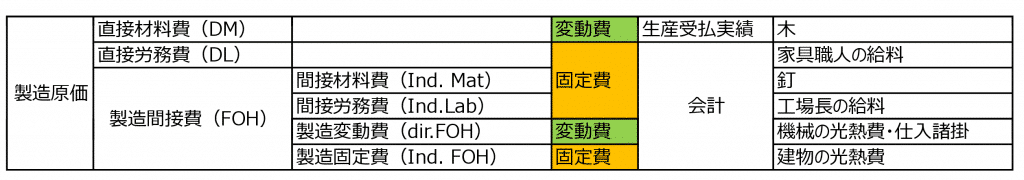
Not only variable costs such as direct material costs, but also fixed costs such as direct labor costs and manufacturing overheads are expressed in formulas similar to variable costs to calculate standard costs.
- Direct Material Cost = Unit Price x Quantity
- Direct Labor Cost = Wage Rate x Labor Hours
- Manufacturing Overhead = Allocation Rate x Operating Hours
Direct Material Costs (Materials)
Production management systems function based on master information such as item master, BOM (Bill of Materials), and unit price master, but in daily operations, they do not always operate according to the master definitions.
There may be discrepancies between the required material quantities based on the BOM and the actual material usage on the shop floor, scrap may occur, and the actual production results may not meet the plan. Additionally, the purchase price at the time of issuing a P/O (Purchase Order) may be lower than the price based on the purchasing unit price master due to negotiations, resulting in differences between master information and actual results.
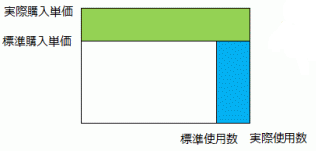
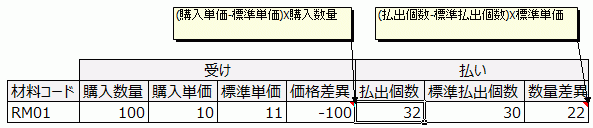
- Price Variance = (Actual Purchase Price - Standard Purchase Price) x Actual Quantity
- Quantity Variance = (Actual Quantity - Standard Quantity) x Standard Purchase Price
The practical report format looks like this.
Direct Labor Costs (Labor)
For direct labor costs, actual work time (activity) for each work procedure is collected through work reports, and the variance caused by the difference between the actual wage rate and the standard wage rate (allocation rate) is the rate variance (Allocation rate difference), while the variance caused by the difference in work time is the activity variance (Activity difference).
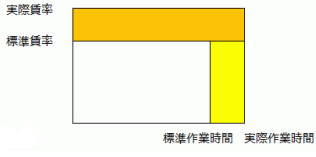
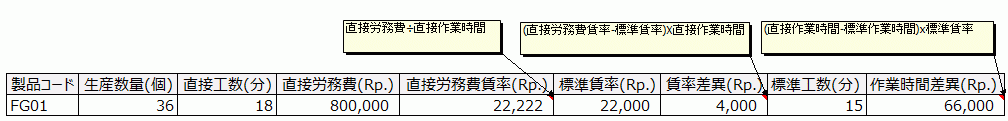
- Rate Variance = (Actual Wage Rate - Standard Wage Rate) x Actual Work Time Actual Wage Rate = Actual Direct Labor Cost ÷ Actual Work Time
- Activity Variance = (Actual Work Time - Standard Work Time) x Standard Wage Rate
The practical report format looks like this.
Actual work time (direct labor hours) can be aggregated by direct department unit (cost center), but to calculate direct labor hours per item (minutes per unit), it is apportioned based on the standard labor hours (Standard activity) set in advance in the master and the production quantity.
- Total Direct Labor Hours per Item = Total Direct Labor Hours per Department x {(Standard Labor Hours x Actual Production Quantity) / SUM(Standard Labor Hours x Actual Production Quantity)}
The concept of calculating direct labor costs per unit as "labor hours x wage rate" is used as a guideline for the ordering side to present to the receiving side as a reference for subcontracting costs, but it is also used when calculating labor costs per product.
Manufacturing Overheads (Machinery)
Most of the variable costs in manufacturing costs consist of direct material costs and subcontracting costs, but strictly speaking, utility costs for operating machinery should be classified as variable costs, and manufacturing overheads are divided into manufacturing variable costs and manufacturing fixed costs.
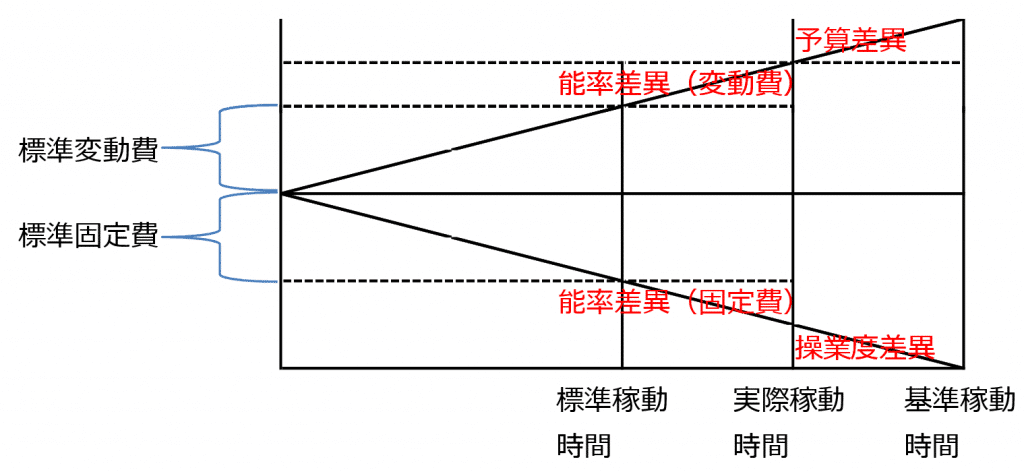
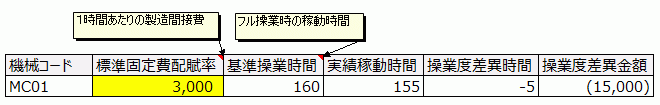
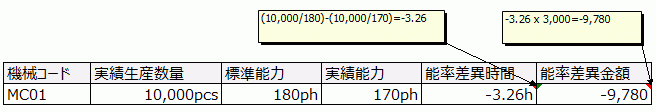
The difference between the standard operating time (full operating time) and the actual operating time is the capacity variance time, and the amount converted into monetary terms by multiplying the standard fixed cost unit price represents the capacity variance, indicating the loss when the machine load (Load) does not meet the capacity (Capacity).
Differences Between Actual Costing and Standard Costing
In actual costing, the total direct material cost is calculated as "standard material unit price x actual input quantity," and the total manufacturing overhead is calculated as "standard unit price (time) x actual work time." As a result, the unit price of products and intermediates can be calculated in real-time (quick cost), and in accounting system-linked ERP packages, journal entries are made using the perpetual inventory method, allowing for constant tracking of inventory valuation.
In standard costing, material costs are calculated as "standard usage = child requirement (BOM) x production quantity," and standard purchase unit price (purchasing unit price master) x standard usage, while in actual costing, it is standard purchase unit price (purchasing unit price master) x actual usage.
For example, when producing 100 products using 4 bolts per product, in standard costing, it is standard purchase unit price x 4 units x 100 units, but in actual costing, it is standard purchase unit price x (4 units x 100 units + NG units). In other words, there is no price variance between actual costing and standard costing, but a quantity variance occurs as standard purchase unit price x variance units.
Additionally, in standard costing, labor costs are calculated as standard wage rate x standard work time, but in actual costing, it is standard wage rate x actual work time (standard work time + loss time). As a result, no rate variance occurs, but an activity variance does.
Frequently Asked Questions | Standard Costing and Actual Costing
Common points asked before variance analysis.
What is the difference in roles between standard costing and actual costing?
The standard is a measure for planning and evaluation, while the actual is a summary of occurrences. The difference is the variance, and a design that allows for comparison at the same granularity is necessary.
What should be looked at first in variance analysis?
The separation of quantity variance and price (unit price) variance. It serves as an entry point to determine whether the cause lies in purchasing, yield, or operation.
What is the significance of having both in the system?
Having evaluation and actual results on separate axes allows for tracking "whether it went according to plan/where it deviated" from both business and accounting perspectives on a monthly basis.