

The three financial statements, consisting of the Profit and Loss Statement, Balance Sheet, and Cash Flow Statement, are the global standard format representing corporate activities. These are essential knowledge to systematically understand in order to generate new ideas based on the essence of business operations.
-
-
Accounting Systems in Indonesia
The adoption rate of SaaS-based accounting systems in Indonesia is less than 8%, despite the advancement of SaaS technology. The continuous launch of new…
続きを見る
What this article covers
- The three financial statements consist of the Profit and Loss Statement, Balance Sheet, and Cash Flow Statement.
- Capital is investment from shareholders, transforming into products and equipment.
- The Profit and Loss Statement shows the flow of revenue and expenses and determines profit.
- The Cash Flow Statement is crucial for understanding the flow of funds.
- The accrual basis recognizes profit and loss at the timing of goods and services provision.
The Standard Format Representing Company Assets, Amounts, and Cash is the Three Financial Statements
In companies and individual businesses, the movement of assets, amounts, and cash is the essence of operations. Even with the advancement of business automation through system implementation, a systematic understanding is necessary to generate new ideas based on real-world events. This differs from information easily obtained online.
The global standard format representing the movement of assets, amounts, and cash is the three financial statements. Comprising the Profit and Loss Statement (P/L), Balance Sheet (B/S), and Cash Flow Statement (C/F), understanding the broad process of creating these is important.
- Capital is investment from shareholders, transforming into products and equipment.
- Purchased goods become COGS when sold.
- Profits are carried over as retained earnings, a source of asset increase for the company.
- There is a discrepancy between accrual-based profits and cash flow differences.
- P/L views revenue and expense flows, B/S views stock, and C/F views income and expenditure flows.
In school, even humanities students were advised to learn English and accounting. Recently, programming is also emphasized. Not only entrepreneurs but also generalists with low specialization need the ability to view the entire company comprehensively.
Converting Transactions into Slide Puzzle Movements
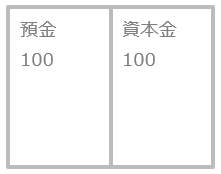
To understand the flow until the three financial statements are generated, it is helpful to liken it to the movement of a slide puzzle when opening a smartphone shop, purchasing 10 items, and selling 4 of them.
1. Transferred 100 million from personal account to company account upon opening.
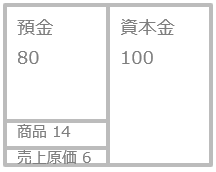
Transferring 100 million from a personal savings account to the shop account creates a piece representing 100 million in shop deposits, balanced by a capital piece. If the deposit balance is insufficient later, additional transfers from the personal savings account use a loan piece instead of capital. Capital is the total stock amount held by shareholders as stated in the company's establishment certificate, and accepting investment from VCs increases the capital piece through third-party allotment.
2. Purchased 10 smartphones at 2 million each.
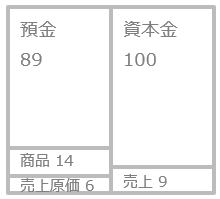
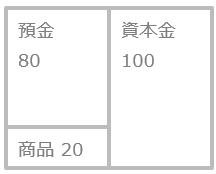
The deposit piece decreases by 20 million and changes to a product piece, balancing the breakdown of capital into deposits and products. This is the perpetual inventory method, but there is also the periodic inventory method, which records cost at purchase and deducts ending inventory from the sum of beginning inventory and purchase cost.
3. Sold 3 smartphones for 9 million paid by debit card.
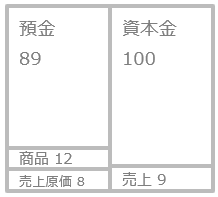
4. Sold 1 smartphone with payment of 3 million deferred to next month.
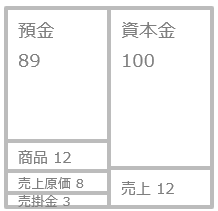
Selling 1 smartphone with a cost of 2 million reduces the product piece by 2 million, changing to a COGS piece, balancing the transaction. Simultaneously, the sales proceeds of 3 million for 1 unit generate an accounts receivable piece, increasing the sales piece by 3 million, balancing the transaction. The accounts receivable piece disappears when payment is received next month, increasing the deposit piece by 3 million to balance the transaction.
5. Confirming the month's profit
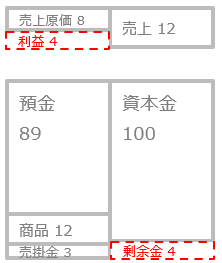
Separating sales and COGS, a profit piece of 4 million is inserted, confirming the month's profit as 4 million. The Profit and Loss Statement (P/L) confirms profit from the flow of expenses and revenues incurred during the month. The remaining pieces are balanced by inserting a retained earnings piece of 4 million, confirming the company's asset status and breakdown at the end of the month. The Balance Sheet (B/S) confirms the shop's asset status. Capital is investment from shareholders, and retained earnings are capital accumulated through business activities.
6. Categorizing the movement of deposits
The balance of 89 million at the end of the month indicates an inflow of 89 million compared to the beginning of the month, as seen by comparing the B/S. To know the details, transaction history must be traced.
The initial inflow of 100 million is based on "financial activities" as capital on the right side of the B/S, the outflow of 20 million for smartphone purchases is based on "investment activities" as product purchases on the left side of the B/S, and the inflow of 9 million from sales is based on "operating activities" reflected on the P/L.
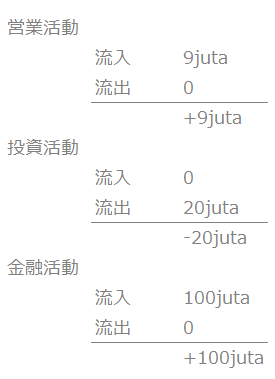
The Cash Flow Statement (C/F) views this movement of cash, supporting the stock of deposit balances on the B/S, and is crucial for understanding the flow of funds in corporate activities, where a shortfall in funds for payments results in game over.
The Relationship Between Profit and Cash Flow
SAGE ACCPAC, a popular accounting system in Indonesia, has two shortcomings.
- It does not issue journal vouchers.
- The Cash Flow Statement (C/F) is not standardly equipped.
This may be because it is an American accounting package software, where issuing journal vouchers for paper-based approval is not customary. However, after the application of International Financial Reporting Standards (IFRS), the Cash Flow Statement will become essential as one of the three financial statements, and future accounting package software will require the creation of C/F using the Direct Method.
In accounting, the profit and loss (expenses and revenues) on the Profit and Loss Statement (P/L) do not necessarily match the cash flow (income and expenditure) on the C/F. Even if there is profit on the P/L, a cash shortage can lead to bankruptcy despite being in the black.
Case: For example, the journal entry for loan repayment from a bank is as follows.
- (Debit) Loan (Decrease in Liability) (Credit) Cash (Decrease in Asset)
This entry indicates a decrease in cash, i.e., an expenditure, but since there is no change in expense or revenue items, it is not recorded on the P/L. This shows that entries related to cash flow are not necessarily linked to profit and loss.
Cash Basis for Cash Flow and Accrual Basis for Profit and Loss
There are two methods for recognizing profit and loss: cash basis and accrual basis. The accrual basis mainly adopts the shipment basis and inspection basis. The cash basis recognizes the timing of cash flow as the timing of profit and loss (revenue and expenses). However, with the generalization of credit transactions (on account), it is common for cash flow and the timing of goods and services provision to differ.
The accrual basis recognizes profit and loss at the timing of goods and services provision, divided into shipment basis and inspection basis.
- At shipment
(Debit) A/R Accrued (Credit) Sales - At invoice issuance
(Debit) A/R (Credit) A/R Accrued - At purchase
(Debit) Purchase (Credit) A/P Accrued - At invoice arrival
(Debit) A/P Accrued (Credit) A/P
A/P Accrued (accrued expenses) and A/R Accrued (accrued revenues) are interim accounts, and since goods and services are not yet provided, they are recorded on the Balance Sheet (B/S) and not recognized as profit and loss.
Case: In an Indonesian auto parts factory, sales and receivables are recorded at the time of shipment, and purchases and payables are recorded at the time of receipt. In this case, no accounting entries occur at invoice issuance or arrival, and at settlement, receivables/payables recorded at receipt are offset against the invoice.
In addition to the accrual basis condition (transfer of goods or services), the realization basis distinguishes the method of recognizing profit and loss by acquiring cash or cash equivalents (monetary assets such as accounts receivable, notes, etc.).
Flow from General Accounting to Financial Statements
Household accounts record cash flow and can grasp cash balances, but they do not reveal the purpose of expenditures or the status of possessions. Therefore, double-entry bookkeeping is used to record a single transaction from two aspects, classified into five items: assets, liabilities, net assets, expenses, and revenues.
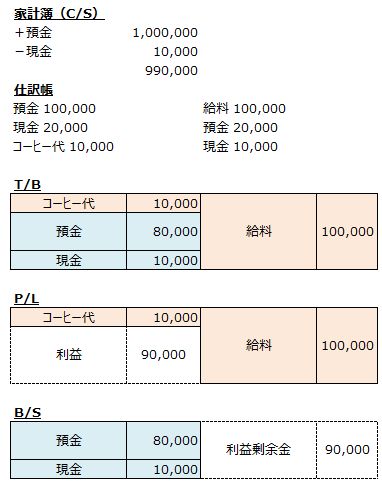
In an accounting system, general accounting refers to journal entries, ledgers, and trial balances, while financial statements refer to the three financial statements: P/L, B/S, and C/F. Typically, daily transactions are recorded in the journal, and those posted by account become the general ledger. In business systems, there is little difference in the positioning of both.
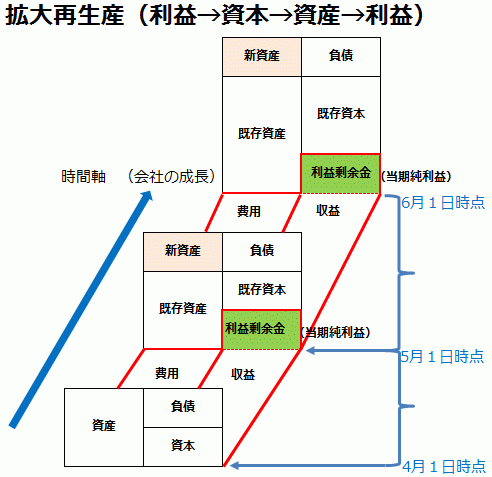
Whether unapproved or approved, all data is stored in the G/L table, and the only difference is whether the output results are viewed by voucher or by account, allowing amounts to be output in debit-credit sets. This is an example of how accounting operations are centralized through systemization, unifying different levels of management ledgers.
- Journal entries exist in the ledger in unapproved and approved states, and the balance of the ledger becomes the trial balance, which is divided into asset, liability, and net asset clusters, and expense and revenue clusters.
- The expense and revenue portion of the trial balance becomes the P/L, and the protruding part of this cluster is profit, matching the indented part of the asset, liability, and net asset cluster in size.
- By inserting profit as retained earnings into the indented part of the asset, liability, and net asset cluster, balance is achieved, completing the B/S.
- The B/S describes the company's assets at a point in time, and the P/L describes the company's profit over a period. The profit from subtracting expenses from revenues on the P/L accumulates as retained earnings on the right side of the B/S, and since the right and left of the B/S match, assets increase by the amount of retained earnings.
Frequently Asked Questions | Three Financial Statements
Common questions about the connection between B/S, P/L, and C/F.
What does each of the three financial statements represent?
The Balance Sheet represents the financial position at a point in time, the Profit and Loss Statement represents the results over a period, and the Cash Flow Statement represents the increase and decrease of funds. They view assets, amounts, and cash from different angles.
Why do profit and cash flow not match?
Because the timing of accrual-based profit and cash flow differs. Accounts receivable, accounts payable, and depreciation create differences.
What are the key points for aligning the three statements in a system?
Consistency in journal entries and period closing. If transactions are correctly posted to the general ledger, the three statements can be developed from the same data.