

In standard cost, the planned production quantity is calculated from the product production plan and BOM. Then, the planned direct working hours are derived from the planned production quantity and the standard cost work efficiency master. Furthermore, the allocation rate is determined from the manufacturing overhead budget and planned production quantity, and the wage rate is calculated from the direct labor cost budget and planned direct working hours.
-
-
Cost Management Systems in Indonesia
Mass production factories in Indonesia adopt comprehensive cost accounting. Custom order production factories adopt individual cost accounting.
続きを見る
What this article covers
- Standard cost calculates planned production quantity from product production plans and BOM.
- Budget cost is calculated by dividing into direct material cost, direct labor cost, and manufacturing overhead.
- In accounting systems, budgets are set by department and compared with P/L and B/S.
- In Indonesia, labor costs are low, making machinery depreciation a significant cost.
- Project cost management adjusts materials, subcontracting, and other groups to maintain initial estimated profit.
Budget Cost in Cost Management System (Item Unit)
Budget means calculating in advance, estimating planned sales and expenses, and predicting profits. In accounting, important tasks are financial closing and budgeting, where financial closing is done after the company completes a year's business activities, and budgeting is done before the company starts a year's business activities.
Actual cost refers to the actual product manufacturing cost, standard cost refers to the standard product manufacturing cost, and budget cost refers to the budget product manufacturing cost. Product manufacturing cost is grouped into direct material cost, direct labor cost, and manufacturing overhead, calculated using the total average unit price and allocation cost accumulation method, or functionally using the three-part method.
In the cost management system, direct material cost is calculated by multiplying the calculated total average unit price by the input performance. Direct labor cost is allocated directly under the manufacturing department, and manufacturing overhead is initially allocated from the indirect department to the direct department, and the aggregation results are apportioned to the product (WIP). The variance between standard cost and actual cost is analyzed by breaking down direct material cost into price variance and quantity variance, and direct labor cost into wage rate variance and working time variance.
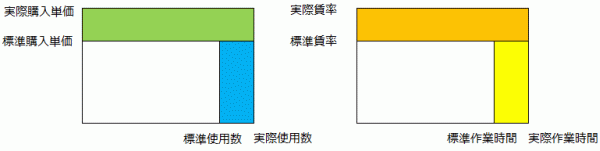
By replacing the master values for standard cost calculation (standard purchase unit price, wage rate, efficiency, allocation rate) with parameters for budget cost calculation, planned direct material cost and planned direct labor cost are derived.
- Standard purchase unit price ⇒ Planned purchase unit price (purchase plan table) ← Master value
- Standard usage quantity ⇒ Planned input quantity (input plan table) ← Automatic calculation
Planned input quantity (input plan table) is automatically calculated from planned production quantity (production plan table) and BOM.
- Standard wage rate (how much per minute) ⇒ Planned wage rate (planned allocation cost, allocation rate table)
- Standard efficiency (how many minutes per unit) ⇒ Planned efficiency (planned direct working time table)
Budget cost calculation is performed by replacing the production performance parameters for actual cost calculation with parameters for budget cost.
- Production performance ⇒ Planned production quantity (production plan table)
Furthermore, by setting the planned sales quantity in the sales plan table and calculating the sales budget, gross profit can be predicted. In the cost management system, budget sales and budget product manufacturing cost are calculated, and variance management with actual results (actual cost calculation results) is performed.
- Sales performance ⇒ Planned sales quantity (sales plan table)
Budget Management in Accounting System (Department Unit, Account Item Unit)
The major difference in master data between the accounting system and the cost management system is the presence or absence of an item master. Since the accounting system does not have an item master, item information is necessary to aggregate transactions from the general ledger (G/L) on an item basis. This difference is reflected in the budget management of the accounting system and the cost management system.
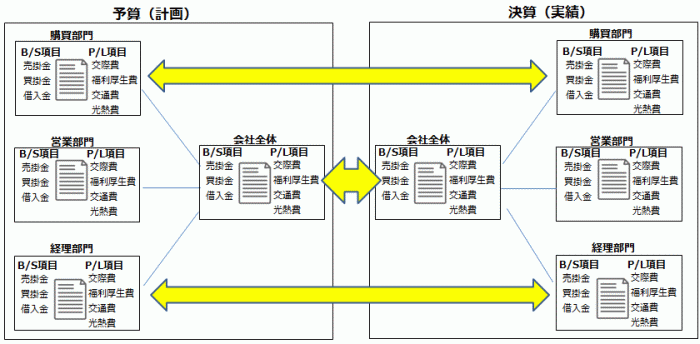
In the cost management system, there is a budget cost calculation function on an item basis, but the accounting system's budget management sets budgets for each department on the items of the profit and loss statement (P/L) and balance sheet (B/S). This allows the company's overall budget to be automatically aggregated and compared with the P/L and B/S figures after closing.
To perform variance management on a department basis, it is necessary to set up departments so that the P/L and B/S items of the accounting system's G/L data can be aggregated on a department basis after closing.
In Japan, the largest expense for companies is often labor costs, but in Indonesia, where labor costs are low, machinery depreciation costs can be the largest cost, or materials may account for the majority of the cost.
Project Budget Management
In long-term projects, material costs, subcontracting costs, and other expenses are transferred to WIP accounts or construction in progress accounts and managed as "assets without sales." These cost estimates exist at the time of project estimation, but in Indonesia, due to inflation and unpredictable additional costs, the initial estimated cost is often exceeded.
Therefore, cost items are divided into three groups: materials, subcontracting, and others, and the overall balance is adjusted to protect the initial estimated profit. Since the estimated cost is confirmed at the time of order registration, project cost management functions (Job Costing) are used to register estimated costs on a project basis and perform variance management of costs through the issuance of purchase orders (P/O) for material purchases and subcontractor services during the project period.
Frequently Asked Questions | Basics of Cost Management and Budget Management
We will briefly organize the frequently asked questions according to the content of this article.
What is the difference between standard cost and actual cost?
Standard cost refers to the standard product manufacturing cost, indicating the manufacturing cost under planned conditions. On the other hand, actual cost is the actual product manufacturing cost incurred. Analyzing these differences can improve the accuracy of cost management.
What is the difference between a cost management system and an accounting system?
The cost management system has a budget cost calculation function on an item basis and manages product manufacturing costs in detail. In contrast, the accounting system performs budget management on a department basis and variance management on the items of the profit and loss statement and balance sheet.
What should be noted in project budget management?
In project budget management, it is important to manage material costs and subcontracting costs as WIP accounts and ensure that the estimated cost is not exceeded. To prepare for inflation and unpredictable additional costs, it is necessary to group cost items and adjust the overall balance.