


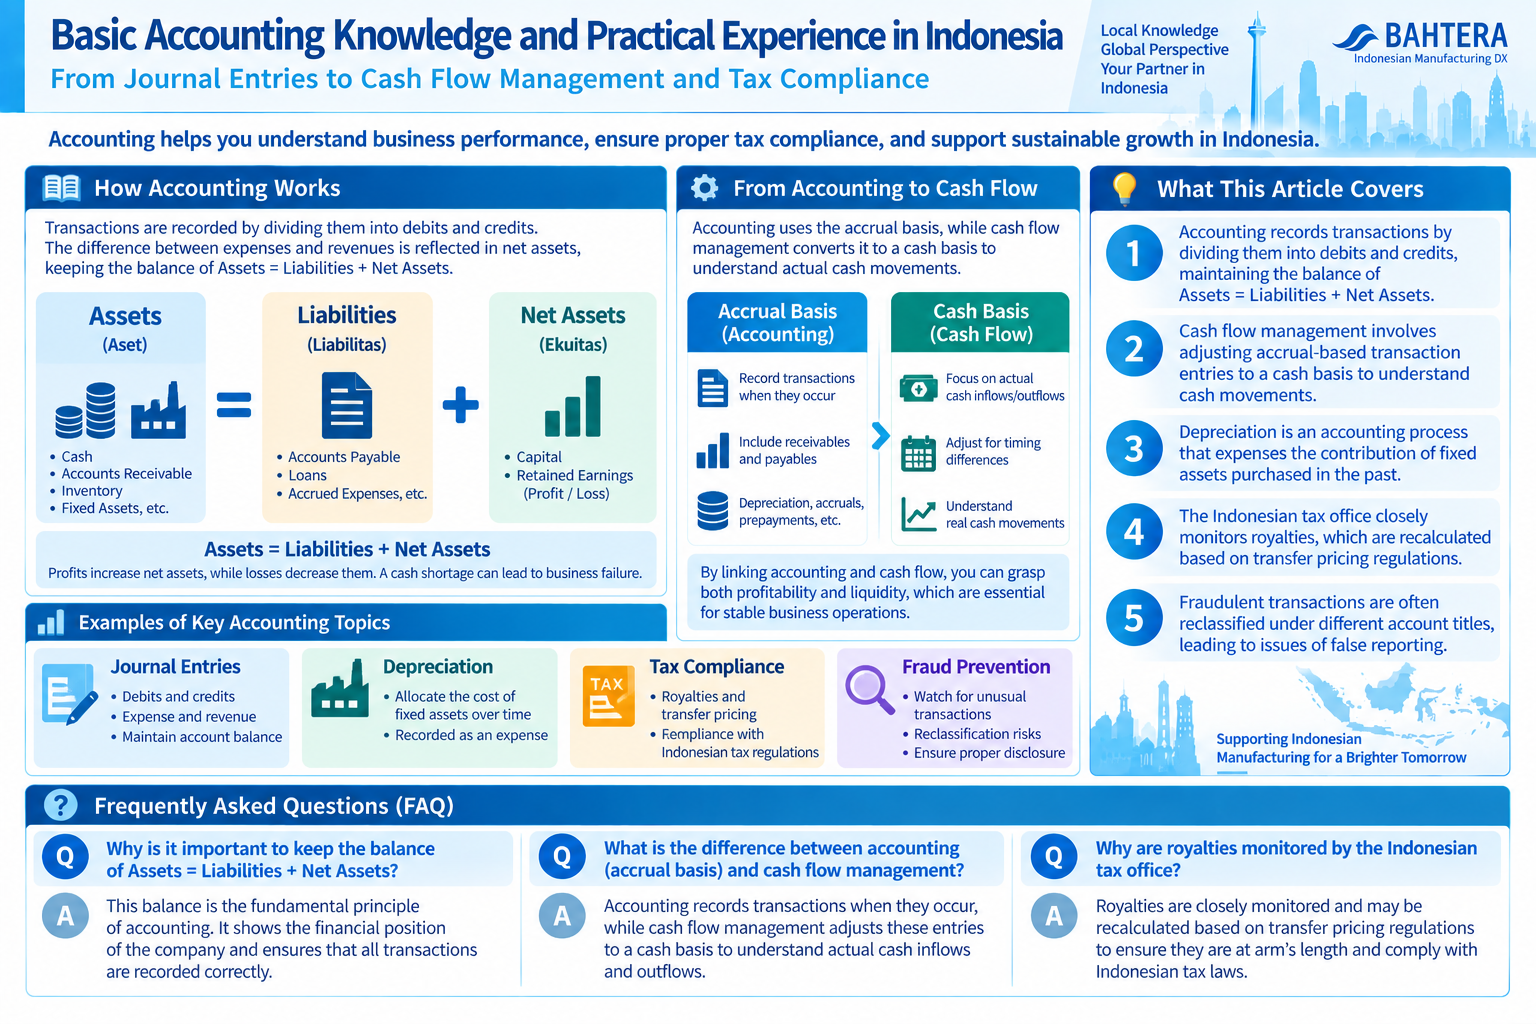
Accounting involves recording transactions by dividing them into debits and credits, incorporating the difference between expenses and revenues into net assets to maintain the balance of "Assets = Liabilities + Net Assets." Cash flow management involves adjusting accrual-based transaction entries to a cash basis to understand cash movements.
-
-
Accounting Systems in Indonesia
The adoption rate of SaaS-based accounting systems in Indonesia is less than 8%, despite the advancement of SaaS technology. The continuous launch of new…
続きを見る
What this article covers
- Accounting records transactions by dividing them into debits and credits, maintaining the balance of Assets = Liabilities + Net Assets.
- Cash flow management involves adjusting accrual-based transaction entries to a cash basis to understand cash movements.
- Depreciation is an accounting process that expenses the contribution of fixed assets purchased in the past.
- The Indonesian tax office closely monitors royalties, which are recalculated based on transfer pricing regulations.
- Fraudulent transactions are often reclassified under different account titles, leading to issues of false reporting.
Accounting Information to Share on This Blog
Based on nearly 20 years of experience implementing business systems in Indonesia, this blog compiles knowledge related to IT and business obtained from conversations with on-site personnel, as well as the challenges faced in advancing projects. I hope this serves as a source of reassurance for expatriates and business travelers who find themselves dealing with tasks outside their main profession in Indonesia.
Access from Japan to this blog is higher for accounting-related entries than for those related to Indonesia. Entries on account transfers, rate calculations, and journal entries for paid and free supplies seem to be viewed by corporate accounting personnel and information systems departments.
-
-
Accounting Treatment and Tax Management of Paid and Free Supply
Paid supply involves selling materials to subcontractors and purchasing the work-in-progress after processing. In Indonesia, paid supply is required as free…
続きを見る
While accounting knowledge is not necessarily required for working in business systems, having such knowledge allows for deeper discussions with Indonesian accounting personnel.
I once aimed to become an accountant during my student days, passing the second level of the Japan Chamber of Commerce bookkeeping exam, but failing the first level. My interest in Indian classical music led me to spend long vacations in India, and my dream of becoming an accountant faded.
When I received news that my junior, Mr. S, who left the Chinese martial arts club to focus on the accounting exam, passed in his fourth year, I felt a mix of congratulations and envy. I realized I couldn't fully commit to exam studies like he did.
Although I lack the specialized knowledge of an accountant, I aim to share the knowledge and experience gained from implementing and operating accounting systems, which cannot be obtained from academic studies in accounting or bookkeeping.
The Intriguing Aspect of Accounting as a Slide Puzzle
In accounting, a transaction is recorded by dividing it into debits and credits. By extracting items related to expenses and revenues from a month's journal entries and subtracting them, the resulting profit (or loss) is incorporated into net assets. This creates a "slide puzzle" mechanism where "Assets = Liabilities + Capital (Net Assets)" balances. Profits increase capital, while losses decrease it, and a cash shortfall results in a company game over.
All transactions corresponding to debits and credits
- Increase in assets <-> Decrease in assets
- Decrease in liabilities <-> Increase in liabilities
- Decrease in capital <-> Increase in capital
- Increase in expenses <-> Decrease in expenses
- Decrease in revenue <-> Increase in revenue
The profit and loss for the current month (or period) is calculated using the P/L (Profit and Loss Statement), and the resulting state of assets, liabilities, and net assets is known through the B/S (Balance Sheet). All figures are based on real-world transactions.
The Challenge of Introducing the Concept of Time to Transactions in the Real World
The real world is a three-dimensional space formed by up, down, left, right, front, and back. However, in accounting, the concept of time is introduced to transactions occurring in this three-dimensional space, creating a four-dimensional awareness for recording. For example, when purchasing fixed assets like machinery or inspection equipment, they become your property through cash payment or credit. If these fixed assets contribute directly or indirectly to profits, the portion that contributed is expensed and deducted from sales to ensure fair profits.
Thus, even if a transaction has not occurred in the real world, past purchases of machinery (fixed assets), stationery (supplies), or prepaid insurance premiums (assets granting the right to free or discounted treatment) are considered to have contributed to the current month's sales. The contribution of these assets is converted into monetary value and expensed. The concept of time is added to real-world transactions, creating a four-dimensional space.
Just like Doraemon's pocket connects to a four-dimensional space, typical transactions that expense past payments in the future (current period) include depreciation, accrued accounts (prepaid expenses), and supplies.
Fixed assets purchased in the past are considered to have contributed to the current month's sales, so the contribution is expensed. The acquisition cost of fixed assets remains unchanged, and the book value is calculated indirectly using accumulated depreciation.
- (Debit) Fixed Assets 900 (Credit) Deposits 900
- (Debit) Depreciation Expense 10 (Credit) Accumulated Depreciation 10
Thanks to the insurance premiums paid for a year in the past, free or discounted treatment can be received at hospitals this month.
- (Debit) Prepaid Insurance Premiums 80 (Credit) Deposits 80
- (Debit) Insurance Expense 10 (Credit) Prepaid Insurance Premiums 10
Of the supplies paid for in the past, the portion consumed this month is considered to have contributed to the current month's sales.
- (Debit) Supplies 90 (Credit) Cash 90
- (Debit) Supplies Expense 10 (Credit) Supplies 10
The principle of accrual accounting involves recognizing revenue or expenses based on the occurrence or change of economic events, regardless of cash inflows or outflows. Input into business systems, including accounting, is fundamentally based on accrual accounting.
The Challenge of Returning from Four-Dimensional to Three-Dimensional Cash Movements
Why return to three-dimensional cash movements after incorporating the concept of time into transactions based on the principle of accrual accounting? In reality, the presence or absence of cash determines a company's survival. To understand the cash movements and balance for the current month, it is necessary to adjust the P/L created on an accrual basis to a cash basis.
Cash flow management involves adjusting accrual-based performance input to a cash basis to understand the movements of cash and deposits that can be freely moved. A company being profitable refers to generating profit on the P/L.
- Expenses and revenues that have occurred but are unpaid
- Depreciation expense
By adjusting these, a cash flow statement is created, providing management information to respond to immediate settlements on a cash basis.
The Challenge of Different Values Based on the Background of Three-Dimensional Objects
In the real world, the valuation of the same product differs between inventory from the previous month and those manufactured this month. Since shipped products contain both, the breakdown of cost of goods sold is as follows:
- Unit cost of product inventory from the previous month × quantity shipped
- Unit cost of products manufactured this month × quantity shipped
Thus, even products that appear the same have different valuations based on the manufacturing period. "Manufacturing cost = cost of goods sold" only holds true for make-to-order production where only sellable items are produced. Businesses with large inventories tend to have a greater disparity between manufacturing cost and cost of goods sold.
- The cost of materials purchased this month is the cost of materials purchased this month
- The cost of materials used this month from the beginning inventory and materials purchased this month is the material cost for the month (accrued)
- The direct labor cost and manufacturing overhead for this month are the processing costs for the month
- The cost of products completed this month from the beginning WIP inventory, material cost for the month, and processing cost for the month is the manufacturing cost
- The cost of products shipped this month from the beginning product inventory and products completed this month is the cost of goods sold
In reality, the valuation is calculated as accurately as possible based on the Indonesian Company Law, internal resources, and the judgment of the management department, and reflected in the inventory section of the B/S. However, if there are counting errors during the actual inventory process, the resulting figures will be incorrect. If the inventory of materials and WIP is underestimated, it is considered that more was invested in production, increasing manufacturing costs and reducing profits. Conversely, if inventory is overvalued, it is considered that less was invested in production, reducing manufacturing costs and increasing profits.
The Theme of "What to Study During Student Days"
During my student days, I was told to study English to adapt to the international community and bookkeeping accounting to hone economic sense. It was already well-known that English would be necessary in society, and even now, working in Indonesia, I feel embarrassed as a Japanese person with poor English among Indonesians who are proficient in English.
In recent years, web programming, which allows work anywhere in the world, has been gaining popularity. Programming was learned through practical training in computer science, an elective subject at the time, using the FORTRAN77 programming language with 8-inch diskettes. Nowadays, with the widespread use of PCs and the internet, self-study for building websites is possible.
English and programming are motivating to study because one can envision working stylishly with them as a weapon. However, bookkeeping accounting may be harder to imagine the benefits, as it conjures up scenes of tapping calculators in the accounting department, even if one is told they will be able to read financial statements.
Humanities students often feel a kind of inferiority complex towards science students due to the lack of a clear major. In my case, being in a macroeconomics-oriented, financial economics seminar in the commerce department, I had a vague major, so I felt the need to at least take the bookkeeping exam to leave a trace of what I learned at university.
Stories That Lack the Image of Company Continuity Constraints and Cash Flow Seem Dubious
Unless assigned to the accounting department or aiming to become an accountant, even ordinary people who study a bit of bookkeeping accounting become aware of questions like "What does this company (or person) sell to make money?" or "Which account will this be processed under?" when watching the news.
All businesses, whether freelance, manufacturing, or service, are ultimately evaluated in terms of money. All transactions leading up to this are converted into accounting journal entries and reflected in the P/L (Profit and Loss Statement) and B/S (Balance Sheet) through a process. For example, even casual words often seen online involve transactions.
- Earning millions every month (Debit) Deposits (Credit) Sales
- Successfully raised billions in funding (case of third-party allotment) (Debit) Deposits (Credit) Capital
- Expanding into Indonesia as part of the Southeast Asia strategy (establishing a local subsidiary). (Debit) Deposits (Credit) Capital
- Made a fortune with Bitcoin (case of selling). (Debit) Deposits (Credit) Cryptocurrency (Credit) Gain on Sale
- Living as a freelancer while traveling the world. (Debit) Deposits (Credit) Sales
- Living by doing only what I love with passive income (affiliate marketing on a blog). (Debit) Accounts Receivable (Credit) Sales (when confirmed) (Debit) Deposits (Credit) Accounts Receivable (when transferred)
Thus, while cash increases in the bank account as sales from business activities are generated, expenses are constantly incurred to continue the business. For example, a company with capital of 10,000 can only record expenses of 2,500 per month for four months, and if sales are not generated before the source of capital, deposits (money), run out, the company will go bankrupt.
In the month the company is established, personal money is converted into the company's assets (deposits).
- (Debit) Deposits (money) 10,000 (Credit) Capital 10,000
In the first few months, only expenses are incurred for office supplies and product purchases.
- (Debit) Expenses 2,500 (Credit) Deposits (money) 2,500
Finally, sales are generated the following month.
- (Debit) Deposits (money) 8,000 (Credit) Sales 8,000
In other words, sales from business activities must replenish cash in the current account before funds run out, under the constraint of avoiding a cash shortfall. Without a concrete image of this basic company continuity constraint and cash flow in the background of such glittering phenomena, there is a sense of dubiousness.
This feeling is likely similar to what a bank loan officer experiences when listening to someone seeking a loan, assessing whether the business is sustainable and whether the principal and interest can be repaid.
Accounting Transactions Occur Even in Fraudulent Money Flows
It is extremely difficult for publicly traded companies, whose securities reports are guaranteed to be appropriate by external audits, to conduct off-the-books transactions involving billions of yen. Therefore, when fraudulent transactions are discovered, they are usually reclassified under more plausible different account titles.
- "Reclassification" to Selling, General and Administrative Expenses (SGA) ⇒ Money from Nissan's CEO reserve flowed to Middle East Nissan as sales promotion expenses, then tunneled through an Oman dealership to Mr. Ghosn's investment company.
- "Circular Transactions" through Paid Supply ⇒ Toshiba inflated sales by double-counting when supplying LCD manufacturing to subcontractors as paid supply.
- "Transfer Pricing" as Sales Commission or Consultant Fees ⇒ Transfer pricing to local subsidiaries in tax havens like the Cayman Islands for tax avoidance, as seen with Nippon Credit Bank and Olympus.
On April 4, 2019, former Nissan chairman Carlos Ghosn was arrested for the fourth time on charges of violating the Companies Act (special breach of trust) for causing damage to the company by illegally remitting funds to Oman in the Middle East. The arrests on November 19 and December 10, 2018, were due to underreporting executive compensation by a total of 5 billion yen, leading to Nissan's securities reports being deemed false and violating the Financial Instruments and Exchange Act.
In the Financial Instruments and Exchange Act violation, the issue was whether Mr. Ghosn's fraud could be proven, but Nissan's executive compensation, an SGA account on the P/L, was underreported, and the difference may have been reclassified to another SGA account.
- (Debit) Executive Compensation 5 billion yen (Credit) Current Account 5 billion yen
Subsequently, on December 21, he was arrested for the third time on charges of special breach of trust for reclassifying swap contract losses between his personal asset management company and Shinsei Bank to Nissan, but was released on bail on March 6, 2019, as the actual damage to Nissan could not be proven.
However, this time's violation of the Companies Act (special breach of trust) is completely black, with suspicions that, in addition to the 3.8 billion yen sent from Nissan to Mr. Ghosn's investment company via Middle East Nissan and an Oman dealership, Mr. Ghosn's personal yacht purchase costs and his four children's Stanford University expenses were recorded as fictitious SGA in Nissan's accounting and misappropriated for personal use.
- (Debit) Sales Promotion Expenses 3.8 billion yen (Credit) CEO Reserve 3.8 billion yen
Economic news labeled as "inappropriate accounting" aims for tax evasion, personal misappropriation, or window dressing, and all involve false statements in securities reports, leading to incorrect P/L and B/S figures, with shareholders suffering the most. Nissan is an automobile manufacturer, and all costs, including material and labor costs for producing cars, are included in manufacturing costs.
This incident is entirely recorded as SGA from the CEO reserve, which Mr. Ghosn could spend at his discretion. Although Nissan's image is inevitably tarnished by Mr. Ghosn's fourth arrest, it is important to emphasize that the manufacturing sites responsible for the core business of making products bear no responsibility.
On December 30, 2019, Carlos Ghosn fled Japan illegally and escaped to Lebanon.
Tax Havens and Transfer Pricing
When I joined a former long-term credit bank system company as a new graduate, I was first assigned to a department developing and operating overseas branch systems on AS/400 using RPG (Report Program Generator) and CL (Control Language). The list of overseas branches included famous cities like London and New York, but the Cayman branch was particularly unique.
A senior colleague explained that the Cayman Islands is a special zone with tax advantages, and most Japanese banks have branches there for tax savings.
Later, I forgot about the Cayman Islands after transferring to Indonesia, but I heard the name again during the Olympus loss concealment scandal in 2013. When suffering significant losses in real estate or financial assets, the principle of mark-to-market accounting requires loss processing. However, during the 1997 Yamaichi Securities bankruptcy, real estate with latent losses was sold at book value to non-consolidated related companies, and the losses were recorded by the related companies in a practice known as "tobashi."
The Olympus scandal occurred in 2013, a time when such blatant "tobashi" was no longer acceptable. It seems that the method used was to overvalue essentially worthless paper companies for M&A, generate slush funds to cover losses, and "reclassify" financial losses as M&A losses.
The Cayman Islands has a law allowing companies that do not conduct business on the island to avoid paying corporate taxes, attracting tax avoidance money. The country's finances are supported by company establishment, operation, and remittance fees, a strategy unique to a country with a small population. The island's approximately 50,000 residents live almost tax-free with well-developed social security.
In fact, like the bank that was my former employer's parent company, large corporations worldwide establish paper companies and use Cayman branches for tax-saving purposes. This aligns with the corporate goal of maximizing shareholder profits, but from the perspective of ordinary citizens, it may seem like free-riding on public services without paying taxes to one's own country.
Unrelatedly, a few months before I transferred to Indonesia, a real estate leasing company affiliated with this bank revealed massive real estate losses due to the bubble collapse, and a director seconded from the bank was involved in the incident, which became news. This incident triggered the disappearance of the bank itself.
Transfer pricing regulations were introduced in Japan in 1986, and I worked in Japan around 1995. If the operating income from long-term financial bonds issued in Japan was recorded as consulting fees or sales commissions and remitted to the Cayman branch, it would have been considered transfer pricing.
Royalty and Dividend as Account Titles
When implementing an accounting system, it is necessary to prepare account titles first. As accounts for Japanese headquarters to recover investments from Indonesian bases, there are royalty and dividend. Royalty is often classified as Production Royalty for manufacturing cost accounts, Sales Commission for SGA accounts, and dividend is classified as a liability account as Dividend Payable.
Royalty is an important account between Indonesian subsidiaries and Japanese headquarters, closely monitored by the Indonesian tax office. In the worst case, it may be denied as transfer pricing. Even if recognized as legitimate royalty, it is recalculated based on transfer pricing regulations, and a 20% withholding tax called PPh26 must be paid.
Since Japan and Indonesia have a tax treaty, it is possible to apply a reduced tax rate in Indonesia by paying a certain amount of tax in Japan. By obtaining a withholding tax certificate (Bukti potong PPh26) in Indonesia and submitting it to the Japanese tax office, double taxation can be avoided.
Ideally, investment recovery in the form of dividends is desirable, but the Indonesian tax office currently denies dividend recognition unless a company has posted operating profits for several consecutive years.
Transfer Pricing and Profit Manipulation
Recently, when purchasing packaged software developed in Japan from an overseas base in Malaysia, I was told, "Discount sales could be considered transfer pricing in Japan, so we cannot offer preferential treatment just because it's Indonesia." It is disheartening when discount sales made out of goodwill are suspected by authorities of transfer pricing or profit manipulation.
Case: In Indonesia, "friend prices" are very risky, and offering products without profit because "you're a valued customer" may be considered profit manipulation by the tax office. Ultimately, it may not benefit either party.
Takeaway: Offering products at no profit as a friendship price carries the risk of being considered profit manipulation for tax purposes.
Frequently Asked Questions | Basic Accounting and Practical Experience
Based on the content of this article, frequently asked questions are briefly organized.
What is the basic mechanism of accounting?
Accounting involves recording transactions by dividing them into debits and credits, incorporating the difference between expenses and revenues into net assets to maintain the balance of "Assets = Liabilities + Net Assets." This allows for an accurate understanding of a company's financial status.
How does practical accounting experience in Indonesia help?
Nearly 20 years of experience implementing business systems in Indonesia provides valuable knowledge gained from conversations with on-site personnel. This serves as foundational knowledge for expatriates and business travelers to engage in deep discussions with local accounting personnel.
What is the difference between accrual and cash basis accounting?
Accrual accounting records revenue and expenses when transactions occur, while cash basis accounting records them when cash is received or paid. Cash flow management involves adjusting the P/L created on an accrual basis to a cash basis to understand cash movements.