

If there are no input records for items with beginning inventory, those items continue to be recorded as assets on the B/S and are not expensed as manufacturing costs for the month. Assuming there are no uncompleted inputs, the essence of actual cost calculation lies in calculating the manufacturing cost of input items by accumulating the average unit cost by cost item and allocating the processing costs of the current process.
-
-
Cost Management Systems in Indonesia
Mass production factories in Indonesia adopt comprehensive cost accounting. Custom order production factories adopt individual cost accounting.
続きを見る
What this article covers
- Items with beginning inventory but no input records continue to be recorded as assets on the B/S.
- The average method calculates manufacturing costs using the monthly average valuation of input items and current process costs.
- The cumulative method (Rolling Costing) transfers the manufacturing cost of the previous process as the input cost for the current process.
- The average unit cost is calculated based on beginning inventory and current month production, forming the basis for the evaluation amount of input performance for the next process.
- Cost variance analysis shows how much the manufacturing cost for the month deviates from the standard cost.
Manufacturing Cost Calculation Using the Average Method
Manufacturing costs are calculated using the three-part method as "beginning WIP + current month manufacturing costs - ending WIP". The method of transferring the manufacturing cost of the previous process to the current month's manufacturing costs of the current process and calculating product costs at multiple levels using the three-part method is called the rolling costing method.
On the other hand, the average method calculates manufacturing costs as "monthly average valuation of input items + current process costs". The average unit cost is calculated sequentially from materials to products, and accumulating the costs of each process as "(average unit cost x input quantity) + current process incurred processing costs" is called the accumulation method. Both the rolling costing method and the accumulation method result in the same outcome, so they are generally used synonymously.
- Average Unit Cost = (Beginning Inventory Amount + Current Month Manufacturing Cost) / (Beginning Inventory Quantity + Current Month Manufacturing Quantity)
The characteristic of the average method is that it allows for the calculation of issuance costs using the average unit cost, taking into account beginning inventory information. The average unit cost of the production items in the current process is applied to the input performance unit cost of the next process.
- Input Performance Quantity x Average Unit Cost
- Direct Labor Costs (Current Process Incurred Costs)
- Manufacturing Overhead (Current Process Incurred Costs)
The total of these becomes the manufacturing cost for the month, and the average unit cost is determined by considering the beginning inventory, which is then applied as the unit cost of input performance for the next process, ultimately becoming the product manufacturing cost in the final process.
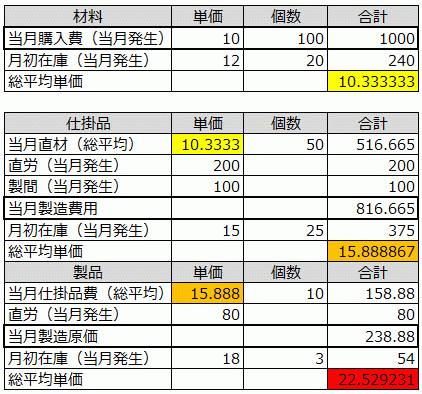
Concept of the Cumulative Method (Accumulation Method)
In production management systems, receipt and issue quantities are managed based on account connection diagrams, and manufacturing costs are calculated in cost management systems. First, the direct material costs input into the initial process are calculated using the average method.
- Direct Material Costs = Average Unit Cost of Input Materials x Input Quantity
The WIP manufacturing cost, which includes these direct material costs and processing costs, is treated as the incurred costs of the input items for the next process, and similarly, the WIP manufacturing cost of the next process is calculated using the average method.
- Cost of Input WIP = Average Unit Cost of Input WIP x Input Quantity
This method is called the cumulative method (Cumulative Method = Rolling Costing). The material cost based on the issue quantity of materials issued becomes the incurred cost based on the input quantity into WIP, and the WIP cost based on the production quantity of the produced WIP becomes the incurred cost based on the input quantity into products, and the COGS based on the shipment quantity of the shipped products.
Usually, materials and WIP become inventory or are used as common materials for multiple products, so the incurred costs based on the production quantity of the current process are greater than the incurred costs based on the input quantity of the next process.
If materials or WIP are not common materials, 100% of the incurred material costs or incurred costs based on the production quantity of the current process become the incurred costs based on the input quantity of the next process, and in the case of products, 100% of the incurred costs based on the production quantity (manufacturing cost) become the incurred costs based on the input quantity of the product.
In contrast to the cumulative method, where the incurred costs of the current process are accumulated as input costs for the next process according to the account connection diagram, the non-cumulative method is a method of calculating product manufacturing costs at once by considering the first to third processes as a single process.
In other words, the cumulative method considers products as the accumulation of cost item codes by process, while the non-cumulative method aggregates the costs incurred in each process into the cost item code of the product itself.
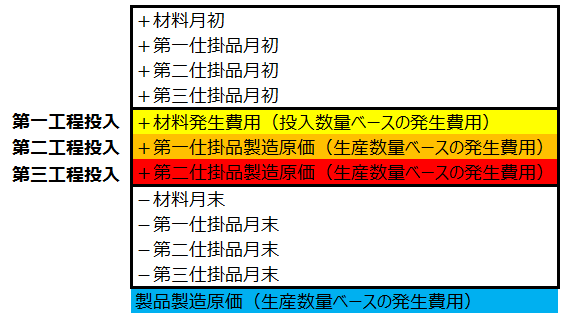
Non-Cumulative Method
Relationship Between Manufacturing Costs and Average Unit Cost
There is a lot of talk about the certification fraud issue of major automobile manufacturers, but if shipments are halted, the production volume for that month drops significantly, and as production quantity falls, the ratio of fixed costs such as depreciation and labor costs per product increases, resulting in an increase in manufacturing costs per product.
While adjusting production quantities in response to market changes, monthly fixed costs remain constant, so calculating manufacturing costs based on actual production quantities tends to lead to shortsighted cost management. Therefore, a leveled standard cost throughout the year is determined before creating the budget for the next term, and sales and procurement plans are made.
Cost variance indicates how much the manufacturing cost for each month deviates from this standard cost, and cost variance analysis breaks down the variance by factors such as purchase price, purchase quantity, and operating time.
Cost variance represents how much the manufacturing cost for the month deviates from the standard cost, which is the benchmark, and the inventory accumulated at the beginning of the month is not responsible for this cost variance, but at the time of shipment, both the inventory and the current month's production are evaluated together at the average cost, ultimately bearing joint responsibility as the COGS unit price.
The manufacturing cost unit price is the unit price of the current month's production, and the average unit cost is the overall unit price combining the beginning inventory and the current month's production. The average unit cost of the product becomes the COGS unit price.
It is easy to get confused when told "calculate manufacturing costs using the average unit cost," but this does not mean "product average unit cost x production quantity." The average unit cost of the product is calculated based on "beginning product inventory + current month product manufacturing cost," and is determined after calculating the manufacturing cost.
In other words, the average unit cost that exists at the time of manufacturing cost calculation is only the average unit cost of the input items, as the average unit cost is calculated from downstream to upstream. The average unit cost is calculated by cost item and is reflected by cost item in the current manufacturing cost of the input items of the next process.
- Direct Material Average Unit Cost = (Beginning Direct Material + Current Month Direct Material) / (Beginning Quantity + Current Month Quantity)
- Direct Labor Average Unit Cost = (Beginning Direct Labor + Current Month Direct Labor) / (Beginning Quantity + Current Month Quantity)
- Manufacturing Overhead Average Unit Cost = (Current Month Manufacturing Overhead + Current Month Manufacturing Overhead) / (Beginning Quantity + Current Month Quantity)
These cost item-specific average unit costs are also accumulated as they go upstream, but cost items that do not incur costs in the current process are not recorded in the cost item-specific incurred costs, as they are the same amount as the cumulative cost of the previous process. The current month's manufacturing cost evaluates the incurred costs of the input items of each process by cost item-specific average unit cost.
Cost Item-Specific Accumulation Calculation of Average Unit Cost
By performing cost item-specific accumulation calculations of the average unit cost, the current month's manufacturing cost by cost item can be automatically calculated by multiplying the usage quantity. The average unit cost is only calculated once the current month's manufacturing cost and beginning inventory amount are aligned. This average unit cost becomes the basis for the evaluation amount of input performance for the next process.
The total of the input performance evaluation amount using the average unit cost and the current process processing costs (by allocation) becomes the current month's manufacturing cost, and by repeating this from upstream (materials) to downstream (products), the manufacturing cost and average unit cost of the final product are determined.
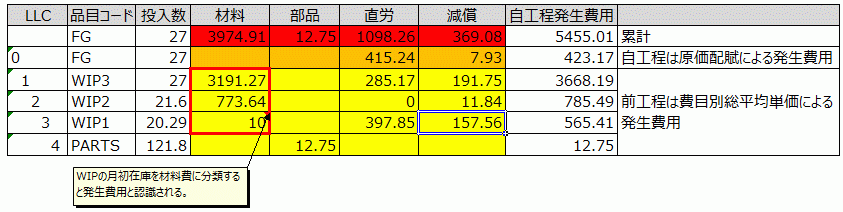
The average unit cost is accumulated by cost item from upstream to downstream, and the difference from the cumulative amount up to the previous process becomes the average unit cost of the current process incurred portion.
Comprehensive Cost Calculation is Suitable for Forecast Production (Mass Production)
In the three-part method, manufacturing costs are calculated as "beginning WIP + current month manufacturing costs - ending WIP," but in the average method, they are calculated as "average valuation of input items + current process incurred costs." Therefore, it is necessary to calculate the average unit cost sequentially from materials to products.
In factories that adopt comprehensive cost calculation, there are usually multiple manufacturing processes, and the process costs are determined for each process. There are cumulative and non-cumulative methods for aggregating into products.
The cumulative method (Cumulative method) is the "rolling costing method," which transfers the manufacturing cost of the previous process (beginning + current month costs - ending) as the input cost of the current process and calculates product costs at multiple levels using the three-part method. This is close to the image of the account connection diagram.
- 1st Process: Beginning WIP1 + Current Month Materials + Current Month Processing1 - Ending WIP1 = Current Month WIP1 Manufacturing Cost
- 2nd Process: Beginning WIP2 + Current Month WIP1 Manufacturing Cost + Current Month Processing2 - Ending WIP2 = Current Month Product Manufacturing Cost
"Rolling Costing" is "accumulation calculation" and is also "rolling costing method." It is the "cumulative method (Cumulative method)" that accumulates the processing costs of each process sequentially according to the account connection diagram, starting from material costs.
The non-cumulative method (Non-cumulative method) is a method of calculating each process cost at a single level without including the previous process costs and directly summing them to determine the product cost.
- (Cost of 1st Process in Product) Beginning WIP1 + Beginning WIP (1st part of 2nd) + Current Month Processing1 - Ending WIP1 - Ending WIP (1st part of 2nd)
- (Cost of 2nd Process in Product) Beginning WIP (2nd part of 2nd) + Current Month Processing2 - Ending WIP (2nd part of 2nd)
- 1st Process Cost + 2nd Process Cost = Current Month Product Manufacturing Cost
Receipt and Issue Performance Data for the Average Method
The performance data on the production management system that occurs in the process of purchasing materials, providing processed WIP to subcontractors free of charge, and shipping subcontracted processed products is as shown in the figure below.
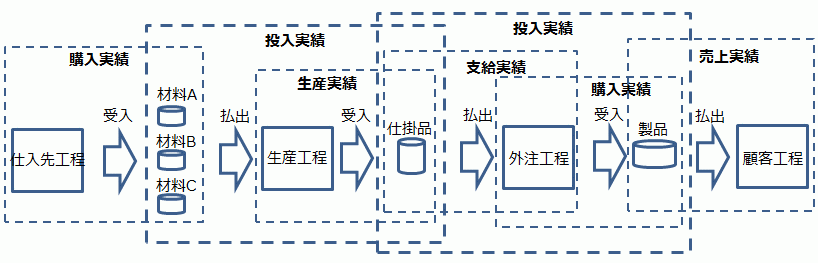
- Issue Performance ⇒ For Transfer to Other Accounts Deduct scrap and inventory shrinkage due to defects from COGS. WIP unit cost is evaluated by accumulating the current month's "average unit cost + processing costs".
- Input Performance ⇒ For Direct Material Cost Calculation It is the incurred cost based on input, indicating how many units of the child were input to the parent.
- Production Performance ⇒ For Direct Material Cost Calculation It is the incurred cost based on production, indicating how many units of the parent were produced.
- Supply Performance ⇒ For Direct Material Cost Calculation It indicates how many units were supplied to the subcontractor.
- Purchase and Subcontract Performance ⇒ For Direct Material and Subcontract Processing Cost Calculation It indicates how much the purchase cost was for materials and how much the subcontract processing cost was for products.
- Sales Performance ⇒ For COGS Calculation Calculate gross profit.
Frequently Asked Questions | Basics of Manufacturing Cost Calculation
In line with the content of this article, frequently asked questions are briefly organized.
How is manufacturing cost calculated using the average method?
In the average method, manufacturing costs are calculated by adding the current process incurred costs to the monthly average valuation of input items. Specifically, the average unit cost is calculated sequentially from materials to products, and the costs of each process are accumulated as "(average unit cost x input performance quantity) + current process incurred processing costs." This allows for the calculation of issuance costs using the average unit cost, taking into account beginning inventory information.
What is the cumulative method?
The cumulative method (Cumulative Method) is a method of calculating product costs at multiple levels using the three-part method by transferring the manufacturing cost of the previous process as the input cost of the current process. This is also called the "rolling costing method," where processing costs of each process are accumulated sequentially according to the account connection diagram. By accumulating costs for each process, the manufacturing cost of the product is ultimately determined.
What is the difference between the non-cumulative method and the cumulative method?
The non-cumulative method is a method of calculating each process cost at a single level without including the previous process costs and directly summing them to determine the product cost. On the other hand, the cumulative method transfers the manufacturing cost of the previous process as the input cost of the current process and accumulates the costs of each process to calculate the product cost. The non-cumulative method calculates each process independently, while the cumulative method emphasizes inter-process linkage.