


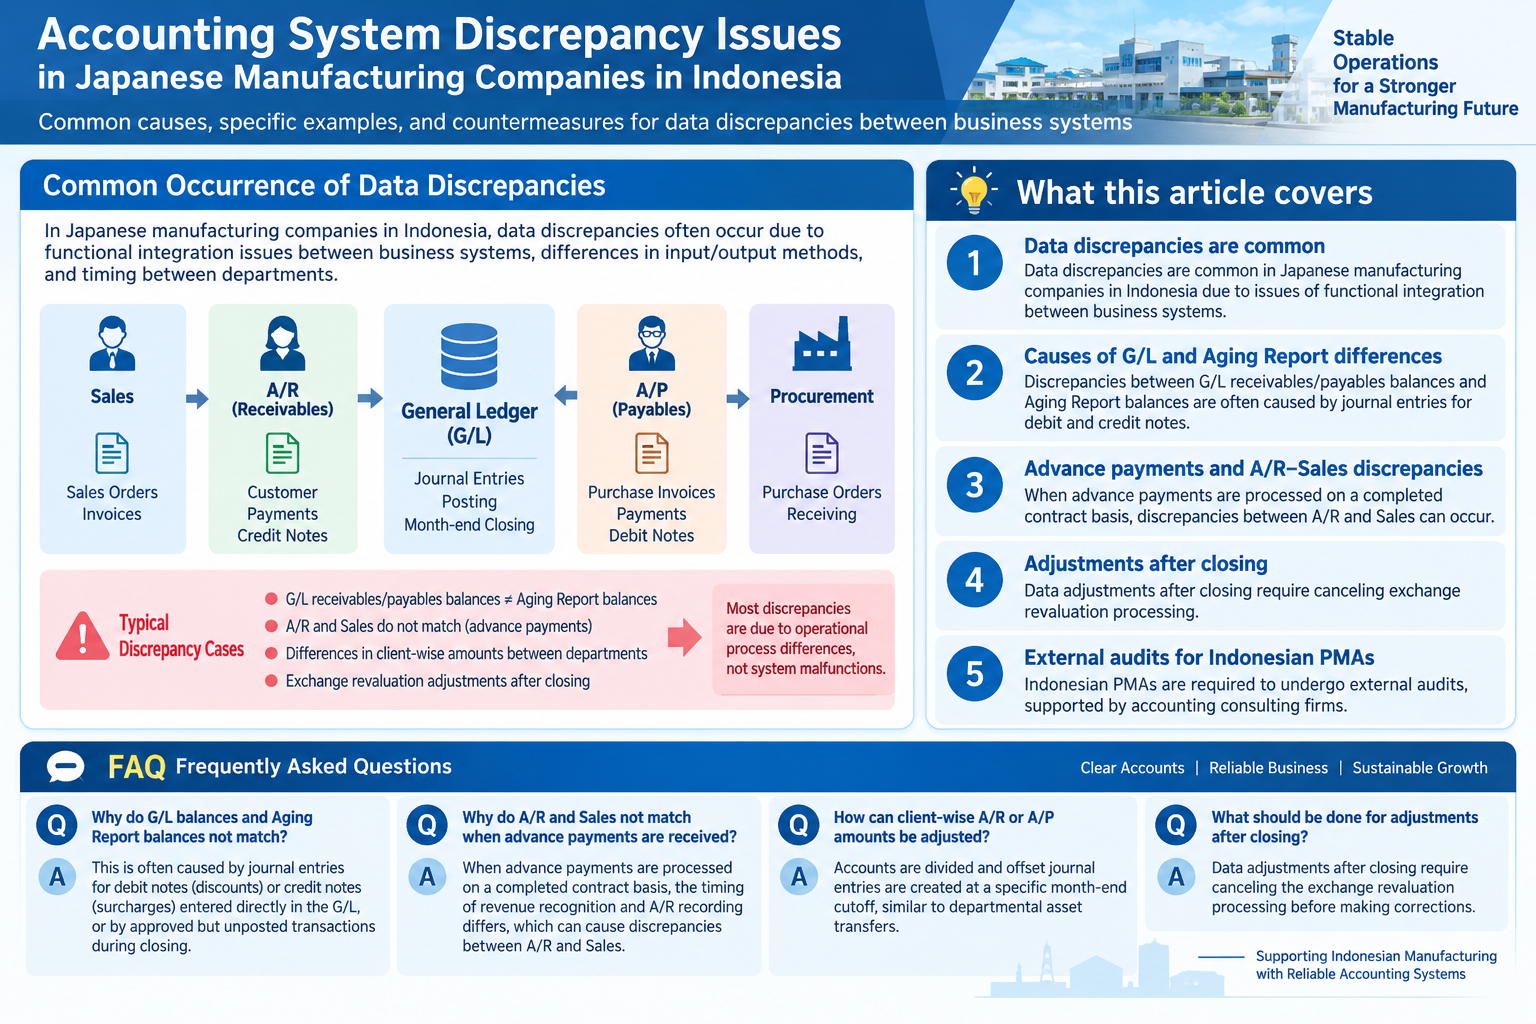
In Japanese manufacturing companies in Indonesia, data discrepancies can occur during the operation of business systems. These are often issues of functional integration between business systems, such as discrepancies between receivables and payables balances and the balances in the G/L, or discrepancies between receivables lists and sales.
-
-
Accounting Systems in Indonesia
The adoption rate of SaaS-based accounting systems in Indonesia is less than 8%, despite the advancement of SaaS technology. The continuous launch of new…
続きを見る
What this article covers
- Data discrepancies are common in Japanese manufacturing companies in Indonesia due to issues of functional integration between business systems.
- Discrepancies between G/L receivables/payables balances and Aging Report balances are often caused by journal entries for debit and credit notes.
- When advance payments are processed on a completed contract basis, discrepancies between A/R and Sales can occur.
- Data adjustments after closing require canceling exchange revaluation processing.
- Indonesian PMAs are required to undergo external audits, supported by accounting consulting firms.
Cases of Data Discrepancies Between Departments
Business systems are used by department personnel to utilize necessary functions, and information is relayed from upstream to downstream, but discrepancies can occur in the process. These discrepancies are mostly due to differences in input and output methods and timing between departments, not system malfunctions. Upon analysis, the causes can be summarized as follows:
Discrepancies Between Receivables (A/R) and Payables (A/P) Balances on the Ledger (G/L) and Aging Report
Theoretically, the beginning A/R and A/P balances carried over in the G/L should match the previous month's ending balances on the Aging Report, but they often do not.
- Direct input of A/P and A/R from G/L ⇒ This occurs by entering journal entries for debit notes for discounts or credit notes for surcharges directly in the G/L.
- The system is set up to generate A/P and A/R journal entries upon approval before posting. ⇒ It is necessary to check approved but unposted A/P and A/R transactions during closing.
When A/R and A/P Span Multiple Departments
Data discrepancies often become apparent when A/P and A/R balances do not match the G/L balances, but there are cases where the total amounts themselves do not match, and cases where the aggregated amounts per client do not match. To adjust the amounts per client for A/P and A/R, accounts are divided and offset journal entries are created at a specific month-end cutoff, similar to departmental asset transfers.
- (Debit) A/P (Client Code A) 10 (Credit) A/P (Client Code M) 30
- (Debit) A/P (Client Code B) 10
- (Debit) A/P (Client Code C) 10
Discrepancies Between A/R and Sales When Advance Payments Are Processed on a Completed Contract Basis
Sales personnel try to reconcile which A/R the current month's sales originated from, but the sales list displayed on the G/L does not necessarily match the A/R list for that month.
Returns and discounts can be corrected from A/R information using a Credit Note, but adjustments for foreign currency A/R exchange gains or losses and tax differences are made by accounting personnel using transfer slips in the G/L, leading to discrepancies between A/R information and A/R account balances on the G/L.
Additionally, when services are processed on a completed contract basis, advance payments are processed in the Down Payment account instead of the Sales account, and when converted to sales in the following month, comparing sales and A/R on a monthly basis will not match.
- Upon receiving advance payment (Debit) A/R 100 (Credit) Down Payment 100
- Upon completion of work (Debit) A/R 40 (Credit) Sales 40 (Debit) Down Payment 100 (Credit) Sales 100
Data Adjustments After Closing
It is common to realize after performing exchange revaluation at month-end and executing closing that an invoice was paid but forgotten to be entered. In such cases, it is necessary to cancel the closing and exchange revaluation, process the invoice settlement, and then re-execute the exchange revaluation and closing. If this operational procedure is not clear, modifying the invoice without canceling the exchange revaluation will result in the modification not being reflected in the exchange revaluation.
- End of November dollar A/R rupiah-based balance: 100
- Rupiah-based balance after November end exchange revaluation: 110
- Adjustments should be made against 100, but adjustments are made against 110.
Premature Input of A/R and A/P Settlement Processing Due to Delayed Closing
Exchange revaluation is to re-evaluate the A/P balance at month-end rates, but closing is usually delayed until the following month. If offset processing is done in the meantime, the month-end A/P balance will change.
- End of November rupiah-based balance: 100
- Balance after settlement processing input on December 1: 90
- Exchange revaluation should be done against 100, but it is done against 90.
Possible Countermeasures
Separate Realized and Unrealized Accounts
Exchange gains and losses consist of realized gains and losses occurring at settlement and unrealized gains and losses occurring at month-end revaluation. If these are not separated by account, it becomes difficult to narrow down transactions causing exchange gains and losses when tracing back.
- Forex Gain-Realized
- Forex Loss-Realized
- Forex Gain-Unrealized
- Forex Loss-Unrealized
In the system, it is possible to distinguish whether exchange gain/loss journal entries occurred at settlement or exchange revaluation, but in general accounting, filtering is usually only possible by account or client. Therefore, it is recommended to divide the accounts as above.
Clarify Operational Procedures for Irregular Processing
Data corrections for A/R and A/P after closing must be done after canceling the exchange revaluation, otherwise, the corrections will not be reflected in the month-end evaluation amount. Therefore, it is necessary to clarify the operational procedures for irregular correction processing.
Accounting Audits by External Auditors
Generally, audits refer to accounting audits by accounting firms, but statutory audits are only mandated for large companies as defined by the Company Law. The definition of a large company is "a company with capital of 500 million yen or more or liabilities of 20 billion yen or more," and companies may enter or exit the scope of audit obligations as they grow or decline.
Even privately held companies must undergo audits by accounting auditors (audit firms or certified public accountants) according to the law (Company Law Article 328), and if a large company subject to statutory audit does not conduct an audit, it is subject to fines for legal violations. However, in reality, there are cases of gray operations.
In Indonesia, foreign capital companies (PMA) are treated as large enterprises, and even if they qualify as small and medium-sized enterprises in Japan, they are obligated to undergo external audits as long as they are PMA.
Case: As Peter Drucker would say, although companies are public entities of society, deterioration of financial statements affects bank reviews, stock prices, bidding conditions, etc. Therefore, a habit of creating financial statements in a gray zone, "how to make them look clean," has developed, and when it surfaced, as in the Toshiba issue, the term "inappropriate accounting" was born.
External Business Audits and Internal Audits
Audits generally refer to accounting audits by external auditors, but since the establishment of JSOX, a rule on internal controls under the Financial Instruments and Exchange Act enacted in 2006, business audits evaluating compliance with internal controls have also been emphasized. Business audits are audits of business activities other than accounting operations (purchasing, production, logistics, sales, etc.) and organizations/systems, but ultimately they lead to shareholder protection by ensuring the appropriateness of financial statements.
- Accounting External Audit: Directly ensures the soundness of financial statements.
- Business External Audit: Ensures compliance with internal controls according to ISO or JSOX.
- Internal Audit: Ensures compliance with internal controls according to ISO or JSOX.
With the current systematization of operations, IT control is essential for evaluating internal controls. In Indonesia, during business audits, questions about ERP systems are narrowed down to the following three points:
- Whether the approval flow is appropriate
- Whether access rights to the system are appropriately set
- Whether there are operation manuals, operation manuals, etc.
The Role of Accounting Consulting Firms in Indonesia
In Japanese manufacturing companies in Indonesia, it is common to enter into bookkeeping outsourcing contracts or accounting advisor contracts with accounting consulting firms. When introducing an accounting system, the financial statements output after month-end closing are compared with the financial statements prepared by the accounting consulting firm to ensure accuracy. Additionally, the opening balances required at the start of using the accounting system are imported into the system or entered via transfer slips based on the trial balance prepared by the accounting consulting firm.
Indonesian accounting consulting firms, regardless of size, generally engage in the following activities:
- External audits (accounting audits, business audits)
- Bookkeeping outsourcing, payroll calculation outsourcing
- Tax support (PPh, PPN, customs duties, etc.)
- Visa and company establishment support
For Japanese companies, the commonly known JAC (Japan Asia Consultant) is familiar. I always keep three books authored by the representative of this company (company management, taxation, accounting) on my desk as my go-to references.
Data Required from Accounting Consulting Firms When Introducing Accounting Systems
When introducing an accounting system to clients contracted with accounting consulting firms, certain issues inevitably arise. I refer to these as the three mismatches.
- Opening balance mismatch: This occurs when internal data is modified after submission.
- Account mismatch: This troubles operators during mid-month data entry.
- Timing mismatch of opening balance alignment: This affects the system introduction schedule.
After submitting data to the accounting consulting firm, there may be cases where a missing invoice is discovered internally. In such cases, it may not be possible to request data correction from the accounting consulting firm in time, resulting in discrepancies between the invoice-based receivables and payables balances internally and the receivables and payables account balances sent from the accounting consulting firm, taking time to identify the cause.
Additionally, the accounting consulting firm's mission is to prepare accurate financial statements based on Indonesian company law. Given the large number of clients, it is necessary to use common account codes as much as possible to reduce management burden. This is unavoidable.
However, if mapping with internal account codes is insufficient, accounting input personnel may not know which account to enter gray transactions into, making it impossible to reconcile account balances at month-end. As a result, closing cannot be performed.
Furthermore, since the confirmed data after the previous month's closing arrives around the 20th of the following month at the earliest, it becomes difficult for the manager creating the system introduction project to manage the schedule.
Frequently Asked Questions | Accounting Issues in Indonesian Manufacturing
Based on the content of this article, frequently asked questions are briefly organized.
Why do data discrepancies occur in Japanese manufacturing companies in Indonesia?
Data discrepancies in Japanese manufacturing companies in Indonesia can occur due to issues of functional integration between business systems. Discrepancies between receivables and payables balances and the balances in the G/L, or discrepancies between receivables lists and sales, are common. These are not system malfunctions but are due to differences in input and output methods and timing between departments.
What should be noted during exchange revaluation processing?
When performing exchange revaluation processing, if data corrections are needed after closing, they must be done after canceling the exchange revaluation, otherwise, the corrections will not be reflected in the month-end evaluation amount. If closing is delayed and A/R and A/P settlement processing is prematurely input, the month-end A/P balance will change, so caution is needed.
How is the obligation for accounting audits defined in Indonesia?
In Indonesia, foreign capital companies (PMA) are treated as large enterprises and are obligated to undergo external audits. The definition of a large company is "a company with capital of 500 million yen or more or liabilities of 20 billion yen or more," and statutory audits are mandated. Even privately held companies must undergo audits by accounting auditors according to the law, and if a large company subject to statutory audit does not conduct an audit, it is subject to fines for legal violations.