


If materials are received but not used, the incurred cost for the month is 0. This is because the cost of materials used during the month becomes the incurred cost. If no manufacturing occurs, the manufacturing cost is also 0, and the cost of what is produced during the month becomes the incurred cost. If there are no sales, the cost of goods sold is also 0, and the cost of what is sold during the month becomes the incurred cost.
-
-
Cost Management Systems in Indonesia
Mass production factories in Indonesia adopt comprehensive cost accounting. Custom order production factories adopt individual cost accounting.
続きを見る
What this article covers
- If materials are not used, the incurred cost for the month is 0.
- WIP is recorded as an end-of-month balance on the B/S, not the P/L.
- Incurred material and processing costs for the month correspond to WIP manufacturing costs.
- Incurred costs of common materials are calculated using the average method.
- The end-of-month balance of WIP uses product conversion based on progress and the average method.
WIP Appears as an End-of-Month Balance on the B/S, Not the P/L
When I started studying cost accounting, it took me time to understand that manufacturing cost is the cost of producing products. After understanding this, I wondered why incurred material costs, manufacturing costs, and cost of goods sold are calculated using the three-part method, but the manufacturing cost of WIP in between is not calculated.
- Beginning material inventory + materials purchased during the month - ending material inventory = incurred material cost for the month
- Beginning WIP inventory + (incurred material cost for the month + processing cost for the month) - ending WIP inventory = manufacturing cost of products for the month
- Beginning product inventory + manufacturing cost of products for the month - ending product inventory = cost of goods sold for the month
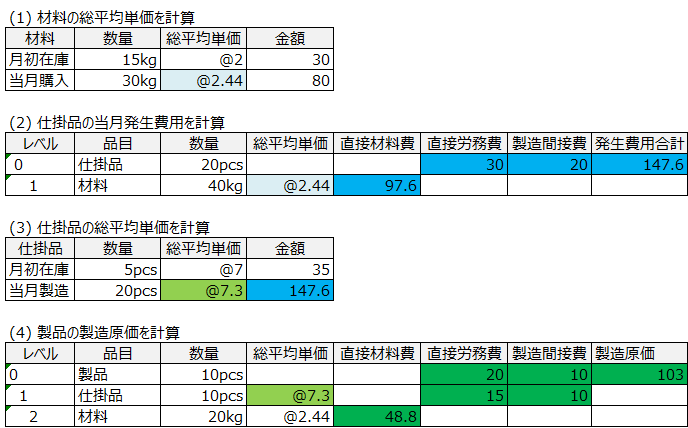
WIP at level 0 is considered incurred cost.
The purpose of financial accounting is to create the P/L and B/S, and it is sufficient to calculate incurred material costs, manufacturing costs, and cost of goods sold. Processing costs are allocated only to products, forming the P/L, but only the material cost portion appears in the end-of-month balance of WIP on the B/S.
Incurred Costs for the Month Correspond to WIP Manufacturing Costs in Accounting
From an asset perspective, WIP is the state between materials and products.
- Materials ⇒ In-process (costing of materials and incurrence of processing costs) ⇒ Products
Thus, when materials are used and costed, they become WIP, and processing costs are added. Therefore, "what became WIP this month" is synonymous with "what was costed this month," which corresponds to WIP manufacturing costs. The incurred costs for the month, "incurred material costs + incurred processing costs," are the WIP manufacturing costs for the month.
The manufacturing cost calculated as "WIP average unit cost x quantity + direct labor cost + manufacturing overhead" is the same as the result calculated by subtracting ending inventory from "beginning WIP inventory + incurred costs for the month - ending WIP inventory."
- Beginning material inventory + materials purchased during the month - ending material inventory = incurred material cost for the month
- Beginning WIP inventory + WIP manufacturing cost for the month - ending WIP inventory = manufacturing cost of products for the month
- Beginning product inventory + manufacturing cost of products for the month - ending product inventory = cost of goods sold for the month
Calculation of End-of-Month Balance of WIP
If it is necessary to allocate processing costs, which are currently allocated only to products, to WIP as well, incurred costs need to be apportioned between products and WIP. Material costs can be apportioned based on input quantity, but due to the difference in form between products and WIP, it is necessary to convert WIP into products based on progress. This is labor-intensive.
Therefore, a cost management system becomes important. One of the objectives of financial accounting is to calculate the end-of-month balance of WIP with allocated processing costs, which is difficult to do manually. The average method is used to calculate the allocation of common materials, which cannot be handled by the three-part method.
Incurred Costs of Common Materials That Cannot Be Calculated by the Three-Part Method
For common materials, it is possible to calculate incurred costs for the month using the three-part method from beginning inventory, purchases during the month, and ending inventory. However, due to the lack of input-based amounts, it is not possible to calculate incurred costs by item.
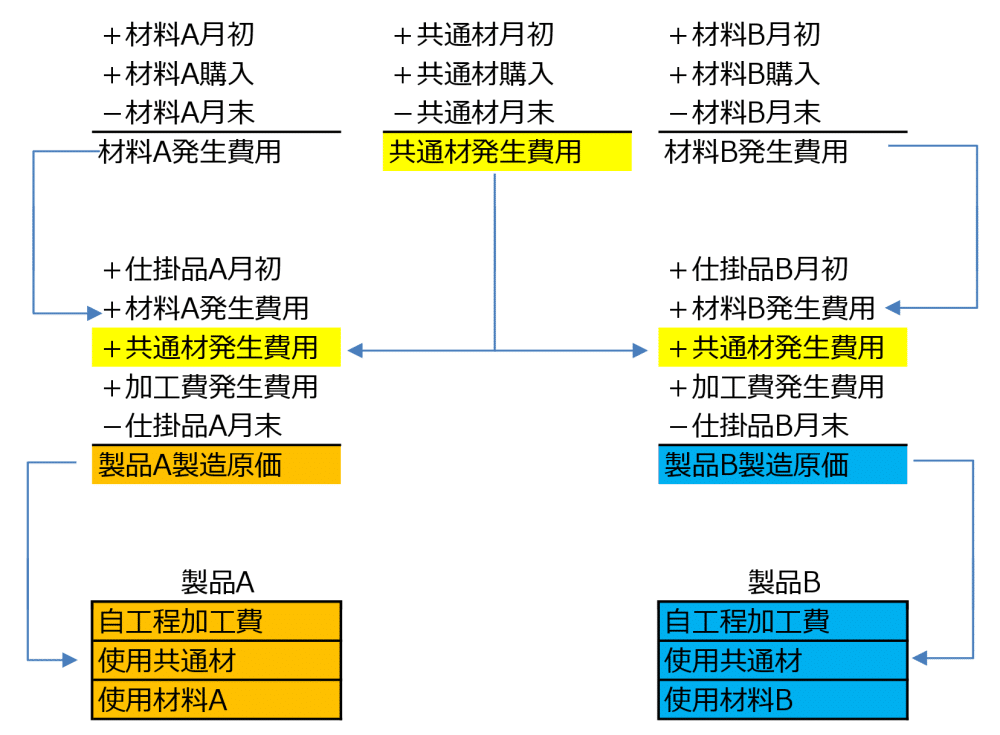
On the other hand, using the average method, it is possible to calculate not only the incurred costs of common materials but also the manufacturing cost by product based on the parent-child relationship of input results.
- Incurred costs of common materials Common material input quantity x average unit cost
- Cost of common materials included in manufacturing cost of Product A Common material usage quantity x average unit cost
Incurred Costs in the Accounting System Are "Above Material Costs and Below Manufacturing Costs"
The ultimate goal of the accounting system is to create the P/L and B/S, so it does not have an item master. In accounting terms, when materials are used, they become incurred material costs, and the portion that becomes products is recorded as manufacturing costs in the P/L. The portion that does not become products is recorded as WIP in the end-of-month WIP inventory on the B/S.
- Beginning material inventory + materials purchased during the month - incurred material costs (portion that became WIP) = ending material inventory
- Beginning WIP inventory + (incurred material costs + incurred processing costs) - manufacturing costs (portion that became products) = ending WIP inventory
Thus, incurred costs in the accounting system encompass "above material costs and below manufacturing costs," and all are considered incurred costs for manufacturing WIP.
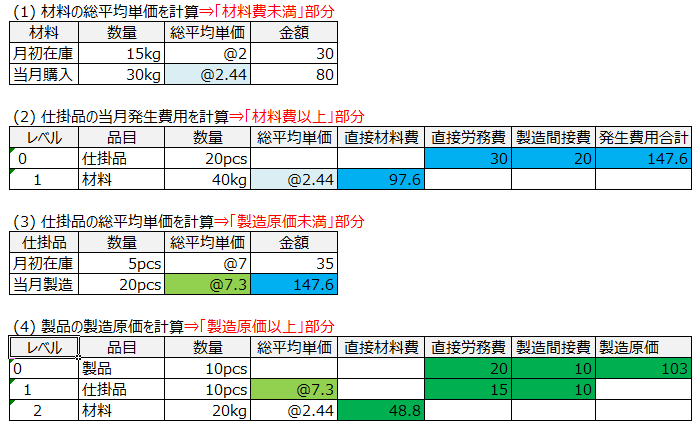
Monthly Incurred Costs Based on Production Results in the Cost Management System
In the cost management system, incurred costs are calculated for each WIP as "average unit cost of inputs x input quantity + processing costs of the process," and incurred costs by item and average unit cost are maintained by cost item (direct material cost, direct labor cost, manufacturing overhead). This allows monthly incurred costs to be managed as WIP manufacturing costs, and if the item is a product, it becomes the manufacturing cost. These are cumulative amounts aggregated from the initial process in order.
- Beginning material inventory + materials purchased during the month - incurred material costs (portion that became WIP 1) = ending material inventory
- Beginning WIP 1 inventory + (incurred material costs + incurred processing costs) - manufacturing cost of WIP 2 (portion that became WIP 2) = ending WIP 1 inventory
- Beginning WIP 2 inventory + manufacturing cost of WIP 2 - manufacturing costs (portion that became products) = ending WIP 2 inventory
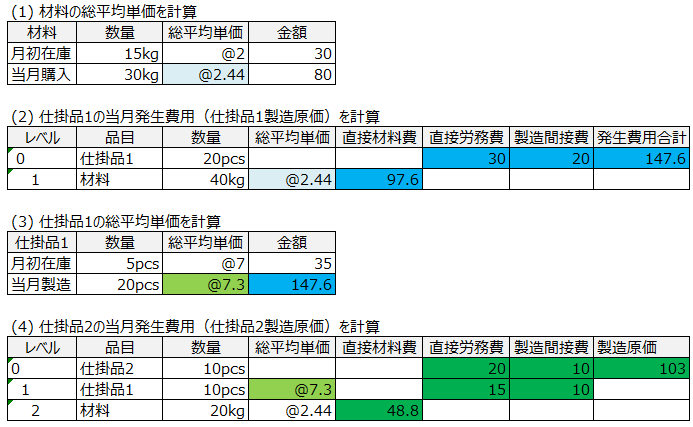
Monthly Incurred Costs Based on Input Results in the Cost Management System
"Incurred costs" refer to monthly incurred costs in accounting, and the end-of-month balance that did not become products is summarized as "WIP." In the cost management system, it refers to WIP manufacturing costs by item code. For example, if there is a BOM like "WIP 1⇒WIP 2⇒Product," incurred costs for each process are managed by cost item.
- Initial process: Material cost and processing cost 1 are incurred ⇒ WIP 1
- Next process: Processing cost 2 is incurred ⇒ added to WIP 1 to become WIP 2.
- Final process: Processing cost 3 is incurred ⇒ added to WIP 2 to become a product
To create a cost list by item for each BOM, it is necessary to manage incurred costs by process and cost item.
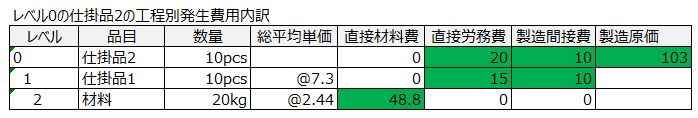
Table for Storing Calculation Results of the Cost Management System
Production result-based incurred costs are the manufacturing costs of WIP or products, and input result-based incurred costs are the monthly incurred costs. Monthly incurred costs do not necessarily become manufacturing costs and may remain as end-of-month WIP inventory.
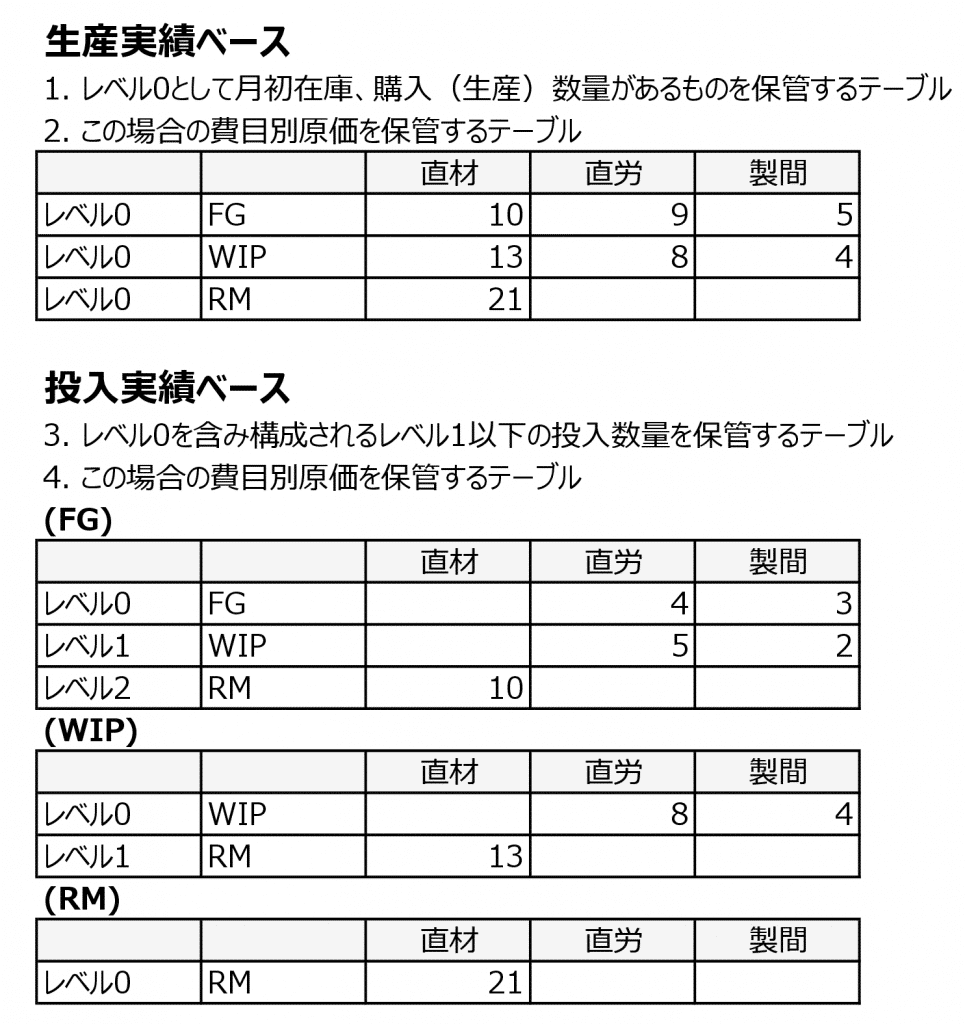
A table storing items with beginning inventory and purchase (production) quantities at level 0, and a table storing their cost by cost item, generate a cost item list (production result-based). Furthermore, a table storing input quantities for level 1 and below, which includes level 0, and a table storing their cost by cost item, generate a detailed composition of the cost item list (input result-based).
Frequently Asked Questions | Relationship Between Cost Accounting and WIP
Based on the content of this article, frequently asked questions are briefly organized.
How is WIP treated in accounting?
In accounting, WIP appears as an end-of-month balance on the B/S (balance sheet). When materials are used and costed, they become WIP, and processing costs are added. This makes the incurred costs for the month correspond to WIP manufacturing costs.
How is incurred material cost calculated?
Incurred material cost is calculated by adding beginning material inventory and materials purchased during the month, then subtracting ending material inventory. This calculation determines the actual material cost incurred during the month.
How does the cost management system manage incurred costs?
The cost management system calculates incurred costs for each WIP using the average unit cost of inputs and input quantity, along with processing costs. This allows incurred costs by item and average unit cost to be managed by cost item, and monthly incurred costs to be managed as WIP manufacturing costs.